


Stablecoins are digital property whose worth is pegged to that of a fiat foreign money, sometimes the U.S. greenback at a peg of $1.00 per token. In a earlier weblog publish, we described the speedy development of stablecoins by way of early 2025, highlighted modifications in stablecoins’ reserve-asset composition, and examined their reactions to Bitcoin value shocks. On this publish, we doc the expansion of stablecoins since our final publish. Then, we look at how shocks from outdoors the crypto trade can affect the composition of stablecoins’ reserve property. For our case research, we use the 2023 failure of Silicon Valley Financial institution (SVB) and its affect on USD Coin (USDC, issued by Circle), the second-largest stablecoin by market capitalization.
Latest Progress of Stablecoins
Since our final publish in April 2025, the market capitalization of U.S. greenback stablecoins has elevated by $71 billion (30 %) to about $308 billion not too long ago, as proven within the chart beneath. This era coincides with the passage of the GENIUS Act in July 2025, which established the primary federal regulatory framework for cost stablecoins.
Stablecoin Market Capitalization
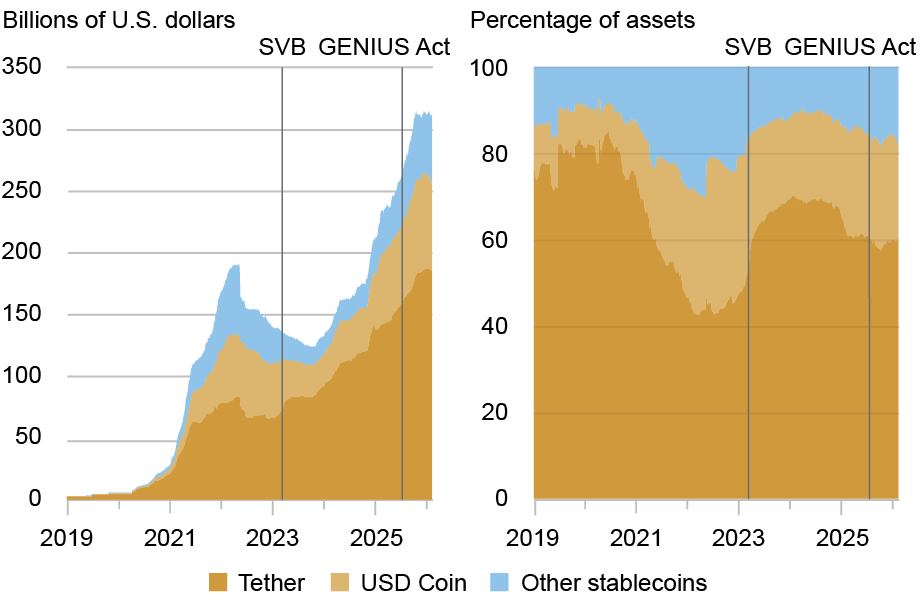
Be aware: The vertical traces point out, respectively, SVB’s failure in March 2023 and the passage of the GENIUS Act in July 2025.
The stablecoin trade stays extremely concentrated, with the 2 largest issuers, Tether (USDT) and USDC, accounting for over 80 % of trade property. The reserve composition of those stablecoins differs considerably: USDC’s attested reserves consist primarily of money and short-term U.S. authorities securities. In distinction, company bonds, gold bars, Bitcoin, secured loans, and “different investments” accounted for almost 24 % of USDT’s attested reserves as of December 2025.
Reserve-Asset Composition and Exterior Shocks
In prior posts, we examined the affect of optimistic and adverse crypto value shocks on web flows into stablecoins. Right here we research a complementary query: how do non-crypto shocks have an effect on web flows into stablecoins and the composition of their reserve property? This query is essential given stablecoins’ growing interconnectedness with conventional monetary markets. To reply it, we doc the modifications in USDC’s reserve property following SVB’s failure in March 2023.
On March 11, 2023, Circle reported that roughly 8 % of USDC’s reserves had been held at SVB, which had been positioned into FDIC receivership yesterday. Following Circle’s announcement, USDC’s secondary market value dropped significantly beneath $1.00, and it skilled notable web outflows. Along with these results, the composition of the Circle Reserve Fund (CRF), a cash market mutual fund (MMF) whose shares can solely be bought by Circle, modified considerably. (The CRF accounts for roughly 86 % of USDC’s reserve property as of March 2026.)
The chart beneath reviews the weighted common maturity (WAM)—a measure of interest-rate sensitivity—for the CRF versus the median U.S. Treasury-only (TO) MMF. Previous to SVB’s collapse, the CRF’s WAM exceeded that of the median TO MMF. Following SVB’s failure, the CRF’s WAM fell beneath that of the median TO fund and has remained beneath the fifth percentile of the WAM distribution of TO MMFs. Thus, following SVB’s failure, the CRF diminished its interest-rate threat publicity, on steadiness.
Weighted Common Maturity: Circle Reserve Fund vs. Treasury-Solely MMFs
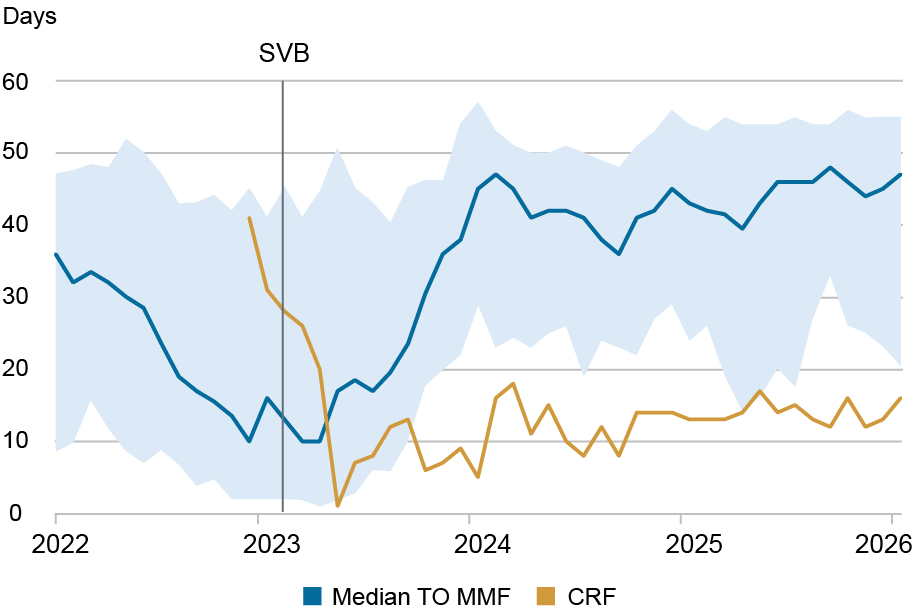
Notes: The information are at a month-to-month frequency. “TO MMF”: Treasury-Solely MMF. “CRF”: Circle Reserve Fund (inception date is November 2022). The sunshine-blue shaded space denotes the fifth to the ninety fifth percentile vary of the WAM distribution amongst TO MMFs. The vertical line signifies when SVB failed in March 2023.
Turning to portfolio composition, the charts beneath present that, following SVB’s collapse, the CRF’s holdings of repurchase agreements (repos) spiked from zero to over 90 % of its web property. This share has since retreated some however nonetheless stands at 69 %, above the distribution of TO MMFs’ repo holdings as a share of web property. Thus, following the SVB shock, the CRF diminished its interest-rate threat publicity and considerably restructured its counterparty threat publicity.
Repo Holdings: Circle Reserve Fund vs. Treasury-Solely MMFs
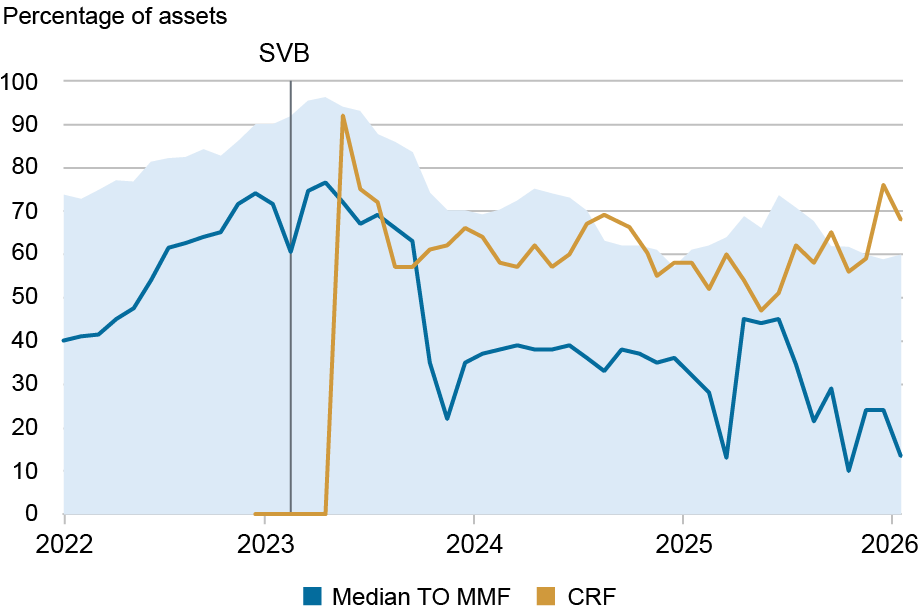
Notes: The information are at a month-to-month frequency. “TO MMF”: Treasury-Solely MMF. “CRF”: Circle Reserve Fund (inception date is November 2022). The sunshine-blue shaded space denotes the fifth to the ninety fifth percentile vary of repo holdings as a share of web property amongst TO MMFs. The vertical line signifies when SVB failed in March 2023.
Circle Reserve Fund’s Repo Holdings by Counterparty Kind
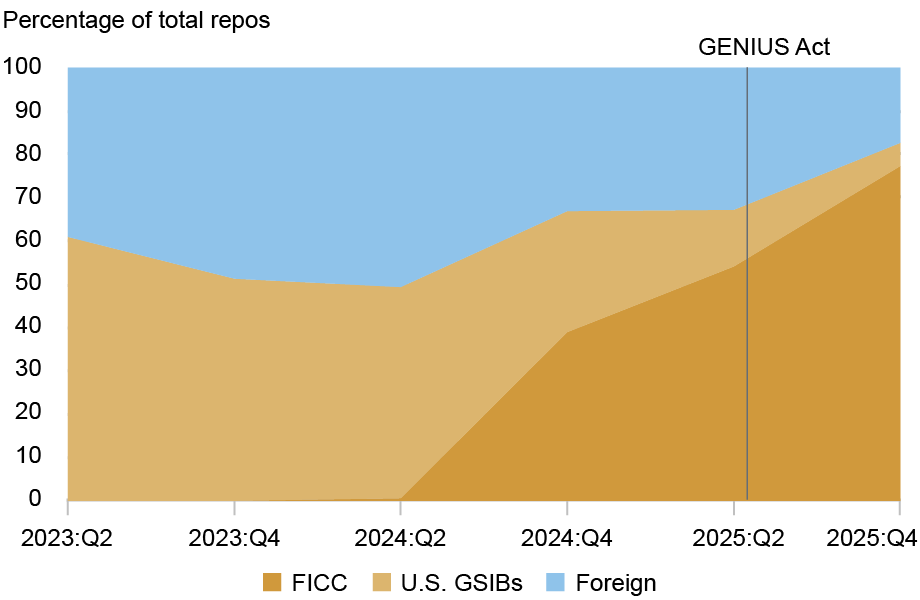
Notes: The information are at a quarterly frequency. “FICC”: Fastened Revenue Clearing Company.
Inspecting the CRF’s repo counterparty composition extra intently, we observe a speedy shift beginning in late 2024: The share of Fastened Revenue Clearing Company (FICC)-sponsored repos, whose final counterparties are typically entities with a web demand for funding, similar to hedge funds, grew quickly and reached 77 % by 2025:This autumn (see the chart above).
Subsequent, we flip to USDC’s reserve property held outdoors of the CRF, which have averaged 12 % of complete reserves because the begin of 2023. How has the composition of those non-CRF reserves developed since SVB’s failure? The chart beneath depicts the fraction of USDC’s reserves held as financial institution deposits. USDC’s financial institution deposits rose briefly after SVB’s failure however have since remained beneath the degrees that prevailed earlier than SVB’s failure.
Additionally, the sorts of banks holding USDC’s money modified markedly, shifting from a mixture of World Systemically Vital Banks (GSIBs) and non-GSIBs (together with SVB and Signature Financial institution) in February 2023 to predominantly GSIBs by April 2023—with Circle reporting “in extra of 90% of money” held at GSIBs. In different phrases, after SVB’s collapse, USDC’s financial institution deposits grew to become, and have remained, concentrated in GSIBs.
Fraction of USDC’s Reserves Held at Banks
Share of USDC’s property
Summing Up
Following SVB’s failure in March 2023, the composition of USDC’s main reserve asset, held in an MMF, modified notably: the common maturity of its reserve property declined considerably; its repo holdings surged and have become concentrated in FICC in recent times. As well as, its direct deposits with banks shifted from a mixture of GSIBs and non-GSIBs to GSIBs. General, the SVB occasion triggered a change in the kind of threat held by one of many largest stablecoin issuers, away from interest-rate threat and towards counterparty threat. These modifications spotlight the rising interconnectedness between conventional finance and new, rising monetary applied sciences.
Kenechukwu Anadu is a vp of the Federal Reserve Financial institution of Boston’s Supervision, Regulation, and Credit score Division.

Pablo Azar is a monetary analysis economist within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
Sean Baker is a threat analyst within the Federal Reserve Financial institution of Boston’s Supervision, Regulation, and Credit score Division.

Marco Cipriani is head of Cash and Funds Research within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.

Thomas M. Eisenbach is a monetary analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
Mattia Landoni is an affiliate professor of finance at China Europe Worldwide Enterprise College (CEIBS).
Gabriele La Spada is a monetary analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
Marco Macchiavelli is an assistant professor of Finance on the College of Massachusetts, Amherst.
J. Christina Wang is a principal economist and coverage advisor within the macroeconomic/monetary markets part of the Federal Reserve Financial institution of Boston.
Find out how to cite this publish:
Kenechukwu Anadu, Pablo D. Azar, Sean Baker, Marco Cipriani, Thomas M. Eisenbach, Mattia Landoni, Gabriele La Spada, Marco Macchiavelli, and J. Christina Wang, “Stablecoins and (Non)Crypto Shocks: A 2026 Replace,” Federal Reserve Financial institution of New York Liberty Road Economics, July 31, 2026, https://doi.org/10.59576/lse.20260731
BibTeX: View |
Disclaimer
The views expressed on this publish are these of the writer(s) and don’t essentially mirror the place of the Federal Reserve Financial institution of New York or the Federal Reserve System. Any errors or omissions are the duty of the writer(s).