


Smaller is best. At the least that’s what many buyers consider on the subject of fairness investing in India.
And the info does appear to assist this view. During the last twenty years, mid and small cap indices have delivered considerably larger returns than Nifty 50. Nicely, no less than on the floor.
However is it actually that easy? Does going smaller at all times imply larger returns? And extra importantly, are you able to deal with the journey?
What Does This Submit Cowl?
On this put up, allow us to examine the efficiency of 8 cap-based indices over the past 21 years (April 1, 2005, to March 31, 2026). I’ve thought-about the Worth index (and never the Whole Returns index) for the evaluation. Have thought-about 250-day 12 months for evaluation on this put up. We are going to take a look at calendar 12 months returns, CAGR, rolling returns, and threat metrics to grasp how these indices have truly behaved.
The 8 cap-based indices thought-about for this evaluation:
- Nifty 50
- Nifty 100
- Nifty 500
- Nifty Massive & Midcap 250
- Nifty Subsequent 50
- Nifty Midcap 150
- Nifty Smallcap 250
- Nifty Microcap 250
Disclaimer: I’ve used Claude AI extensively for this efficiency evaluation. Whereas I’ve performed a number of pattern checks and the findings look positive directionally, it might nonetheless include inaccuracies. Please do additional analysis or seek the advice of your funding adviser earlier than appearing on the knowledge shared on this put up.
The Fundamentals: How Are These Indices Totally different?
Earlier than we get to the numbers, a fast refresher.
Nifty 50 tracks the 50 largest corporations by market capitalization. Nifty 100 extends this to the highest 100. Nifty 500 is a broad market index masking the highest 500 corporations. Nifty Massive & Midcap 250 combines the highest 100 massive caps and the following 150 midcaps. Nifty Subsequent 50 tracks corporations ranked 51-100 by market cap. Nifty Midcap 150 covers corporations ranked 101-250. Nifty Smallcap 250 covers corporations ranked 251-500. And Nifty Microcap 250 goes even additional down the market cap spectrum.
Be aware that as you progress down the market cap ladder, you might be basically investing in smaller and fewer liquid corporations. As an investor, the expectation is that you just get compensated for this extra threat via larger returns. However does the info assist this? Let’s discover out.
Calendar 12 months Returns

Take a look at the typical calendar 12 months returns throughout these 21 years. Nifty 50 delivered 14.8%. Nifty Midcap 150 delivered 21.2%. And Nifty Microcap 250 delivered 26.2%. The sample is obvious. Smaller the shares, larger the typical returns.
However now take a look at the person years. In 2008, Nifty 50 fell 51.8%. Nifty Smallcap 250 fell 69.1%. Nifty Microcap 250 fell 75.2%. In 2018, Nifty 50 was up 3.2% whereas Nifty Microcap 250 was down 27.7%. And in 2011, Nifty 50 fell 24.6% whereas Nifty Microcap 250 fell 41.6%.
The journey will get considerably rougher as you go smaller, proper?
Within the good years, the smaller indices ship wonderful returns. In 2009, Nifty Subsequent 50 delivered 127.9%. Nifty Microcap 250 delivered 118.4%. In 2014, Nifty Microcap 250 was up 103.3%. And in 2007, Nifty Smallcap 250 was up 94.9%.
Good years are positive, however through the funding journey, dangerous years matter too.
Consolidated Efficiency: The place the Actual Story Lies
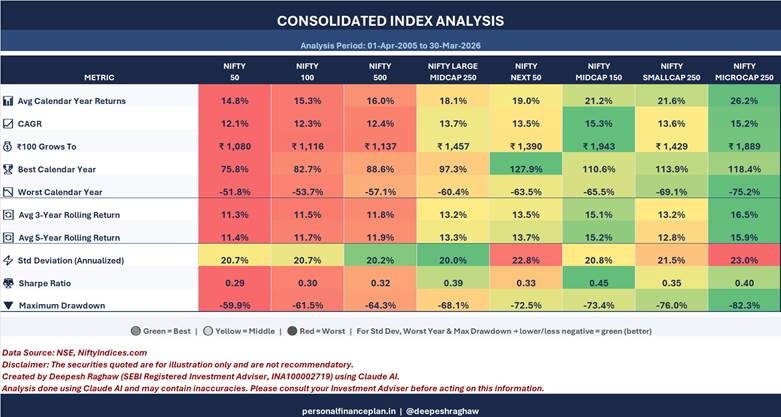
Common Returns vs CAGR: Thoughts the Hole
The common calendar 12 months return for Nifty Microcap 250 is 26.2%. However the CAGR is just 15.2%. That’s an enormous hole of about 11 share factors.
For Nifty 50, the typical return is 14.8% and the CAGR is 12.1%. The hole is just about 2.7 share factors.
Why does this occur? Due to volatility drag. The extra risky the returns, the bigger the hole between common returns and CAGR. Therefore, whereas the typical returns for smaller indices look spectacular, the precise wealth creation (captured by CAGR) shouldn’t be as dramatic because it seems.
Rs 100 Grows To…
Should you had invested Rs 100 in April 2005, right here’s what it will have change into by March 2026:
- Nifty 50: Rs 1,080
- Nifty Midcap 150: Rs 1,943
- Nifty Smallcap 250: Rs 1,429
- Nifty Microcap 250: Rs 1,889
Nifty Midcap 150 truly created extra wealth than Nifty Microcap 250. Sounds a bit unusual. Doesn’t it? Regardless of Microcap 250 having larger common returns. That is the volatility drag at work.
Threat: The Uncomfortable Fact
Nifty 50 has a typical deviation of 20.7% and a most drawdown of -59.9%.
Nifty Microcap 250 has a typical deviation of 23% and a most drawdown of -82.3%. An 82% fall means your Rs 1 lac turns into Rs 17,700. And you then want a 449% rise simply to get again to the place you began.
Now to the Sharpe ratio (threat adjusted returns). Greater the higher.
Nifty Midcap 150 has the very best Sharpe ratio at 0.45. Nifty 50 has the bottom at 0.29.
Nifty Small Cap 250 at 0.35. Nifty Microcap 250 sits at 0.40, decrease than Midcap 150.
Rolling Returns: Consistency Issues
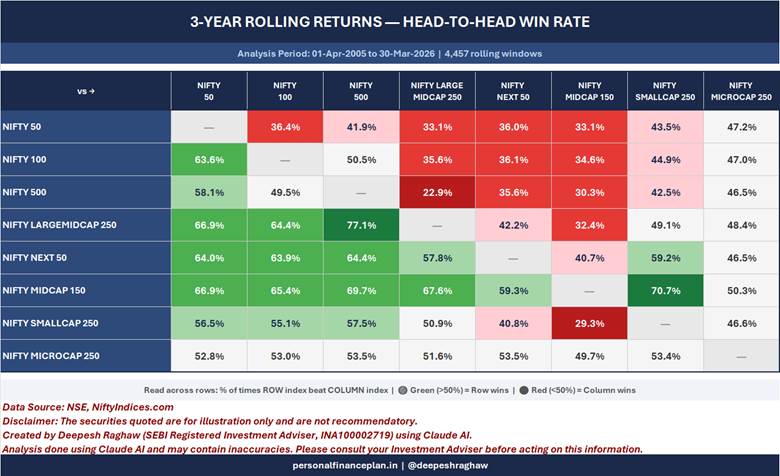
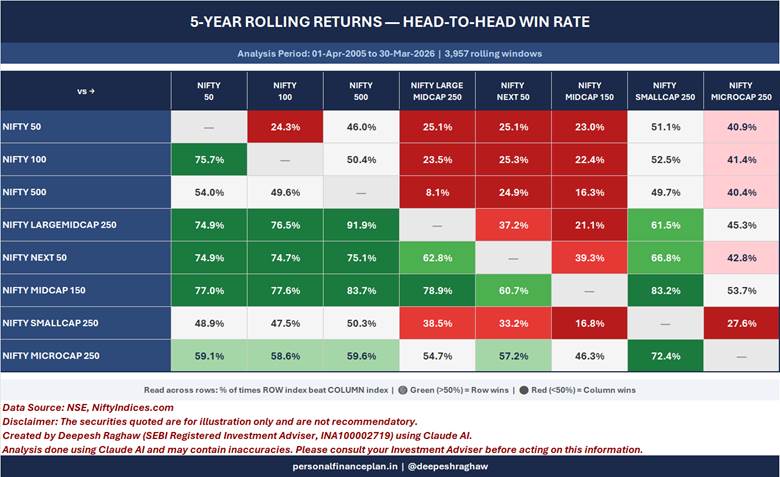
Rolling returns offer you a way of consistency.
To me, the shock half is that Nifty Small Cap 250 dropping out to Nifty Midcap 150 over 80% of the time in 5-year rolling returns. 70% in 3-year rolling returns.
You’d have anticipated Nifty Small Cap 250 to beat Nifty Midcap 150 over the long-term. In spite of everything, it has even smaller shares. It does appear to outperform point-to-point over 21 years, for those who take a look at simply the typical calendar 12 months returns. Nevertheless, if you take a look at the CAGR, rolling returns and so forth., the small cap index falls behind fairly a bit.
And that’s not it. On 5-year rolling returns, Nifty Smallcap 250 beat Nifty 50 solely about 48.9% of the time. Lower than half. So, regardless of the upper common returns, for those who had invested in Nifty Smallcap 250 for any random 5-year interval, there was a superb probability Nifty 50 would have performed higher.
How do you employ this data?
- Don’t belief the info blindly. There could also be errors in my evaluation.
- The intent of this put up is NOT to reveal superiority of 1 index over one other. And also you must also NOT evaluation this evaluation on this context. You don’t need to be the most effective to be comfortable.
- Don’t simply give attention to the returns. I’ve proven long-term knowledge. Therefore, for among the indices, the long-term knowledge might look very spectacular. Firstly, previous efficiency doesn’t assure future efficiency. Secondly, the long-term knowledge normally appears to be like fairly easy. It can conveniently conceal the risky journey {that a} explicit index would have taken you thru. Or relatively you are likely to ignore these elements and focus merely on the returns. Lengthy-term, for many buyers, is only a collection of short-term investments. Therefore, earlier than contemplating any of the indices chosen for this put up, you need to look past the returns knowledge as effectively.
- Conviction in an funding technique is important. No funding technique, regardless of how good, works on a regular basis. No funding technique, regardless of how dangerous, fails on a regular basis. The ups and downs will check your persistence. Should you lack conviction, you’ll largely probably soar the ship on the mistaken time.
- Concentrate on constructing a low-cost diversified long-term portfolio.
The Caveats
- Previous efficiency (or outperformance) doesn’t assure future efficiency (outperformance).
- Whereas I’ve thought-about the info from April 1 2005, many of those indices had been launched a lot later. Therefore, the outperformance by these issue indices might merely be a results of back-fitting. I wrote a >put up in early 2025 the place I in contrast the efficiency of issue indices since launch.
- I’ve proven returns for indices. You don’t spend money on indices. You spend money on index funds or ETFs. Such merchandise can have monitoring distinction for varied causes and can decrease your returns. The monitoring distinction might enhance if the underlying shares are much less liquid.
Supply
Disclaimer: Registration granted by SEBI, membership of BASL, and certification from NISM by no means assure efficiency of the middleman or present any assurance of returns to buyers. Funding in securities market is topic to market dangers. Learn all of the associated paperwork rigorously earlier than investing.
This put up is for schooling goal alone and is NOT funding recommendation. This isn’t a advice to take a position or NOT spend money on any product. The securities, devices, or indices quoted are for illustration solely and should not recommendatory. My views could also be biased, and I’ll select to not give attention to elements that you just think about necessary. Your monetary targets could also be totally different. You might have a special threat profile. Chances are you’ll be in a special life stage than I’m in. Therefore, you need to NOT base your funding choices primarily based on my writings. There isn’t any one-size-fits-all answer in investments. What could also be a superb funding for sure buyers might NOT be good for others. And vice versa. Due to this fact, learn and perceive the product phrases and circumstances and think about your threat profile, necessities, and suitability earlier than investing in any funding product or following an funding strategy.