

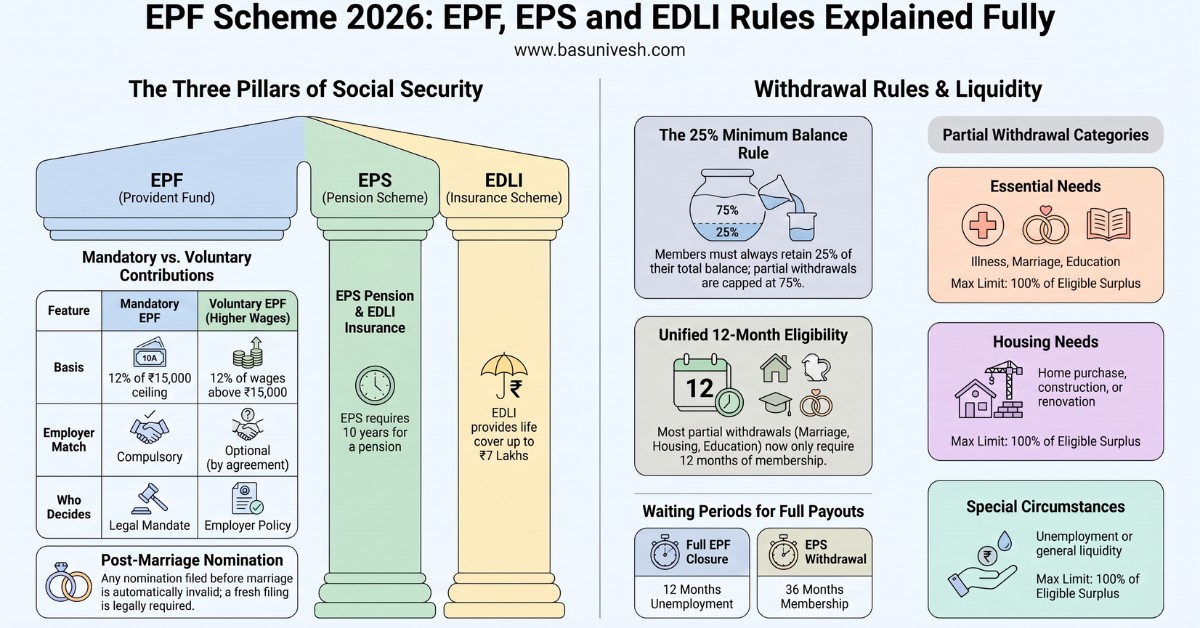

EPF Scheme 2026 defined absolutely: EPF withdrawal, EPS pension, and EDLI insurance coverage modifications with examples, verified towards the official gazette textual content.
Your wage slip has proven that acquainted 12% PF deduction each month for years. You by no means questioned it. You simply assumed it should continue to grow quietly till you retire. Then all of a sudden, information channels and WhatsApp forwards began screaming that the federal government has changed the complete EPF regulation. Some stated your PF is now capped at Rs.1,800. Some stated you can not withdraw your personal cash for an entire 12 months. Some stated your nomination is cancelled.
Naturally, this created panic amongst lakhs of EPFO subscribers.
So let me clear the air, and this time with full certainty, as a result of I’ve gone by means of the precise gazette notifications, not summaries or information reviews about them. On twenty ninth June 2026, the Ministry of Labour and Employment concurrently notified three separate schemes underneath the Code on Social Safety, 2020, every changing a decades-old predecessor:
- The Workers’ Provident Funds Scheme, 2026 (Notification G.S.R. 525(E)), changing the EPF Scheme, 1952
- The Workers’ Pension Scheme, 2026 (Notification G.S.R. 527(E)), changing the Workers’ Pension Scheme, 1995 and the Workers’ Household Pension Scheme, 1971
- The Workers’ Deposit-Linked Insurance coverage Scheme, 2026 (Notification G.S.R. 526(E)), changing the EDLI Scheme, 1976
Most subscribers solely ever hear in regards to the first one and assume it covers the whole lot. It doesn’t. Your retirement safety really rests on all three legs collectively, your provident fund, your pension, and your life insurance coverage cowl by means of EDLI. Allow us to undergo each real change throughout all three, verified paragraph by paragraph towards the notified textual content.
What Precisely Modified, And What Stayed The Similar
Consider this much less as a model new retirement product and extra as a authorized improve. Earlier, EPF was ruled by the Workers Provident Funds and Miscellaneous Provisions Act, 1952. That Act has now been subsumed underneath the Code on Social Safety, 2020, the umbrella labour code the federal government has been implementing in phases. The three schemes above are merely the detailed rulebooks framed underneath this new Code.
For those who had been already a member underneath the previous EPF Scheme 1952 or EPS 1995, you robotically proceed as a member underneath the corresponding 2026 scheme. You should not have to open a brand new account, apply afresh, or full any new formalities. Your present stability, Common Account Quantity, contribution historical past, and accrued advantages carry ahead with none interruption.
What Stays Precisely The Similar In EPF
- The obligatory EPF contribution charge stays 12% of wages from each worker and employer, with 10% persevering with for sure notified institutions.
- The statutory wage ceiling for obligatory EPF contribution stays Rs.15,000 per 30 days, at present unrevised. Value understanding: the EPF Scheme 2026 itself doesn’t hardcode this determine anyplace in its textual content. It solely refers to a “wage ceiling notified by the Central Authorities occasionally”, so Rs.15,000 is the administratively present quantity, not a set authorized determine, and it might change by means of a separate notification while not having a contemporary Scheme.
- Your UAN, KYC, and portability throughout employers stay intact and unaffected.
- The EPF rate of interest framework is untouched by this notification. The present charge of 8.25% continues, and any future revision occurs by means of a separate EPFO announcement, precisely as earlier than. Do observe, this can be a totally different charge from the 8.5% minimal the Central Authorities has dedicated to on EPS and EDLI cash it holds in its personal Public Account; that 8.5% flooring applies to the pooled government-held corpus, to not the curiosity credited to your particular person EPF passbook.
- Tax remedy of EPF contributions, curiosity, and withdrawal stays the identical. Full 5 years of steady service and your withdrawal continues to be tax free.
- Full withdrawal on retirement is allowed from age 55, whereas EPS month-to-month pension eligibility stays age 58. These are two totally different age thresholds underneath two totally different schemes, so don’t confuse one for the opposite.
The Massive Confusion: Obligatory EPF vs Voluntary EPF on Larger Wages vs VPF
That is the place most workers are genuinely confused, and the confusion is comprehensible as a result of the EPF Scheme 2026 makes use of the phrase “voluntary” in two fully totally different contexts.
Earlier, many employers calculated EPF at 12% of the worker’s precise fundamental wage plus dearness allowance, even when that wage crossed the statutory ceiling of Rs.15,000. For instance, in case your fundamental wage is Rs.50,000, your employer might have been deducting 12% of Rs.50,000, that’s Rs.6,000, and matching it with an equal employer contribution.
The EPF Scheme 2026 now clearly separates this into two distinct buckets.
Obligatory EPF Contribution
That is strictly tied to the statutory wage ceiling of Rs.15,000, no matter your precise wage.
- Worker contribution: 12% of Rs.15,000 = Rs.1,800
- Employer contribution: 12% of Rs.15,000 = Rs.1,800 (break up as per EPS allocation guidelines)
This Rs.1,800 from you and Rs.1,800 out of your employer is the legally obligatory portion. No employer can refuse to contribute even this minimal quantity.
Voluntary EPF on Larger Wages
In case your fundamental wage is above Rs.15,000, say Rs.50,000, and also you and your employer select to proceed contributing on the complete Rs.50,000 as an alternative of limiting it to Rs.15,000, that further portion is now formally labeled as voluntary contribution on greater wages.
- Worker EPF: 12% of Rs.50,000 = Rs.6,000
- Employer EPF: 12% of Rs.50,000 = Rs.6,000 (provided that the employer agrees to proceed this observe)
Your employer is underneath no authorized obligation to match your contribution above Rs.15,000. It has three choices: proceed contributing in your full greater wages as earlier than, partially cut back contributions above the ceiling, or limit future contributions strictly to the statutory Rs.15,000 ceiling. The Scheme additionally explicitly permits both aspect to scale back or discontinue such voluntary contributions at any time. Verify together with your HR to know which path your organisation intends to take.
Voluntary Provident Fund (VPF)
That is totally different from each of the above. VPF is an additional quantity that solely you, the worker, select to contribute over and above your common EPF. Your employer by no means matches this VPF quantity. For instance, in case your EPF contribution is Rs.6,000 and also you moreover go for Rs.10,000 as VPF, your whole month-to-month contribution turns into Rs.16,000, however your employer’s contribution stays capped at Rs.6,000, or decrease, relying on their coverage. VPF continues to be some of the tax environment friendly methods to construct a big retirement corpus, because it earns the identical EPF rate of interest and enjoys the identical tax remedy, topic to the 5 12 months steady service situation.
| Characteristic | Obligatory EPF | Voluntary EPF on Larger Wages | Voluntary Provident Fund (VPF) |
| Contribution Foundation | 12% of Rs.15,000 wage ceiling | 12% of wages above Rs.15,000, by mutual settlement | Further worker contribution over and above EPF |
| Worker Contribution | Obligatory | Voluntary | Voluntary |
| Employer Contribution | Obligatory | Provided that employer agrees | No employer matching |
| Who Decides | Regulation | Employer coverage or mutual settlement | Worker alone |
Withdrawal Guidelines Received Genuinely Easier: 13 Causes Diminished to three Classes
Beneath Para 46 of the notified EPF Scheme 2026, all partial withdrawal causes are actually grouped into three broad classes, every capped at 100% of your “eligible member surplus”, which is your whole stability minus the 25% minimal stability you should at all times retain.
- Important Wants – sickness of self or household (after 12 months of Fund membership, no frequency restrict specified), training of self or household (after 12 months, as much as 10 instances throughout your membership), and marriage of self or household (after 12 months, as much as 5 instances throughout your membership).
- Housing Wants – buy of a flat or home, buy of a plot for development, home development, reimbursement of a house mortgage taken for buy or development, or extension, alteration, renovation or enchancment of an present home. Capped at 100% of eligible surplus, restricted to five withdrawals throughout your membership.
- Particular Circumstances – accessible after 12 months of Fund membership, as much as 100% of eligible surplus, while not having to state a selected cause, however restricted to twice in a monetary 12 months.
Here’s a genuinely essential element the textual content confirms clearly: members who depart employment earlier than finishing even 12 months of membership stay eligible to use for partial withdrawal underneath this Para, capped at their eligible surplus on the date of the declare (Para 46(5)). That is the availability that offers you actual, pretty instant entry to funds for those who lose your job early in your profession.
Uniform 12-Month Membership Requirement Replaces The Outdated 5 to 7 12 months Rule
Let me bust a fable instantly. Many workers nonetheless imagine that to withdraw for a home or a marriage, they want at the very least 5 to 7 years of service, as a result of that’s the way it labored for many years. That’s now not true. A uniform minimal of 12 months of EPF membership now applies to most partial withdrawal classes, a genuinely important aid for early profession professionals and frequent job switchers.
The 25% Minimal Stability Rule You Should Know
Whereas partial withdrawals have turn out to be simpler, EPFO has in-built a safeguard. Members should at all times retain at the very least 25% of their whole EPF stability, which the Scheme defines as “minimal stability”. Each partial withdrawal, throughout all three classes, is capped at 100% of your eligible surplus, that means your whole stability minus this 25% flooring. Virtually, this implies the utmost you may ever entry by means of a partial withdrawal is 75% of your whole stability, by definition, at all times.
Suppose your whole EPF stability is Rs.8 lakh. Your minimal stability to guard is Rs.2 lakh, 25% of the overall. Your eligible surplus is Rs.6 lakh, and that Rs.6 lakh is absolutely the ceiling for any partial withdrawal, regardless of which class you apply underneath.
Misplaced Your Job? Right here Is Precisely What The Gazette Textual content Says
That is the purpose that deserves your most cautious consideration, and I wish to stroll you thru it exactly because the notified textual content describes it, as a result of there are two genuinely separate provisions at play right here, and mixing them up results in the unsuitable expectations.
Full Closure Of Your Account: A Flat 12-Month Bar
Para 49 offers with full withdrawal, that means absolutely closing your EPF account. It permits 100% withdrawal on retirement after age 55, everlasting incapacity, everlasting migration overseas, retrenchment, or a mutually agreed voluntary retirement scheme, every with its personal brief ready interval, generally as little as 2 months.
However for the peculiar case, that means you merely resign or your job ends for causes outdoors these particular classes, the textual content is direct: you aren’t eligible to use for full withdrawal except you will have remained out of employment repeatedly for at the very least 12 months instantly previous your software. It is a flat bar, not a staged payout. Ladies resigning particularly for marriage are exempted from this ready interval.
Your Actual Liquidity Choice: Partial Withdrawal
Right here is the place the broadly quoted “75% instantly” determine really comes from. It’s not a particular unemployment provision separate from the 12-month bar. It’s merely the final partial withdrawal ceiling underneath Para 46, accessible to you thru the Particular Circumstances class, any time after job loss, no matter how lengthy you will have been unemployed, and even in case you have not but accomplished 12 months of Fund membership. What genuinely requires the 12-month wait is closing your account fully and withdrawing the remaining stability.
So the entire image on job loss: you may entry as much as 75% of your EPF stability nearly instantly by means of a Particular Circumstances partial withdrawal, whereas full account closure requires the 12-month wait.
EPS 2026: Your Pension Guidelines, Verified From The Precise Notification
Only a few subscribers realise that EPF and EPS are ruled by two fully separate schemes with two totally different units of guidelines, and this turns into vital the second you permit a job.
What Stays Unchanged In EPS
- Employer contribution to the Pension Fund stays 8.33% of wages, topic to the notified wage ceiling, remitted inside 15 days of month finish.
- The Central Authorities continues to contribute 1.16% of wages in the direction of the Pension Fund, topic to the relevant ceiling.
- For members who opted for greater pension contribution underneath the sooner scheme, employer contribution stays 9.49% on wages exceeding the ceiling.
- The pension method is unchanged: Month-to-month Member’s Pension equals Pensionable Wages multiplied by Pensionable Service, divided by 70.
- The minimal month-to-month pension stays Rs.1,000, and members want at the very least 10 years of eligible service to qualify for a month-to-month pension in any respect.
- Early pension can nonetheless be drawn from age 50, with a 4% discount for yearly wanting the conventional superannuation age.
EPS Withdrawal Profit: A Genuinely Separate, Longer Wait
If in case you have lower than 10 years of eligible EPS service once you depart a job, you might be entitled to a withdrawal profit, a lump sum calculated as per the Scheme’s Desk IV, as an alternative of a month-to-month pension. However Para 13 is express: you turn out to be eligible to say this withdrawal profit solely after a steady interval of 36 months has elapsed from the date your final contribution grew to become due, or on attaining superannuation, whichever is earlier. That is confirmed instantly within the gazetted textual content, and it’s a genuinely totally different, for much longer wait than the EPF’s 12-month bar.
In case your EPS service has already crossed 10 years, this withdrawal profit just isn’t accessible to you in any respect. You’re solely entitled to a month-to-month pension from age 58 onward, or a Scheme Certificates that preserves your pensionable service for those who transfer to a different EPF-covered employer.
So bear in mind, after shedding a job: your EPF full stability is locked for 12 months, however a piece is accessible earlier by means of partial withdrawal. Your EPS lump sum, for those who qualify for it in any respect, is locked for 36 months. Two totally different clocks, operating at very totally different speeds.
Pension Declare Accountability
Para 17 of the EPS Scheme mirrors the EPF accountability provision. A whole pension declare have to be settled inside 20 days of receipt. Any deficiency have to be communicated to the applicant throughout the identical 20 days. If the Commissioner fails to settle an entire declare inside 20 days with out enough trigger, the profit quantity attracts penal curiosity at 12% every year, recovered from the Commissioner’s personal wage.
EDLI 2026: Your Life Insurance coverage Cowl Simply Received A Extra Exact System
The Workers’ Deposit-Linked Insurance coverage Scheme gives a life insurance coverage type payout to your loved ones for those who die whereas an EPF member, fully funded by your employer, for free of charge to you. Right here is strictly how the payout is calculated underneath the 2026 Scheme, per Para 21.
The Base Profit
Take the typical stability in your EPF account over the previous 12 months, or your complete membership interval if shorter.
- If that common stability is Rs.50,000 or much less, your loved ones receives a flat minimal of Rs.50,000.
- Whether it is greater, the profit is Rs.50,000 plus 40% of the quantity exceeding Rs.50,000, topic to an total cap of Rs.1,00,000.
The Enhanced Profit
For those who had been in steady employment for a full 12 months instantly previous your dying, a second, extra beneficiant method applies: your common month-to-month wages (capped on the notified wage ceiling) multiplied by 35, plus 50% of your common EPF stability, with that mixed wage-linked element itself capped at Rs.1,75,000. No matter this works out to, the Scheme ensures it is going to be not lower than Rs.2,50,000 and no more than Rs.7,00,000. Your loved ones receives whichever is greater between this enhanced determine and the bottom profit above.
One exact element value understanding: the Scheme provides an extra 20% bonus particularly on prime of the bottom profit calculation (Para 21(5), referencing sub-paragraphs (1) and (3) solely). It doesn’t stack on prime of the improved wage-linked method above. So if your loved ones qualifies for the improved profit, that Rs.2,50,000 to Rs.7,00,000 determine is what they obtain; the 20% top-up applies solely when the bottom method is the one in use. Both means, for those who die in service inside 6 months of your final contribution whereas nonetheless in your employer’s rolls, your loved ones nonetheless qualifies for the peace of mind profit, so a brief latest hole in contributions doesn’t disqualify the declare.
Nomination And Claims
You don’t file a separate nomination for EDLI. The nomination you file underneath your EPF account robotically applies to your EDLI payout too, so maintaining that one nomination present covers each advantages. EDLI claims comply with the an identical 20-day settlement customary with 12% penal curiosity for delay, the identical accountability rule that now applies uniformly throughout EPF, EPS, and EDLI.
Simply Received Married? Your Outdated EPF Nomination Is No Longer Legitimate
That is one change that would genuinely create hardship for your loved ones for those who ignore it, and since your EPF nomination now additionally covers your EDLI payout, getting this proper issues much more. Beneath the EPF Scheme 2026, any nomination made earlier than your marriage is robotically handled as invalid the second you marry. You’re required to file a contemporary nomination after marriage.
The rule doesn’t pressure you to appoint your partner particularly. You’ve the flexibleness to appoint any eligible member of the family. However you should file a brand new nomination, as a result of within the unlucky occasion of your dying, an outdated or lacking nomination creates important delays and issues for your loved ones whereas claiming EPF, EPS, and EDLI advantages collectively.
For those who at present haven’t any household, you may nominate any particular person, however you should file a contemporary nomination the second you purchase a household, whether or not by means of marriage or in any other case. Log into the EPFO Unified Member Portal, use the e-Nomination facility, and assessment your nominee particulars as we speak, particularly for those who bought married, had a toddler, or misplaced a member of the family lately.
Hold Your Digital Data Up to date
The 2026 schemes push onerous on digital compliance. Guarantee your Aadhaar, PAN, and checking account are accurately linked and KYC-verified towards your UAN. Employers should now add month-to-month digital returns inside 15 days of month finish, and each declare, whether or not for withdrawal, advance, or switch, is anticipated to be filed electronically by means of the designated portal. Incomplete digital data are some of the frequent causes for declare delays, and getting your KYC correct and present is now squarely your duty as a subscriber.
Inoperative Accounts: Do Not Let Your Cash Sit Idle
In case your EPF accumulation turns into payable, say on retirement after 55, everlasting migration overseas, or the dying of the member, and no withdrawal declare is filed inside 36 months of that quantity changing into due, the account is marked “inoperative.” As soon as that occurs, it stops incomes additional curiosity. So for those who or a member of the family is sitting on a dormant EPF account after leaving India or after a demise within the household, don’t delay the declare.
I attempted my greatest to collate all of the modifications and put it on this picture on your comfort.
What Ought to You Do Now? Your Motion Guidelines
- Log into the EPFO portal and verify whether or not your nomination is present, particularly for those who married, had youngsters, or your loved ones scenario modified lately, since this single nomination now covers each your EPF and EDLI profit.
- Confirm that your Aadhaar, PAN, and checking account are accurately linked and KYC-verified towards your UAN.
- In case your fundamental wage is above Rs.15,000, affirm together with your HR whether or not your employer intends to proceed voluntary EPF contribution in your full wages, or limit it strictly to the statutory ceiling going ahead.
- Cease treating your EPF stability as your major emergency fund. You’ll be able to entry as much as 75% of it pretty rapidly by means of a Particular Circumstances partial withdrawal, however full closure takes 12 months and EPS withdrawal can take as much as 36 months, so construct a separate liquid emergency corpus masking at the very least 6 to 12 months of bills.
- Earlier than making use of for any partial withdrawal, verify which of the three classes, Important Wants, Housing Wants, or Particular Circumstances, your requirement falls underneath, and keep in mind that 25% of your stability will at all times stay untouched.
- If you’re between 10 and fewer than 10 years of EPS service, perceive which observe you might be on, a future month-to-month pension versus a lump sum withdrawal profit, since this materially modifications how you must plan round a job change.
- Resist the temptation to withdraw just because the foundations have turn out to be simpler. Each partial withdrawal reduces the corpus that compounds silently on your retirement.
Backside Line
The EPF Scheme 2026, the EPS Scheme 2026, and the EDLI Scheme 2026 will not be a revolution in how your retirement financial savings work. Your contribution charges, wage ceiling, rate of interest, pension method, and tax advantages stay precisely as they had been. What has genuinely modified is the executive and procedural layer round all three: easier EPF withdrawal classes, a uniform 12-month eligibility interval, a protecting 25% minimal stability rule, an extended look forward to full EPF settlement and a good longer one for EPS withdrawal after job loss, a exactly outlined EDLI payout method, obligatory accountability timelines for EPFO itself throughout all three schemes, and a agency requirement to maintain your nomination up to date because it now does double responsibility for EPF and EDLI collectively.
None of those modifications ought to alarm you for those who perceive them accurately. However they do demand one factor from you as a subscriber: cease being a passive PF holder. Log in, confirm your particulars, perceive which class your future withdrawal wants fall underneath, and let your EPF and EPS corpus do what they had been designed to do, compound quietly on your retirement, whereas your EDLI cowl quietly protects your loved ones within the background.
Incessantly Requested Questions
Has the EPF contribution charge modified underneath the EPF Scheme 2026?
No. The obligatory contribution stays 12% of wages from each worker and employer, calculated on the statutory wage ceiling of Rs.15,000, except each events comply with proceed contributing on greater wages.
Is my PF now restricted to Rs.1,800 per 30 days?
No. Rs.1,800 is simply the obligatory minimal based mostly on the present wage ceiling. Larger contributions can proceed in case your employer agrees, although that is now not computerized and will depend on firm coverage.
How lengthy do I’ve to attend to completely withdraw my EPF after shedding my job?
As per Para 49 of the gazetted EPF Scheme 2026, full closure of your account outdoors retirement, incapacity, or migration requires 12 months of steady non-employment. Nevertheless, you may entry as much as 75% of your stability nearly instantly by means of a partial withdrawal underneath the “Particular Circumstances” class (Para 46), which explicitly covers unemployment.
Is the ready interval the identical for my EPS pension quantity?
No. EPS withdrawal (relevant provided that your EPS service is underneath 10 years) requires 36 months from the date your final contribution was due, or superannuation, whichever is earlier. In case your EPS service has crossed 10 years, you can not withdraw it as a lump sum in any respect, and should wait till age 58 for a month-to-month pension.
Do I want 5 years of service to withdraw for marriage or a home?
No, not anymore. The EPF Scheme 2026 has launched a uniform 12 month minimal membership requirement for many partial withdrawal classes.
Is it obligatory to appoint my partner after marriage?
No, it’s not obligatory to appoint your partner particularly. Nevertheless, it’s obligatory to file a contemporary nomination after marriage, since any nomination made earlier than marriage is robotically handled as invalid. This identical nomination additionally determines who receives your EDLI insurance coverage payout.
How a lot is the EDLI insurance coverage profit for my household?
The bottom profit is Rs.50,000, rising to Rs.50,000 plus 40% of your common stability above that, capped at Rs.1,00,000, plus a 20% bonus on this base determine. For those who had 12 months of steady service earlier than dying, an enhanced method applies as an alternative, assured to be between Rs.2,50,000 and Rs.7,00,000 (the 20% bonus doesn’t apply to this enhanced determine). Your loved ones receives whichever of the 2 calculations is greater.
Has the EPF or EPS curiosity and pension method modified?
No. The EPF rate of interest framework and the EPS pension method (Pensionable Wages multiplied by Pensionable Service, divided by 70) each stay unchanged. Any future revision will occur by means of separate EPFO bulletins, precisely as earlier than.