


Final week, the RBA hiked rates of interest for the fifth time this yr claiming that there have been extra demand pressures within the economic system and that unemployment needed to rise additional to carry demand again into line with provide. They speak in regards to the data they get from their so-called ‘liaison’ teams however don’t disclose additional details about these ‘conferences’. The actual fact is they’re speaking to foyer teams from enterprise and the monetary markets who variously need charge hikes as a result of the rising unemployment suppresses wage calls for and increase financial institution revenue margins. So after all they will inform the RBA something that’s required to elicit the coverage change of their favour. The proof doesn’t assist the declare that there’s extra demand on the coronary heart of the inflationary pressures. Certainly, the proof helps two conclusions: (a) the rising oil costs is an awesome trigger and is invariant to home rate of interest adjustments; and (b) the earnings increase that the rising rates of interest is offering for wealth holders is boosting some expenditure classes (eating places, abroad journey and so forth) throughout the CPI, which can additional push the CPI up as rates of interest rise. It’s superb the established journalists by no means actually demand solutions from the RBA on these factors.
The RBA’s justification
Within the media launch (November 3, 2026) – Assertion by the Financial Coverage Board: Financial Coverage Resolution – the official line was that the inflation was “elevated” and “broadly primarily based”.
They mentioned that:
This partly displays larger gasoline and different commodity costs affected by the battle within the Center East. However home capability pressures are additionally judged to have been somewhat tighter than earlier thought …
Capability pressures seem somewhat tighter than beforehand estimated and there are indications that larger gasoline costs are being handed by way of to costs of different items and providers. Inflation is now anticipated to stay above 3 per cent for the approaching yr and there’s an growing danger that larger inflation expectations will change into embedded.
6 out of 9 members on the MPB voted to extend the coverage goal rate of interest, which circumstances mortgage charges and different longer-term company charges.
Terribly, the RBA concluded saying:
The Board will proceed to do what it considers essential to carry inflation sustainably again to focus on. Accordingly, the Board shall be attentive to the information and the evolving evaluation of the outlook and dangers to information its choices. Financial coverage is effectively positioned to answer developments, and the Board is concentrated on its mandate to ship value stability and full employment.
Do no matter is “obligatory” within the logic of the RBA isn’t in step with its twin legislative accountability to “ship value stability and full employment”.
Listed below are some details:
- The labour drive knowledge for September 2026 exhibits the unemployment charge had risen from 4 per cent to 4.7 per cent and the broad labour underutilisation charge (the sum of the unemployment and underemployment charges) has risen to 11 per cent.
- Since February 2026 when the RBA elevated the speed from 3.6 to three.85 per cent, unemployment has risen by 106.6 thousand individuals or 17.1 per cent.
- The rise in unemployment is overwhelmingly being pushed by employees who need full-time work (96.7 thousand out of 106.6 thousand.
They’re thus intentionally attempting to push extra individuals into unemployment which makes a mockery of the RBA claims that it’s specializing in full employment.
The best way establishments just like the RBA get round this inconsistency is to redefine what they outline as full employment.
The backwards and forwards lately by RBA officers, together with the governor, on what constitutes the Non-Accelerating-Inflation-Fee-of-Unemployment (the dreaded NAIRU) is testomony to this chicanery.
The NAIRU is unobservable and must be estimated.
The econometric estimates are very inaccurate (vast customary errors) and make the purpose estimate ineffective for coverage making.
However the ideologues within the RBA simply ignore these points as a result of making claims in regards to the level estimate as in the event that they know, roughly, what it’s, is extra handy for his or her agenda.
The relevance right here is that if official unemployment charge is above the estimated NAIRU, then the New Keynesians declare that the inflation charge will fall.
Conversely, if official unemployment charge is beneath the estimated NAIRU, then the New Keynesians declare that the inflation charge will rise.
And, importantly, the causality that’s developed within the theoretical fashions is from unemployment charge to inflation through demand (spending) pressures.
So, if the unemployment charge is beneath the NAIRU, these economists conclude that there’s an excessive amount of demand strain within the economic system and value stability requires that coverage tighten complete spending by pushing up the unemployment charge.
The issue although is that the RBA (and economists who peddle this theoretical nonsense) hold revising the NAIRU estimate up once they discover the estimates don’t match the idea.
We noticed that within the inflationary episode submit COVID restrictions.
The Governor of the RBA has admitted many occasions that the RBA makes use of the NAIRU to find out whether or not there’s full employment or not and that at the moment (through the COVID inflation):
… employment is above what we might take into account to be in step with our inflation goal.
And so if firms have market energy and use it to push larger mark-ups to gouge extra income, then the RBA would attempt to cease that inflationary strain by pushing up unemployment.
The unemployment that lastly stopped the revenue push may be very excessive but the RBA would name that full employment although thousands and thousands of employees could be with out work.
For a dialogue of all this please confer with the weblog submit – Mainstream logic ought to conclude the Australian unemployment charge is above the NAIRU not beneath it because the RBA claims (July 24, 2023).
On June 20, 2023, the Governor (then Deputy Governor) of the RBA was in Newcastle for a enterprise occasion and her speech was entitled – Reaching Full Employment
Within the Q&A, the Governor mentioned that to stabilise inflation:
… the unemployment charge should rise … the NAIRU … 4½ in all probability appears, we predict, perhaps within the ballpark.
Within the Speech-proper, she mentioned:
The unemployment charge is predicted to rise to 4½ per cent by late 2024 … Whereas 4½ per cent is larger than the present charge, this final result would nonetheless go away us beneath the place it was pre-pandemic and never far off some estimates of the place the NAIRU would possibly at the moment be. In different phrases, the economic system could be nearer to a sustainable stability level.
On the time, the official unemployment charge was round 3.5 per cent.
A while later, with the unemployment charge nonetheless beneath 4 per cent, the RBA appeared to switch its place and mentioned the NAIRU was round 4.25 per cent.
Now the unemployment charge is 4.7 per cent and the RBA claims it has to rise additional.
They can’t get a straight line on this and that’s as a result of there isn’t any constant line that may be taken.
The NAIRU idea could be very fuzzy and estimates derived from econometric modelling are in every single place, such that the estimates actually can’t be used to information coverage.
What we noticed in 2022 and past was that the unemployment charge in Australia was extremely secure at round 3.6 per cent within the aftermath of the pandemic regardless of the inflation charge rising from beneath 3 per cent to its December 2022 peak above 8 per cent.
The RBA claimed the inflation was as a result of the unemployment charge was beneath the NAIRU estimate (the idea is unobservable after all).
So off they went mountain climbing charges however for the subsequent yr, inflation fell dramatically again to only over 3 per cent as the provision constraints arising from the pandemic eased.
That was all the time going to occur.
However the different factor we noticed was that because the inflation peaked after which quickly declined, the unemployment charge remained secure round 3.5 to three.7 per cent (effectively beneath 4.5 per cent and even 4.25 per cent).
If the RBA’s evaluation of the NAIRU degree was appropriate, then inflation ought to have been accelerating, given the official unemployment charge was beneath the RBA’s NAIRU estimate.
However given the truth of a comparatively secure unemployment charge and falling inflation, then the logical conclusion would have been that the official unemployment charge will need to have been above the NAIRU if that idea was relevant.
The RBA by no means responded to that criticism.
What in regards to the RBA declare that the economic system is overheating in capability phrases?
I’ve already famous that broad labour underutilisation is over 11 per cent now.
That’s, round 11 per cent of the prepared and obtainable labour assets will not be working in a method or one other – both in no way (unemployment) or much less hours than desired (underemployment).
What doable conception of full capability may one have to say that 11 per cent of labour assets not working who need to work constitutes full employment.
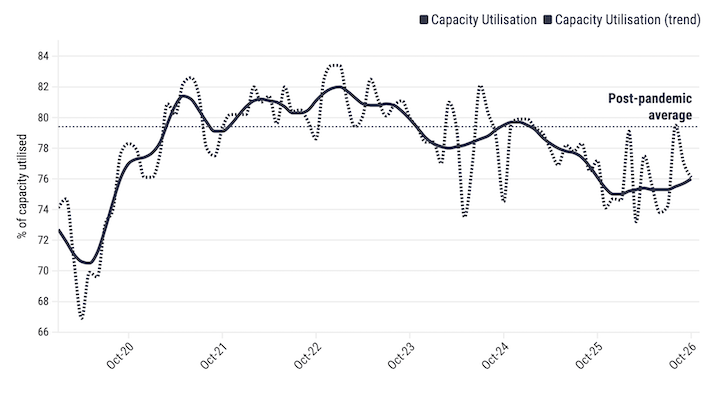
Additional, the Australian Business Group compiles a – Capability utilisation – (as one of many exercise indicators as a part of its Australian Business Index outputs).
The next graph is taken from that sequence (the strong line is the development).
It’s common for companies to keep up some extra capability, which is designed to permit them to fulfill sudden will increase in orders.
Nevertheless, because the graph exhibits over the interval since 2022, capability utilisation throughout the economic system has considerably declined and is now at 76.1 per cent.
That signifies that there 27.2 per cent of the obtainable productive capability isn’t being utilised.
Traditionally that’s numerous extra capability.
The survey additionally notes that:
Price pressures elevated additional because the preliminary influence of upper gasoline costs is now passing alongside provide chains. Weak market circumstances imply business is unable to completely move these prices on, putting mounting strain on margins.
So if there’s broadening of value pressures occurring it’s as a result of the imported gasoline costs stay at elevated ranges.
The query is: How does the worldwide value of oil reply to growing home rates of interest?
The reply: Under no circumstances!
The CPI driving forces
When there are inflationary pressures the smart coverage evaluation is to work out what’s inflicting them.
The one-size-fits-all New Keynesian financial coverage that central banks observe (principally) lately largely ignores that time and treats the inflation as a capability overshoot which requires the demand facet regulate downwards to produce.
Nevertheless, if the present scenario has little to do with extreme spending and all to do with supply-side causes then growing rates of interest is the very last thing {that a} smart coverage regime would ponder.
The availability-side inflation is already hurting low earnings households.
Then the RBA thinks it’s acceptable to inflict extra ache by making their mortgages costlier, whereas on the identical time lining the pockets of the top-end-of-town who’re having fun with booming incomes on account of their monetary property delivering larger curiosity.
And the business financial institution shareholders are laughing as a result of their banks are booming on account of the RBA paying larger curiosity on the surplus reserves held within the system.
The business banks wouldn’t have to do something in any respect and so they nonetheless revenue handsomely on account of these (pointless) transfers from the RBA.
The RBA ought to simply abandon curiosity funds on extra reserves.
However the overwhelming downside is that the rate of interest hikes will not be in a position to goal the main causes of the inflationary pressures.
The next graph exhibits the proportion of the whole change within the CPI accounted for by the main CPI elements.
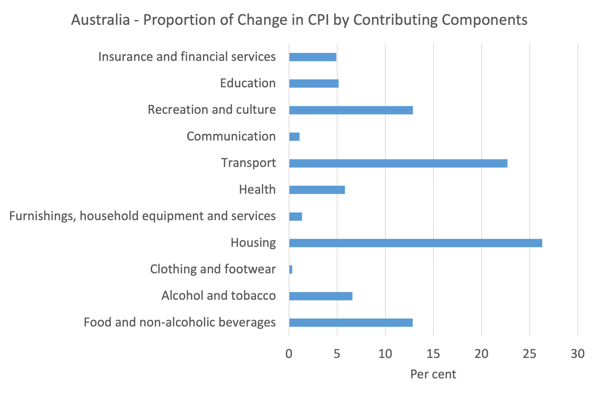
The All teams CPI rose by 4.3 per cent within the 12 months to September 2026.
4 of 11 classes that contribute to that combination final result have been stronger contributors than the others.
- Meals and non-alcoholic drinks contributed 0.558 factors to the whole change (round 12.85 per cent).
- Transport contributed 1.142 factors to the whole change (round 26.30 per cent).
- Housing contributed 0.985 factors to the whole change (round 22.70 per cent).
- Recreation and tradition contributed 0.559 factors to the whole change (round 12.88 per cent).
If we dig deeper we see that:
- Beneath the Transport part, 78.2 per cent of its influence on the CPI in September got here from automotive gasoline.
- Beneath the Housing part, 21 per cent got here from rents and 35.3 per cent got here from Utilities (principally electrical energy). The RBA is pushing the lease CPI part up by driving charges up – landlords dealing with larger mortgage servicing on their funding properties are then passing the prices onto tenants in a decent rental market. The electrical energy costs are rising as a result of the privatised sector is gouging shoppers underneath the regulated value framework.
- Beneath Meals and non-alcoholic drinks part, 49.6 per cent is meals out and take away meals, principally restaurant meals. I surmise {that a} important proportion of that spending is coming from the upper earnings people who’re benefiting from the earnings results of the upper rates of interest on their monetary wealth.
- Beneath the Recreation and tradition part, 45 per cent of the influence is journey – once more I think pushed by larger earnings people.
The purpose is that this knowledge doesn’t point out an economic system that’s working above full capability.
There’s appreciable capital and labour wastage within the system.
Additional, the primary drivers of the inflation are both:
1. Related to the oil concern and invariant to home rate of interest actions; or
2. Boosted by rate of interest hikes (rents, enterprise prices, top-end-of-town earnings results).
As a consequence, the rising rates of interest will:
1. Not cut back inflation.
2. Damage low earnings households and redistribute huge quantities of earnings from the poorer residents who’ve mortgages to the richer residents who maintain monetary property.
3. Ultimately trigger a recession and drive tens of 1000’s extra out of labor, additional compounding the harm.
Conclusion
It’s superb that the mainstream media will not be pushing these points and demanding solutions from the RBA officers.
A lot of the commentary appears to return from journalists who consider themselves as ‘insiders’.
They clarify the RBA logic – that’s repeat the dogma – as a result of they get invited to briefings and so forth and that makes them really feel vital.
That’s sufficient for at present!
(c) Copyright 2026 William Mitchell. All Rights Reserved.