

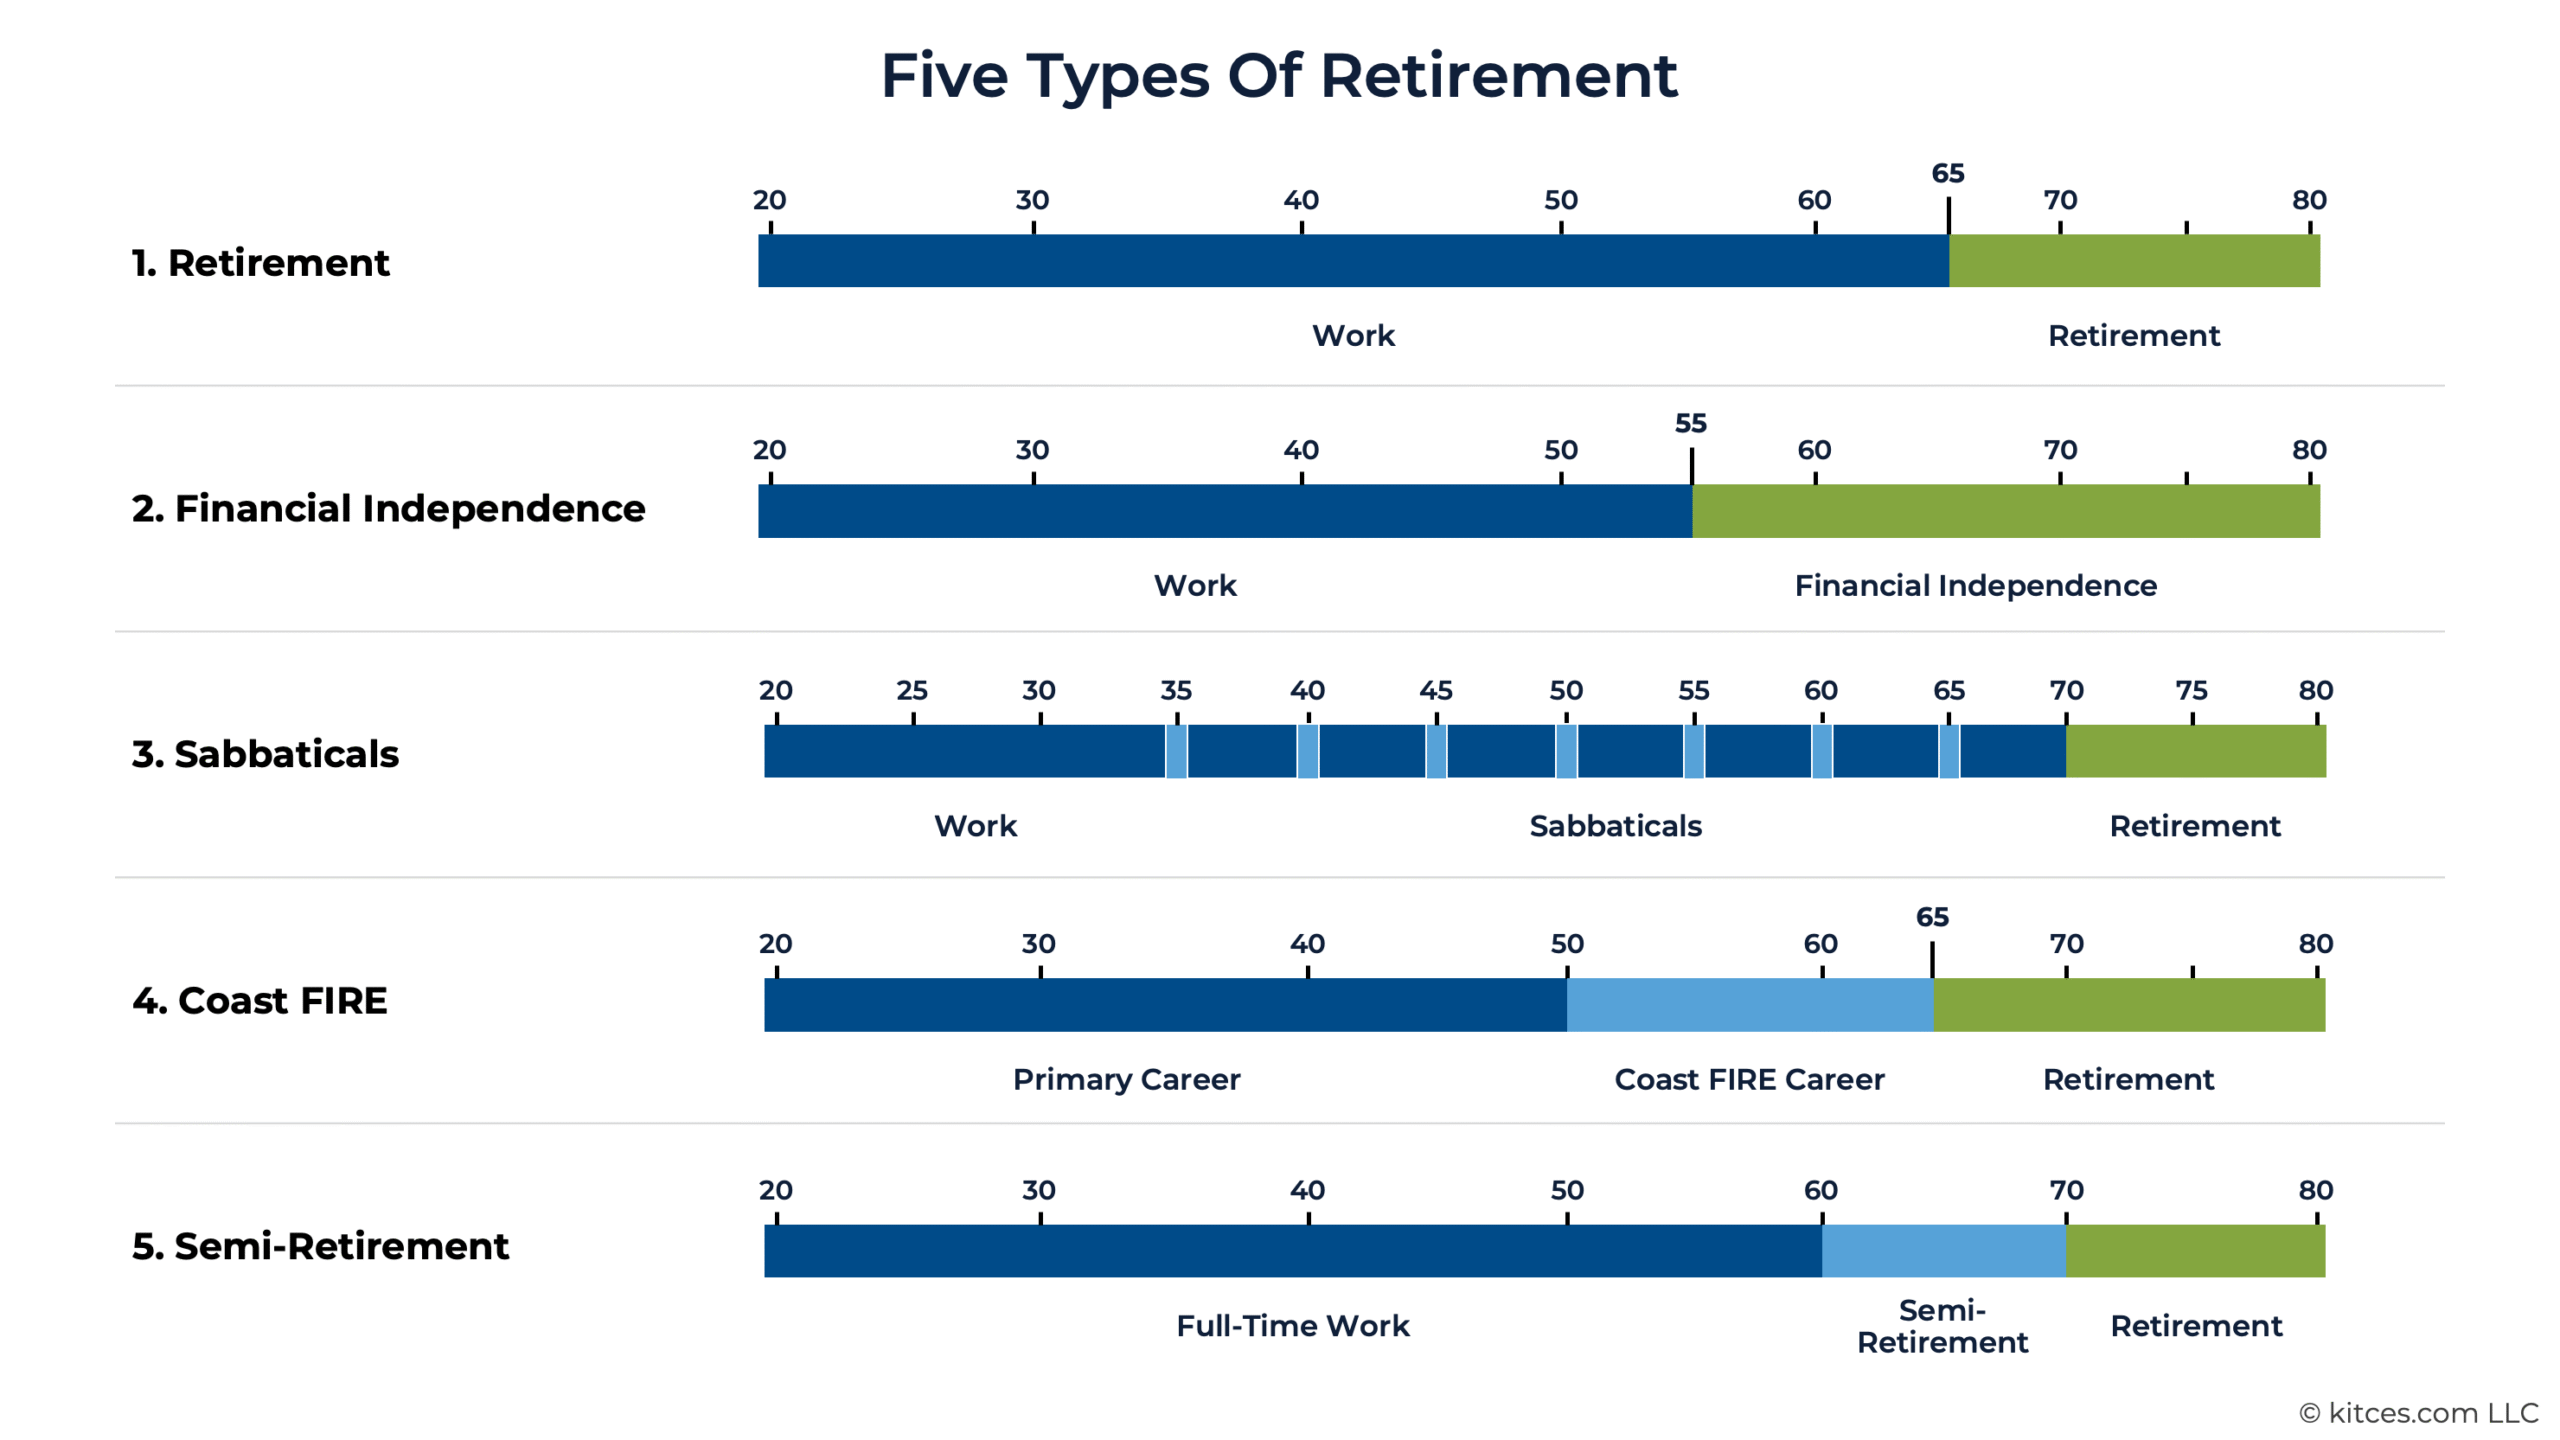

Planning for an pleasurable retirement is a main aim of many monetary planning purchasers. For a lot of, this implies working full-time nicely into their 60s earlier than leaving the workforce totally. Nonetheless, this ‘conventional’ view of retirement won’t be a match for each particular person, as some won’t need to wait till they attain their mid-60s to take vital time away from the office – whereas others would possibly favor to protect the monetary, psychological, and social advantages that may come from working previous ‘conventional’ retirement age.
With this in thoughts, monetary advisors have the chance to create a possible ‘aha’ second for his or her purchasers by introducing them to various retirement paths that would higher match their preferences. Additional, as a result of these methods include their very own respective dangers and planning alternatives, advisors are additionally well-positioned to help purchasers pursuing considered one of these paths on an ongoing foundation.
To begin, purchasers who’ve amassed vital financial savings would possibly be capable of obtain monetary independence, the place paid work is not required to help their way of life bills. Whereas leaving the workforce earlier than ‘conventional’ retirement age comes with direct prices (e.g., buying medical insurance) and dangers (e.g., portfolio sustainability over an prolonged retirement interval), it could additionally current tax planning alternatives (resembling Roth conversion and/or capital positive aspects harvesting throughout lower-income years).
Relatively than depart the workforce utterly, some people would possibly favor to take prolonged breaks through the course of their profession (e.g., for caretaking, or to journey whereas they’re in good well being) whereas planning to return to their current job or an identical place at a distinct firm. These “sabbaticals” provide flexibility (when it comes to their size and frequency) and require fewer belongings than monetary independence, however might necessitate working previous ‘conventional’ retirement age (given the lack to avoid wasting through the sabbatical interval, and the chance that the person will not be capable of discover a commensurate job after they return to the workforce).
For individuals who have not saved sufficient to realize ‘full’ monetary independence however who would possibly need to work in a extra significant and/or much less hectic (however decrease paying job), “Coast FIRE” might be a sexy various path. A person can make the most of this path when their retirement financial savings are projected to develop – with out additional contributions – right into a portfolio giant sufficient to help their anticipated future retirement spending wants. At that time, they ‘solely’ must earn sufficient to cowl their ongoing bills whereas persevering with to work.
Lastly, beneath the semi-retirement path, a person can ‘take a look at’ retirement by decreasing their work hours. On this method, they will see what it is wish to have extra free hours through the week whereas nonetheless tapping into the monetary, social, and psychological advantages that may come from work. A willingness to work at the least part-time previous ‘conventional’ retirement age may also be supportive of a consumer’s long-term plan, because it might enable them to delay Social Safety advantages and mitigate sequence of return threat.
Finally, the important thing level is that monetary advisors are well-positioned to introduce various retirement paths to purchasers who categorical curiosity, and to help them on an ongoing foundation in navigating the ensuing monetary planning challenges and alternatives.
 |
And if you wish to go deeper on this matter, hear instantly from the writer on the Monetary Advisor Technician podcast . |
