


Normal finish of yr evaluation right here. It hasn’t gone nicely, general +0.8 (excluding Russian frozen shares) or +5.4% together with Russian frozen shares. If Russia goes again to regular will likely be up way more as there are plenty of dividends ready to be collected, not included within the beneath.
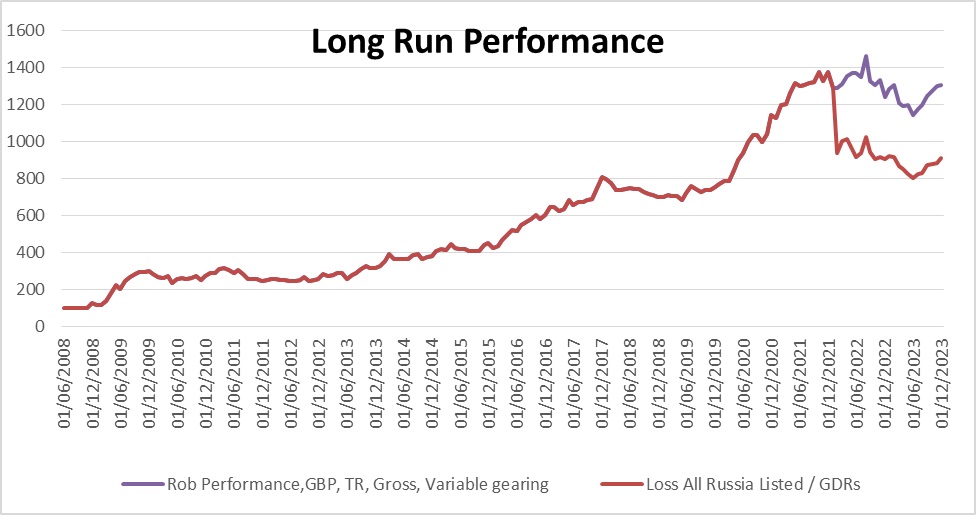


Linking again to final yr I used to be just about unsuitable about every little thing. I used to be closely into pure useful resource shares (c57% weight vs 41% now), not the most effective sector in 2023. A number of the fall in weight is because of me mildly reducing weights as shares didn’t go my manner / although fairly a bit is because of value falls. I had moments of fine judgement – noticed the likelihood for political change in Russia – which very practically happened with the Prigozhin mutiny, received into financials late within the yr. Broadly issues haven’t labored. There’s a delicate optimistic factor to this – if I might be fairly unsuitable on virtually every little thing and nonetheless not lose *a lot* cash it’s not too unhealthy – however it’s removed from perfect given time I put in / potential returns. It’s additionally optimistic I havent gone off the rails after the massive Russian loss final yr – its simple to chase / increase publicity, which is one thing I don’t suppose I’ve executed. There may be an argument round stops – which I don’t use – going to be just a little extra cautious with shares purchased at highs – significantly Hoegh Autos.
Weights are beneath:


Figures are as at twenty third Dec – so just a little approximate – however a usually correct flavour of the place I’m. (some very illiquid shares like ALF costs are incorrect…
Not inclined to vary sector weights an excessive amount of, much less valuable about shares. I’ve additionally been fairly badly hit by manufacturing issues, AAZ had tailing dam points, PTAL – points with the natives, JSE – manufacturing issues. Unsure if that is simply dumb luck or a few of these issues had been within the value – I definitely knew PTAL had issues with ‘group relations’. JSE’s issues with their FPSO (floating manufacturing ship) may have been forseen if I had researched higher – vital to look into age of vessels, didn’t know/suppose to do it on the time nonetheless. These few hundred million market cap shares are rather more weak than I assumed- money piles can evaporate in a short time in the event that they hit points.
Strikes in a few of my bigger weight useful resource co’s that I proceed to carry have been unlucky – CAML -27%, KIST -61%, TGA -53% and THS -32%. While gasoline and coal are down considerably copper is about buying and selling on the value it was at the beginning of 2023, Tharisa’s basket isnt down that a lot. CAML is buying and selling at a PE of 8, 9% yield, THS PE of three.5, 1/4 guide, although marred by a administration who insist on progress capex while buying and selling sub guide. They could get fortunate if costs rise however it’s luck, not judgement. TGA, additionally very, very low cost 7% yield, low single digit PE, once more, irritatingly, investing reasonably than returning capital. These massive falls should not sensible from a capital preservation perspective, one wants a 100% rise to counter a 50% fall. But when we do get a decide up within the economic system / useful resource costs these may simply get again the place they had been. There might also be an argument these can simply rerate with the market, although at current they simply appear to be disliked. PTAL appears to be doing nicely with first rate prospects and a ten%+ yield, with buybacks – all is dependent upon the oil value. Draw back to all that is being commodity producers they solely have a lot management over their destiny – why many traders dislike them.
A inventory which has had manufacturing points is GKP – Gulf Keystone Petroleum it’s points concern the legitimacy of it’s manufacturing contract / pipeline entry. It’s the one one I’ve added to reasonably than lowered over the yr – averaging down. The entire Kurdish oil business has a query mark (relying on who you take heed to) concerning the legitimacy of it’s contracts. However, I can’t consider an instance the place an entire business was seized / nationalised / expropriated. Everybody – Kurdish govt / Iraqi govt and oil corporations have mentioned that contracts will likely be revered / discussions are ongoing. It’s removed from threat free – I believe greatest threat is that one firm is punished / seized to encourage a deal to be made by the others. Large upside on this – it’s a really massive discipline with very low extraction value – though the oil isnt the very best quality, if made reliable relying on the precise deal. They’re greater than masking their prices so for my part value a glance in case you have threat tolerance for a considerable loss. If this works it’s a 3x-5x or extra, however it’s one the place the end result is basically exterior administration’s management – for causes aside from commodity costs.
One among my finest performing investments is JEMA – previously JP Morgan Russia. It’s an odd one – buying and selling at 48p ‘official’ NAV with a share value of c £1.30 and a MOEX NAV at about £5-£6. JPM have marked all of the Russian holdings to about 0. I’m up about 55% and have trimmed the place – promoting a couple of third already. There may be rising speak of seizing Russian property to pay for the subsequent spherical of Ukraine funding. Not totally positive what to do on it – upside continues to be big however I have already got 30% of the portfolio worth in Russian, sanctioned shares. I dont really want an additional weighting to turbo charged Russian publicity with the identical dangers – going to have to chop this to handle threat however considerably reluctant to, given the upside… I imagine plenty of the frozen Russian property are held by Clearstream in Belgium , however uncertain to what diploma Belgium actually makes the decisons on that one. Russia seems to have ‘received’ not less than to a point militarily – they’re making gradual progress, nonetheless they’re eager to have ‘peace’ / stop hearth talks. I believe it is because their wins should not sustainable, human losses/ monetary value is just too heavy to be sustained. Ukraine lacks the manpower and probably arms for an ongoing attritional combat however Russia lacks the motivation. My view is Russia cracks first and we see extra mutinies in 2024.
Uranium commerce has gone nicely – KAP/URNM up 43/53%. Have switched just a little bit of cash out of URNM into YCA – perhaps the metallic will proceed to outperform the miners for fairly some time. I’m considerably skeptical of YCA / SPUT shopping for Uranium to tighten the market – as an industrial commodity – it solely actually has worth if it’s used – so implied value of spot / spot -% means sooner or later it is going to be used, and if it is going to be used then tightening of the market in all probability shouldn’t occur. Not how persons are taking a look at it in the intervening time although.
Financials have executed nicely – regardless of me including Nov/Oct so that they haven’t had an excessive amount of time to contribute. October costs for many funding trusts / asset managers and so forth. (largely UK based mostly) regarded very depressed, 10% yields 40% and so forth low cost to guide values. Startling how rapidly issues have bounced. Not totally positive finest solution to deal with these long run, they may very well be a pleasant stable revenue play, purchased at excessive yields or if I discover one thing higher then time to promote . I wrote about these lately in this publish. I’m a bit involved about them as a long run maintain – the upside could be very a lot restricted, although excessive likelihood. I choose to be within the ‘actual’ inflation linked economic system, arduous property reasonably than the monetary economic system.
A monetary I purchased after that publish is PHNX – Phoenix Group – it is a massive closed life insurance coverage supervisor it’s buying and selling at an honest 9% yield. The dividend is £500m for an organization which is producing £1.3-1.4bn pa in money and which has £3.9bn solvency 2 surpulus – it needs to be sustainable. As ever with hyper large-cap insurers as an newbie you might be by no means fairly positive what the regulator will provide you with which can wreck your day. You’re additionally betting in opposition to the brand new weight reduction medicine growing lifespan – although of late expectancy has been falling unexpectedly. Not one I’ll maintain for too lengthy – I’m excited about a yr or two, however I feel it’s under-priced. In search of alpha write up right here (not by me).
Bought out of AA4 and DNA2 – first rate income on each (+100% on some tranches, held since 2020) however I feel there are higher locations for funds now. I could also be lacking out on a little bit of upside if the A380 finds extra of a market – maybe if one other airline begins utilizing it, although I doubt it’s logistically easy. There are actually higher alternatives on the market, although AA4 could have extra upside however at greater threat.
Fondul Proprietea is now a tiny weight – after tender gives / returns of capital. Its just a little unhappy to be saying goodbye. I got here up with this concept again in 2012 and have benefited from a closing of a 50% low cost and progress in underlying investments – it’s actually the perfect funding. It has had a 962% rise since inception (2011) and I’ve owned it since 2012 – although once in a while have needed to drop it as a result of dealer points. Time to promote this – as there isn’t an excessive amount of upside left now. Actually struggling to search out issues with this stage of high quality / cheapness / ongoing compounding alternative.
Having mentioned this, one which can match the invoice is Beximco (BXP) it is a Bangladeshi Pharma, buying and selling at a PE of 5, doubled income since 2018 (in BDT, however even in USD it has grown impressively) and it has considerably elevated earnings (my 2019 write up right here). It’s presently buying and selling at half the place it’s in Bangladesh however there is no such thing as a arbitrage alternative. Frustratingly, I needed to minimize my weight as my dealer wouldn’t enable it in a tax environment friendly ISA account, this didn’t harm me as the worth fell. My dealer has modified their thoughts so now I can put it again and lift the burden. Brokers right here appear to depend on massive screening corporations and drop / add corporations to the listing of what’s eligible – not relying on the principles however how they really feel on the time.
Walker Cripps could be very a lot the worst sort of worth funding – the one the place nothing occurs. Walker Cripps is reasonable on an AUM foundation however hasn’t moved since I purchased it in 2015. Presumably I’ve given this too lengthy, then once more there’s consolidation within the sector and this could be good for it… The FOMO of understanding the day I promote it a proposal will likely be made at 3x the present value retains me holding, my not insubstantial endurance is operating out.
I nonetheless have some leverage – however that’s low cost mortgage / unsecured debt at 3/4% charges. Its a comparatively small quantity vs portfolio / portfolio + property property – about 20%/11%. In impact, as in prior years leverage is getting used to purchase gold / held on deposit at a better fee…
When it comes to life – no change, nonetheless residing within the UK, reasonably unhappily employed (low/mid stage knowledge analyst) three days every week, doing investments / little little bit of property the remainder of the time. Actually wanting ahead to life beginning correctly when I’m not employed / ideally leaving the nation. Was considerably distracted by a pointless court docket case throughout the first half of the yr and didn’t see a lot alternative so didn’t do a lot. Second half has been higher, significantly after October. I nonetheless suppose a giant transfer in lots of the useful resource co’s I maintain is probably going, so actually dont need to transfer earlier than that occurs – as a rustic transfer will entail pulling fairly a bit out of shares. PE’s of below 5 should not doubtless for my part to be sustained, although there’s a threat a sustained recession / melancholy shrinks earnings and share costs additional… I’d wish to get extra copper / tin / silver publicity however haven’t but discovered any shares I like, and ETF’s should not with out their issues…
Assume this yr has suffered from me largely being in first rate shares by way of yield / valuation however not shares the market cares about / likes which is why they’re low cost. I may go extra mainstream however I’d reasonably keep the place I’m and await the market come to me reasonably than chase… Not wedded to explicit shares however the weighting to the useful resource sector wants to stay – they’ve been below invested in they’re low cost and retro – very a lot suppose they may have their day within the solar. Plan to modify again from among the funds to sources as soon as the financials get again to nearer to what I anticipate is their honest worth.
Shares I plan to have a look at subsequent are tobacco – BATS/IMB in all probability – if I can get comfy with authorized dangers / debt ranges, they’re yielding nicely and should not extremely valued. Once I can purchase mainstream shares at single digit PE/ EV/EBITDA there is no such thing as a must go too far into unique territory. Not the preferred – they do kill their prospects in spite of everything, however vapes, hashish and so forth could present a possibility to really purchase progress at a low value – significantly if regulation cuts out dodgy Chinese language imports. Nonetheless need to rebuy Royal Mail on the proper value. Long term I need extra Latin American / Asian listed shares. China seems low cost however I’m very cautious of avoiding a repeat of the Russian state of affairs.
Better of luck for 2024 – as ever feedback/views appreciated.