
Opinions expressed in reader tales don’t essentially signify the views of freefincal or its editors. We should respect a number of options to the cash administration puzzle and empathise with numerous views. Articles are usually not checked for grammar until it’s essential to convey the proper which means and protect the tone and feelings of the writers.
If you need to contribute to the DIY group on this method, ship your audits to freefincal AT Gmail dot com. You possibly can publish them anonymously if you want.
Please observe: We welcome articles like this from younger earners who’ve simply began investing. See, for instance, this piece by a 29-year-old: How I monitor monetary targets with out worrying about returns. We even have a “mutual fund success tales” collection. See, for instance, how mutual funds helped me obtain monetary independence. Now, over to the reader.
After 4.5 years, I’m writing this text to share an replace and the teachings learnt. A fast abstract earlier than I begin. As I discussed in my earlier article, I began investing late, in my late 30s, which is a standard mistake. However I’m able to catch up due to my 2 onsite tenures. My first onsite helped me to personal a house, with a small residence mortgage. My second onsite helped me to shut my residence mortgage and begin constructing my portfolio. Throughout my second onsite tenure, I landed in freefincal and began vigorous investing. Now I’m in my mid-40s, returned to India 3 years in the past, and proceed working on the similar Company from India.
I purchased robo robo-advisory instrument in 2021, which modified my investing thought course of and gave me peace of thoughts. It directed me what to speculate, when to speculate and the place (asset class) to speculate for every purpose which I did religiously for previous 4.5 years and now I really feel I’m peaceable.
🔥Safe your future with our Robo-advisory instrument trusted by over 3,500 buyers and advisors. From easy retirement planning to funding your kids’s greatest goals, flip your monetary targets into actuality. 🔥
I’ve 2 targets. 1 is my baby’s increased training, which is due within the subsequent 4 years. I nearly reached the quantity required for that purpose lately. 2nd purpose is my monetary freedom; if every thing goes properly, I ought to be capable of obtain monetary freedom across the finish of 2030. I don’t need to name it as retirement plan, as a result of I don’t need to retire as quickly as I obtain it. I’ll proceed to work so long as I’m able to do or I’m allowed to do by the Company, atleast until early 50s.
At current I’m persevering with to speculate for my monetary freedom as suggested by robo advisory instrument. Infact I’m investing greater than the quantity recommended by the instrument, as I’m able to do this.
I don’t monitor each expense, I monitor solely investments. Virtually 65% of my month-to-month earnings goes to funding and remaining 35% for month-to-month bills. I allocate a blanket quantity (round 35% of my wage) for all month-to-month bills and so long as my bills are inside that, I don’t monitor every expense. When there may be spare quantity, I preserve that as money individually reserved for our household tour or any medical associated bills (like scanning, tablets and so on). Each month, cash will get deducted for SIPs, which is automated, in order that I don’t must spend a lot time in administration of it. I monitor and evaluate my portfolio as soon as in 1 / 4. So I don’t preserve seeing issues every day or spending extra time on it.
I didn’t change my life type considerably after getting back from onsite. I lead similar way of life like earlier at similar time I didn’t miss to improve for few issues as properly (like AC for my bed room, OTT subscriptions spending, household tour as soon as in 1 / 4 and so on) . I nonetheless favor public transit throughout my household journeys besides in sure areas the place transportation is in restricted frequency. Being in Tier 2 Metropolis, I didn’t have a necessity for a automotive and therefore I don’t personal a automotive which lower down my month-to-month bills considerably. Infact I’ve a 2 wheeler which is used for workplace commutation and all different private commutation. For household commutation, if required I don’t miss to make use of cabs throughout the Metropolis.
My child’s increased training goal-related portfolio:
Mounted earnings – 72% (PPF, NSC, FDs, RBI Bonds – all maturing throughout the time of the upper training) XIRR ranges from 7.1 to eight% based mostly on the product
Fairness – 0%
Gold mutual fund – 28% – XIRR : 30.25% I began investing important quantity monthly in gold solely from 2023 co-incidentally and , it has helped me lots to realize the purpose. I perceive it’s extremely unstable like fairness and may be at this similar worth for subsequent a number of years, because it has raised considerably already. I took this threat knowingly.
My Retirement portfolio:
Mounted earnings: 32% Debt mutual funds, EPF, NSC. XIRR: 7.1 to eight.5% based mostly on the product
Fairness mutual funds : 48% XIRR: 17.18% I’ve a mixture of Index funds and Energetic fairness funds. My oldest fairness fund was began in 2018, and nonetheless persevering with it. It has a XIRR of twenty-two.23%. That’s energy of fairness when we’ve some luck as properly. After figuring out extra about index funds, my desire is index funds.
Direct Fairness: 20% XIRR: 12.72% (This excludes dividends. I get dividends from the shares near rental earnings, which I reinvest in hybrid mutual funds). I began progressively in Dec 2021. As per the Zerodha report, my portfolio has outperformed the Nifty 50 by 2.24% for the reason that date I began direct fairness investing. Lately, I purchased IT shares, which went down considerably in previous 12 months. In any other case, I left the opposite shares in my portfolio largely unchanged.
Fairness allocation seems to be bit increased than the usual advisable allocation. This yr, I lowered my month-to-month fairness investments and elevated my fixed-income investments. At current my retirement corpus is 25x of my present month-to-month bills. So nonetheless lengthy solution to go, contemplating my present age.
Classes Learnt:
Begin investing early early early. Put money into a disciplined method with out worrying about returns. Magic will occur because the years cross by.
Don’t make investments 100% in fairness. Observe asset allocation at all times
As you make investments on your future, make investments on your well being additionally. Well being is actual wealth. We have to change our way of life (primarily consuming habits) to guide a wholesome life, which I learnt from my very own expertise lately.
Learn extra tales: reader story archive.
We’re on Google Information
Use this button so as to add freefincal.com as a most well-liked private finance supply on Google Information.
You too can comply with freefincal on Google Information.
Discover 1,400+ movies on YouTube!
Subscribe to get posts through e-mail!
Be part of 32,000+ readers and get free cash administration options delivered to your inbox! (Hyperlink takes you to our e-mail sign-up type)
Be part of our WhatsApp Channel
Discover our merchandise
🔥Be part of our group of 9000+ customers! 🔥
- Use our Robo-advisory Software to create a whole monetary plan! Greater than 3,500 buyers and advisors use this! Use the low cost code robo25 for 20% off. Plan your retirement (early, regular, earlier than, and after), plus non-recurring monetary targets (comparable to baby training) and recurring monetary targets (comparable to holidays and equipment purchases). The instrument helps anybody aged 18 to 80 plan for retirement, plus six non-recurring and 4 recurring monetary targets, with an in depth money circulation abstract.
- Our Flagship Course! Study to handle your portfolio like a professional to realize your targets no matter market circumstances! Greater than 3,500 buyers and advisors are a part of our unique group! Get readability on the right way to plan on your targets and obtain the required corpus regardless of the market circumstances! Watch the primary lecture without spending a dime! One-time fee! No recurring charges! Lifelong entry to movies! Cut back worry, uncertainty and doubt whereas investing! Discover ways to plan on your targets earlier than and after retirement with confidence.
- Be part of the freefincal investor circle! An unique area for buyers, advisors, fintech workers and college students to entry monetary planning and insurance coverage instruments, mutual fund and inventory evaluation instruments, coding methods and Excel macros for information extraction. 750+ members at the moment are a part of our investor circle.
- Enhance your earnings by getting folks to pay on your abilities! Greater than 900 salaried workers, entrepreneurs and monetary advisors are a part of our unique group! Discover ways to get folks to pay on your abilities! Whether or not you’re a skilled or small enterprise proprietor in search of extra shoppers by on-line visibility, or a salaried particular person on the lookout for aspect or passive earnings, we are going to present you the right way to do it by showcasing your abilities and constructing a group that trusts and pays you. (Watch the first lecture without spending a dime). One-time fee! No recurring charges! Lifelong entry to movies!
- We additionally publish month-to-month screeners for
Our Podcast: Let’s Get Wealthy With Pattu
On Spotify: Let’s Get RICH With PATTU! Each single Indian CAN develop their wealth! On Audible: Hearken to the Let’s Get Wealthy with Pattu Podcast
You too can watch podcast episodes on the OfSpin Media Mates YouTube Channel 
Hearken to the Let’s Get Wealthy With Pattu podcast on YouTube.
Now watch Let’s Get Wealthy With Pattu தமிழில் (in Tamil)!
About The Creator
Dr M Pattabiraman giving a lecture
- Dr M. Pattabiraman (PhD) is the founder, managing editor and first writer of freefincal. He’s an affiliate professor on the Indian Institute of Expertise, Madras.
- He has over 14 years of expertise publishing information evaluation, analysis and monetary product growth. He has over 28 years of educating and analysis expertise. He’s additionally a public speaker and keynote presenter.
- He’s a patron and co-founder of “Charge-only India,” an organisation selling unbiased, commission-free, AUM-independent funding recommendation.
- Join with him through @pattufreefincal on X LinkedIn YouTube
- Pattabiraman has co-authored three print books.
(1) You may be wealthy too with goal-based investing (Revealed by CNBC TV18) for DIY buyers.
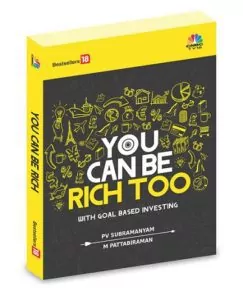
This guide helps you ask the proper questions and discover the proper solutions. It additionally consists of 9 on-line calculators to create customized options.
(2) Gamechanger: Neglect Startups, Be part of Company & Nonetheless Stay the Wealthy Life You Need.
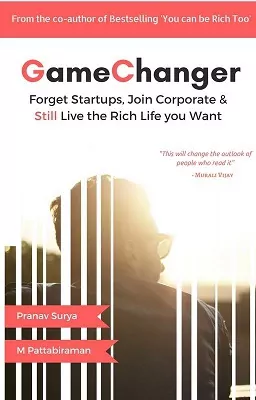
This guide helps younger earners get the fundamentals proper from the beginning! It would additionally allow you to journey to unique locations at a low value! (3) Chinchu Will get a Superpower! for youths.
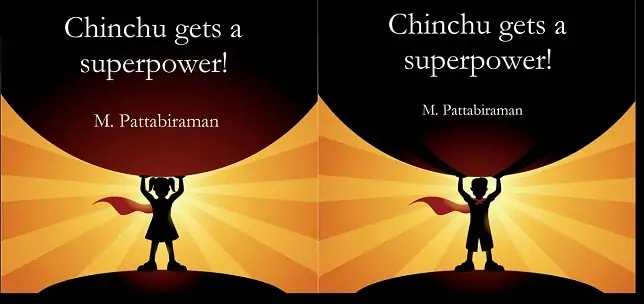
Each the boy and woman variations of “Chinchu Will get a Superpower”.
Most investor issues stem from a scarcity of poor decision-making. We made unhealthy choices and cash errors after we began incomes, and we spent years undoing them. Why ought to our kids undergo the identical ache? What is that this guide about? As dad and mom, what if we needed to groom one means in our kids that issues not just for cash administration and investing however for each facet of life? My reply: Sound decision-making. So, on this guide, we meet Chinchu, who’s about to show 10. The story follows what he needs for his birthday and the way his dad and mom plan it, whereas additionally educating him key concepts about decision-making and cash administration. What readers say!
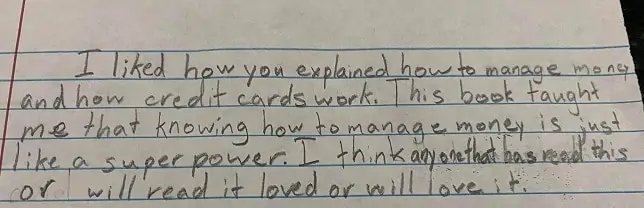
Suggestions from a younger reader after studying Chinchu Will get a Superpower!
Should-read guide even for adults! That is one thing that each mum or dad ought to train their children proper from a younger age. The significance of cash administration and decision-making based mostly on their needs and desires. Very properly written in easy phrases. – Arun.
About freefincal & its content material coverage
Freefincal is a Information Media organisation devoted to offering unique evaluation, reviews, opinions and insights on mutual funds, shares, investing, retirement and private finance developments. We accomplish that with out battle of curiosity and bias. Observe us on Google Information. Freefincal serves greater than three million readers a yr (5 million web page views) with articles based mostly solely on factual info and detailed evaluation by its authors. All statements made will likely be verified with credible and educated sources earlier than publication. Freefincal doesn’t publish paid articles, promotions, PR, satire or opinions with out information. All opinions will likely be inferences backed by verifiable, reproducible proof/information. Contact Data: To get in contact, please use our contact type. (Sponsored posts or paid collaborations won’t be entertained.)
Our publications
- Your Final Information to Journey. That is an in-depth exploration of trip planning, together with the right way to discover reasonably priced flights, finances lodging, and sensible journey suggestions. It additionally examines the advantages of travelling slowly, each financially and psychologically, with hyperlinks to related internet pages and steering at each step. Get the PDF for Rs 300 (on the spot obtain)