


The Australian authorities’s choice to scrap the 50% capital beneficial properties low cost for all investments within the Might funds got here as a giant shock for crypto homeowners. The brand new scheme successfully doubles the taxable part of a achieve, minus a small low cost for inflation.
However there are authorized methods to reduce the quantity of CGT you’ll should pay — in case you begin prepping now.
Some Aussie crypto holders are taking drastic measures — like Finder founder and crypto king Fred Schebesta who’s relocating to Singapore which provides 0% CGT, stating the tax modifications had been a “killer blow.”
However there are much less dramatic strategies to scale back your CGT payments together with establishing a self managed tremendous fund (SMSF), an organization to commerce crypto on the firm tax price, or to simply cross your fingers and hope the opposition will reverse the modifications after the subsequent election.
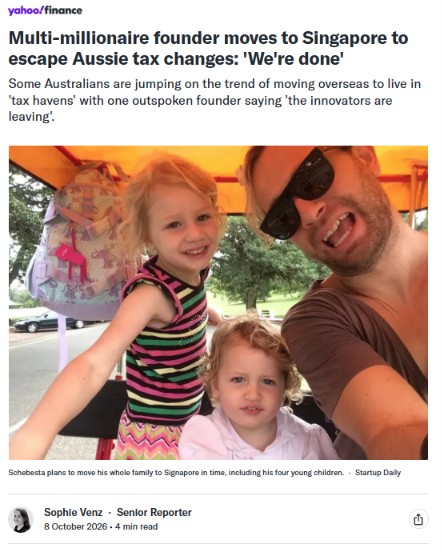
Supply: YahooFinance
What’s altering with CGT on July 1, 2027?
Since 1999, Aussie asset homeowners have solely paid tax on half of their capital achieve. From July 1, 2027 they’ll pay their full revenue tax price — which implies 30% CGT in case your revenue and beneficial properties are between A$45,000 and $135,000, 37% for the portion between $135,000 and $190,000 and 47% above that. (All figures on this story are in Aussie {dollars})
Including insult to harm, low-income earners who aren’t on welfare like college students and retirees pays a minimal 30% CGT price irrespective of how little the achieve.
The one low cost now accessible accounts for the impact of inflation in your value foundation. So in case you purchase a home for $1 million in 2027 and promote it for $1.5 million after 10 years, with inflation at 3%, you received’t should pay tax on the $344,000 or so attributed to inflation.
“The problem for cryptocurrency is that the CGT modifications, indexation actually helps slower rising property not quick ones,” explains Andrea Yuen, Swyftx CEO.
So in case you purchased Bitcoin for $10,000 and promote it ten years later for $100,000, the inflation low cost is simply round $3,439. Underneath the previous system you’d pay tax on $45,000 of beneficial properties. Underneath the brand new system you’ll pay tax on $86,561 of beneficial properties.
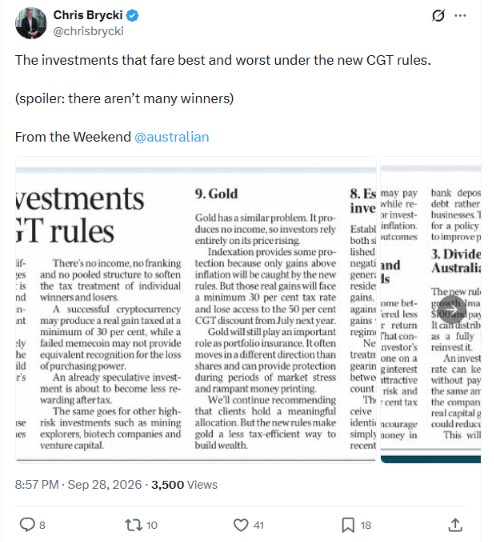
Stockspot analyst Chris Bryki in contrast how ten completely different asset lessons would fare underneath the brand new guidelines.
“Crypto sits on the backside as a result of virtually its complete return comes from capital progress,” he wrote in The Australian newspaper.
“An already speculative funding is about to turn into much less rewarding after tax.”
Listed below are a couple of completely different methods to assist crypto holders cope with the modifications, starting from little to no effort, to restructuring your complete life.
1. Hope for an enormous bull run earlier than July
Any achieve you’ve made earlier than July 1 2027 shall be taxed underneath the prevailing 50% low cost scheme. So your finest guess is to hope a raging bull market pushes the worth of your portfolio as excessive as attainable earlier than that date.
It is best to faithfully report the worth of each crypto asset you’ve gotten that day, as any achieve from that worth shall be taxed on the larger price.
Ben Simpson, founding father of crypto advisory service Collective Shift, says Bitcoin’s efficiency since mid-year in a difficult macro setting bodes properly for additional beneficial properties earlier than July.
However Simpson (who factors out he’s not a monetary advisor) provides, “I most likely wouldn’t be betting the farm on the truth that we’re gonna have an enormous bull run”
“I believe the halving in Might 2028 is the place we’ll see a lot of the returns. So I don’t suppose it’s going to work in buyers’ favor.”
Yuen notes that costs aren’t inside your management. “A method isn’t a technique in case you’re simply form of hoping,” she says.
2. Vote for a celebration that can reverse the CGT modifications
Each the official opposition The Coalition, and the rebel opposition One Nation, have promised to reverse the modifications. Crypto voters who really feel strongly sufficient about this single concern, may vote for a change in authorities.
Nonetheless, the ruling ALP holds 94 out of 150 seats within the Home of Representatives and shall be troublesome to dislodge from workplace. If the federal government does change — and the laws can move the Senate in time — it’s technically attainable the modifications might be reversed earlier than anybody has to file taxes from July 1 2028.
But it surely’s most likely extra probably that any change to the system would happen after that date. Adrian Forza, director of Crypto Tax Australia, says this might make calculating beneficial properties very troublesome.
“It could be a nightmare to do three calculations, however long term, it’ll be higher for the general public.”
3. Shift your crypto right into a self-managed superannuation fund
Australian retirement funds are referred to as superannuation funds, and as soon as you’re over 60 you may entry your investments tax-free — at the same time as they continue to grow.
Sadly not one of the retail tremendous funds permit purchasers to put money into crypto, so if you wish to defend your crypto beneficial properties utilizing this methodology, you’d should arrange an SMSF. A couple of third of Simpson’s excessive internet price purchasers put money into crypto through SMSFs.
“Shopping for Bitcoin and accumulating it there’s a tremendous stable concept,” he says, though he cautions towards including many altcoins. “You’re risking your retirement, which is an extremely long-term maintain, on short-term altcoins,” he says.
Australian tremendous fund AMP has invested in Bitcoin — however doesn’t permit its purchasers to take action.
The large downside with SMSFs — explains the 27-year-old founder — is that youthful crypto buyers can’t entry the cash for many years.
“You possibly can’t contact it till you’re in retirement, proper? So you may’t actually make the most of any of these beneficial properties till later in life.”
Realistically then, it’s a technique extra suited to wealthier buyers aged over 50, who’ve a shorter interval to attend.
Associated: Older buyers are risking every thing for a crypto-funded retirement
The federal government has additionally made operating an SMSF a ache within the bottom, with plenty of compliance paperwork and audits, in addition to a bunch of unavoidable charges that make it prohibitive for smaller balances.
Annual prices usually vary between $2,000 and $4,000, though on-line suppliers like Stake can scale back complete annual prices to round $1,330, so long as you solely purchase Bitcoin or Ether ETFs.
You additionally should promote any crypto and pay tax on it earlier than you may rebuy it together with your SMSF, and there are annual contribution limits to think about, though Forza says you need to have the ability to get virtually $400,000 in there with a little bit of creativity.
Preserve an eye fixed out in December for an in depth report on how one can arrange a crypto SMSF.
4. Borrow towards your Bitcoin to keep away from a CGT occasion
A method some billionaires make use of to keep away from paying tax is by borrowing towards their property, as repaying the mortgage typically works out cheaper than paying tax on a sale.
Bitcoiners can now entry a variety of lenders, together with BlockEarner, Veild and Swyftx, that allow you to make use of an identical technique by borrowing towards your BTC as collateral.
“We prefer to carry that technique to the plenty, not simply to billionaires,” laughs Yuen.
However it may be dangerous in case you don’t have a billionaire’s deep pockets. Debtors face excessive rates of interest, comparatively quick mortgage durations (usually 12 months), and danger shedding their Bitcoin if the market strikes towards them. You possibly can’t borrow towards the complete worth both — Swyftx has a loan-to-value ratio round 40%.
”In case your collateral drops beneath a specific amount, there shall be a margin name,” she says. “I’d say it’s a guess on a worth going up. I believe it’s important to have a view that crypto will go up — or not less than not go down so that you just get margin-called… In any other case, a crypto-backed mortgage wouldn’t make sense for you.”
Simpson doesn’t advocate this technique because of the dangers, however says it might probably repay for some folks. For instance in case you borrow at 10% curiosity, and Bitcoin compounds by 33% a 12 months (because it has carried out previously) you’d find yourself a lot better off than paying CGT.
However he warns it’s a leveraged guess that’s finest suited to stylish buyers.
“I wouldn’t advocate it for somebody that’s extremely uncovered to crypto and doesn’t have the capital behind them as a result of it’s a dangerous factor in case you don’t know what you’re doing.”
Bitcoin is down 28% over the previous 12 months, so anybody borrowing a 12 months in the past would have confronted margin calls and attainable liquidation in addition to curiosity prices.
Borrowing towards Bitcoin for a home deposit has turn into a extra widespread technique. (BlockEarner)
Forza cautions that borrowing crypto may also be a CGT occasion in some circumstances, comparable to borrowing in DeFi. For those who deposit ETH to Aave, it will get mechanically swapped to WETH which is a taxable occasion, and once you withdraw the ETH it’s one other taxable occasion.
Borrowing from centralized lenders like BlockEarner or Swyftx is at present a gray space, and the ATO has not clarified if it’s a taxable occasion.
”For those who’re speaking about [borrowing] ten grand tremendous. However in case you’ve obtained three to 5 Bitcoin, I wouldn’t danger it as a result of if it goes towards you then you definately’re going to be paying tax.”
”Vield is the one one in Australia that’s obtained a non-public ruling that claims their product just isn’t a taxable occasion. Nobody else has obtained one.”
Swftxy confirmed it has not obtained a non-public ruling and stated purchasers ought to search tax recommendation, whereas BlockEarner didn’t reply to a request for remark.
Partly two of our Aussie CGT particular, coming later this week, we’ll carry you the ultimate 4 methods to reduce your crypto tax payments, together with establishing an organization or leaving the nation fully.
Additionally learn: Child boomers price $79T are lastly getting on board with Bitcoin