

Firm Overview
Laser Energy & Infra Restricted is an built-in producer of energy cables, conductors and different specialised merchandise for India’s energy transmission and distribution business, with an working historical past of over three a long time. In 2015 it forward-integrated into the engineering, procurement and building (“EPC”) phase, delivering turnkey rural and concrete electrification, distribution infrastructure and substation tasks. It operates two segments – Manufacturing (energy and management cables, speciality merchandise and conductors) and EPC.
Laser Energy is without doubt one of the main gamers by manufacturing capability for energy cables and conductors in East India, operating three West Bengal services with a mixed put in capability of 85,448 MT as of March 31, 2026, and is an RDSO-accredited registered provider to Indian Railways. As of the identical date, it carried an Order Guide of ₹3,243.4 crore, operations spanning 26 states, 4 union territories and 10 international locations, over 43 accomplished and 34 ongoing EPC tasks, and 699 everlasting staff.
Objects of the provide
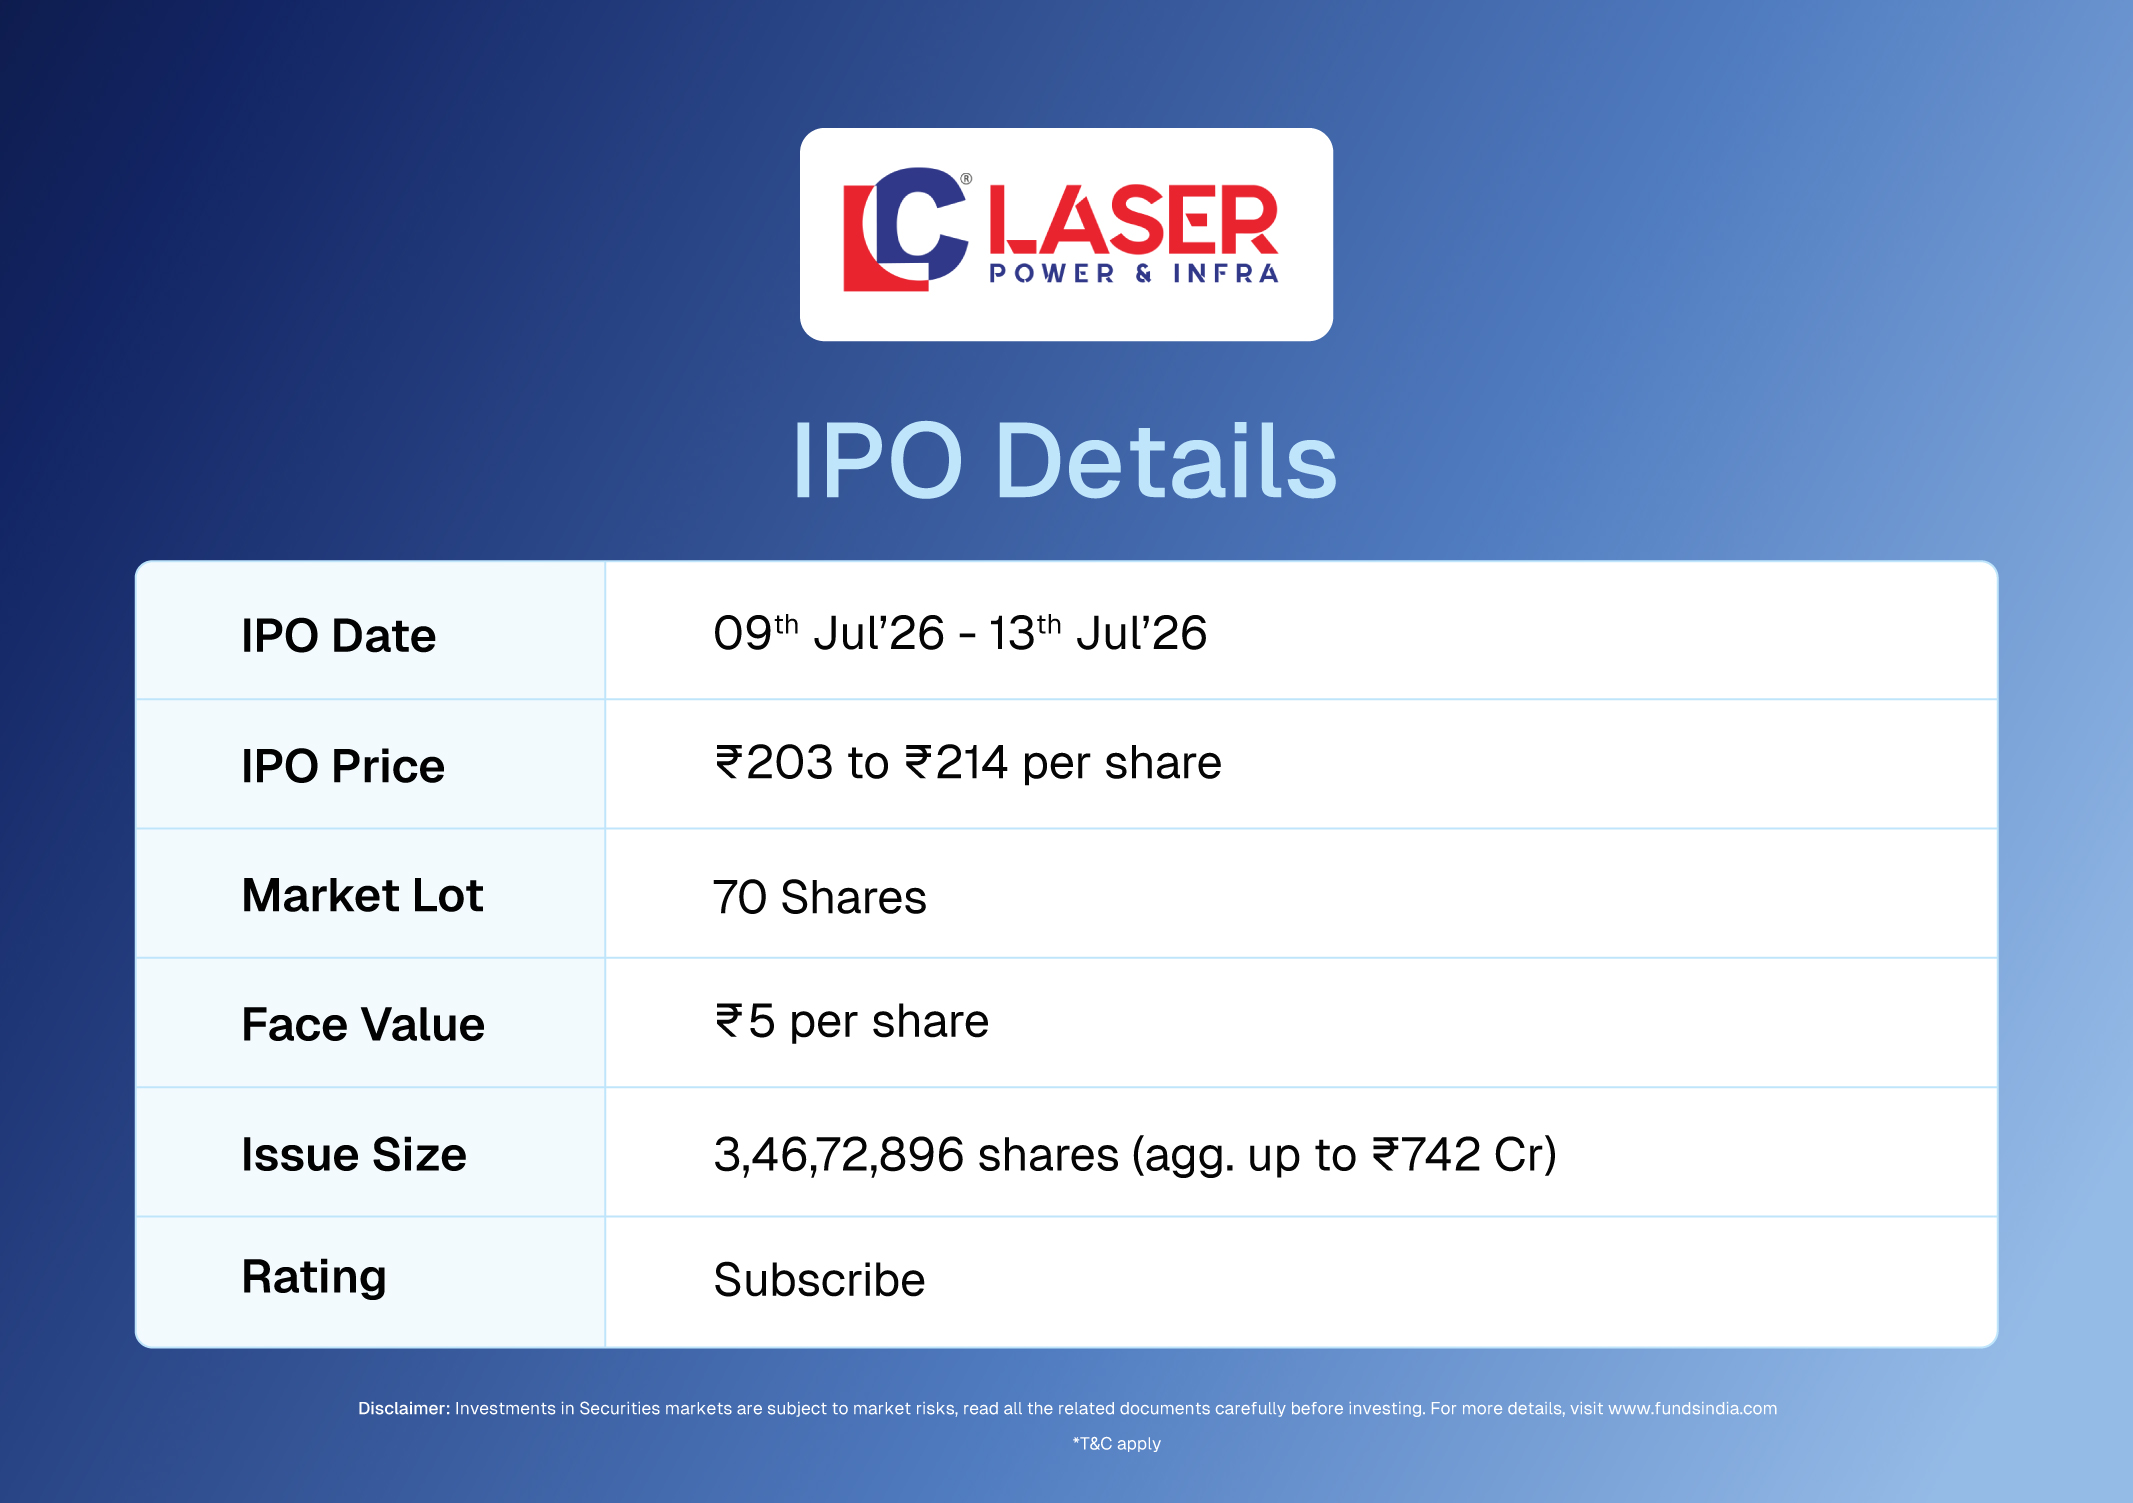
The corporate is enterprise a book-built concern of Fairness Shares of face worth of ₹5 every, comprising a Recent Challenge aggregating as much as ₹542.00 crore by the Firm and an Supply for Sale of as much as ₹200.00 crore by the Promoter Promoting Shareholders.
The proceeds of the Recent Challenge are to be utilized in the direction of the next objects:
- Pre-payment or re-payment, in full or partially, of sure excellent borrowings availed by the Firm, for which ₹490.00 crore of the Internet Proceeds is earmarked towards complete excellent borrowings of ₹935.67 crore as on June 17, 2026.
- Common company functions (not exceeding 25% of the Gross Proceeds).
Funding Rationale
- Backward-integrated dual-engine mannequin spanning manufacturing and EPC: Laser Energy pairs three West Bengal manufacturing items (85,448 MT put in capability) with a turnkey EPC enterprise, and the 2 engines feed one another: cables and conductors for EPC tasks are sourced in-house, with captive transfers rising from ₹259.64 crore in FY24 to ₹354.39 crore in FY26 (+36%), whereas backward integration extends into intermediate merchandise corresponding to aluminium rods and PVC compounds. Barring choose civil works, no EPC work is outsourced to third-party subcontractors, permitting the corporate to regulate timelines and bid competitively on tenders by leveraging cross-feeding economics. The EPC engine has scaled quickly – income almost tripled (~2.9x) over FY24–FY26 to ₹635.07 crore, lifting its share of income from 12.57% to 27.30% – and towards this built-in backdrop, EBITDA margin expanded 403 bps over FY24–FY26 to 12.96%.
- Entrenched East India franchise protected by approved-vendor entry limitations: The corporate is without doubt one of the main gamers by manufacturing capability for energy cables and conductors in East India, an RDSO-accredited registered provider to Indian Railways, and among the many largest authorised distributors of railway signalling, quad and underground energy cables within the area (per CRISIL). Supplying authorities companies requires pre-qualification on observe document, technical functionality and monetary energy – a structural entry barrier behind which Laser Energy serves Indian Railways and the 4 TP Odisha DISCOMs, with authorities prospects contributing 65.16% of FY26 income (up from 53.70% in FY24). Execution credentials compound the moat: 43+ accomplished EPC tasks below RGGVY, DDUGJY, Saubhagya and RDSS, over 85,191 ckm of distribution traces and 113+ substations commissioned, together with tasks in flood-prone riverine islands and terrain the place it was the only bidder (Kalahandi, Odisha) – capabilities that matter as RDSS-led community upgradation concentrates spending in Jap India.
- TS Conductor partnership creates an possibility on India’s transmission and reconductoring upcycle: By way of a strategic manufacturing settlement with U.S.-based TS Conductor Corp, Laser Energy is certified to domestically manufacture superior composite-core conductors – AECC, HTLS, ACSS, AL-59 and eco-conductors – with AECC providing thermal stability as much as 200°C, larger present capability and minimal sag, making it fitted to reconductoring present traces with out increasing right-of-way (per CRISIL). The demand backdrop is substantial: the Nationwide Electrical energy Plan targets transmission line capability rising from 485,544 ckm in 2024 to 648,190 ckm by 2032, and CRISIL tasks the cables and wires market to develop at 11–13% CAGR to ₹2,350–2,550 billion by FY30. The corporate is already monetising this positioning – it’s prequalified and has bid for 18 transmission EPC works of 66 kV and above aggregating roughly ₹900 crore, together with HTLS reconductoring, marking a deliberate transfer up the voltage curve from its 33/11 kV distribution base.
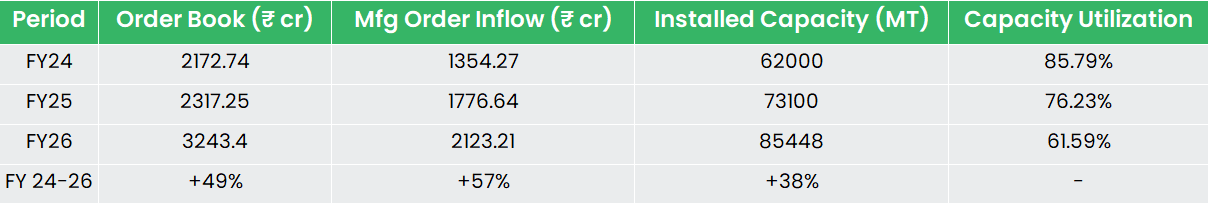
- File order e-book meets freshly constructed capability headroom: The Order Guide stood at ₹3,243.40 crore as of March 31, 2026 – up 40% YoY and 49% over FY24, and roughly evenly break up between manufacturing (₹1,668.89 crore) and EPC (₹1,574.51 crore) – offering income cowl of ~1.39x FY26 income. Manufacturing order influx rose ~57% over two years to ₹2,123.21 crore in FY26. Crucially, the corporate has pre-built the capability to serve this e-book: put in capability expanded 37.82% over FY24–FY26 to 85,448 MT, taking FY26 utilisation all the way down to 61.59% and leaving substantial headroom to soak up order-book execution with out fast capex.
- Monetary Efficiency: The corporate reported income from operations of ₹2,326.10 crore in FY26, down 9.50% from ₹2,570.40 crore in FY25 – attributable, per the RHP, to decrease manufacturing volumes from raw-material shortages and order postponements amid the Center East disaster, alongside decrease EPC execution – although nonetheless representing a two-year CAGR of 15.37% over FY24. Profitability, nonetheless, decoupled from the highest line: EBITDA rose 20.4% YoY to ₹301.44 crore with margin increasing 322 bps to 12.96%, and PAT grew 42.0% YoY to ₹151.59 crore (6.46% margin), a ~3.8x improve over FY24’s ₹40.41 crore. Return ratios are wholesome at 23.32% RoE and 17.83% RoCE. The steadiness sheet is the softer spot – internet debt rose to ₹801.36 crore (1.10x fairness) and working-capital days stretched to 138 from 88 – which the IPO instantly addresses, with the ₹490.00 crore debt compensation retiring over half of excellent borrowings and easing finance prices from FY27.
Key Dangers
- Elevated working-capital depth and stretched receivables
Laser Energy’s operations are working-capital intensive, with internet working capital of ₹1,020.66 crore and commerce receivables of ₹1,374.96 crore as of March 31, 2026, and debtor days of 196 in FY26. Internet working-capital days rose to 138 in FY26 from 88 in FY25, with the cycle funded partly by means of short-term borrowings (internet debt of ₹801.36 crore, 1.10x fairness). As a result of a majority of income comes from authorities entities that carry lengthy credit score durations, progress ties up money earlier than it converts to revenue – so continued scale-up would require ongoing working-capital financing and disciplined assortment, and any lengthening of receivables would pressure liquidity and finance prices.
- Rising buyer focus in a tender-based, government-heavy income base: The highest-10 prospects contributed 72.14% of income in FY26, up sharply from 53.37% in FY24, and authorities prospects accounted for 65.16% of FY26 income. A good portion of contracts are tender-based; whereas the lack of any single buyer has traditionally not been materials given this mannequin, the corollary is that income depends upon regularly profitable aggressive tenders, and rising focus raises the stakes of any slippage in win charges.
- Commodity-linked enter prices and supply-driven quantity threat: Major uncooked supplies – aluminium, metal, copper, XLPE and PVC compound – are commodity- and crude-linked, and value of supplies consumed was ~59.6% of income in FY26, leaving margins uncovered to cost swings. Buyer buy orders typically carry a price-escalation mechanism and the corporate has largely handed on value will increase, so the chance lies much less in pricing than in lags in pass-through and in provide disruption.
Outlook
Laser Energy’s outlook is supported by a document order e-book, freshly constructed capability headroom, a backward-integrated manufacturing-plus-EPC mannequin and its entrenched approved-vendor place in East India, underpinned by structural tailwinds from RDSS-led distribution upgradation, Nationwide Electrical energy Plan transmission additions and the TS Conductor reconductoring alternative. With FY26 volumes curtailed by raw-material shortages and income operating under the prior 12 months, progress will rely upon the normalisation of enter provide, well timed conversion of the order e-book, and a deliberate transfer up the voltage curve into higher-value transmission work. Whereas the enterprise carries an elevated working-capital cycle and a rising, government-heavy buyer focus, the Recent Challenge meaningfully deleverages the steadiness sheet, with efficiency contingent on disciplined receivable assortment and sustained input-cost pass-through as scale rebuilds.
In accordance with the RHP, the corporate’s listed friends are Apar Industries Ltd, Polycab India Ltd, KEI Industries Ltd, Dynamic Cables Ltd and Common Cables Ltd. The peer group is buying and selling at a median P/E of 46.16x, with the very best being 67.05x, and the bottom being 21.05x. On the higher value band, the itemizing market capitalization of Laser Energy shall be Rs. 3,003.88 crore, and the corporate is demanding a P/E of 19.82x, primarily based on the put up concern market capitalization and FY26 diluted EPS. When in comparison with its friends, the problem seems attractively valued, buying and selling at a reduction to the peer group. Based mostly on the above views, we offer a ‘Subscribe’ score for this IPO.

Disclaimer: Investments within the securities market are topic to market dangers, learn all associated paperwork rigorously earlier than investing. Securities quoted listed below are exemplary, not recommendatory. Please seek the advice of your monetary advisor earlier than investing. Please be aware that we don’t assure any assured returns for the securities quoted right here.
Analysis disclaimer: Funding within the securities market is topic to market dangers. Learn all of the associated paperwork rigorously earlier than investing. Registration granted by SEBI, and certification from NISM under no circumstances assure the efficiency of the middleman or present any assurance of returns to traders.
For extra particulars, please learn the disclaimer.
Different articles you could like
Submit Views:
478