


DISCLAIMER: This isn’t funding recommendation. PLEASE DO YOUR OWN RESEARCH.
Administration abstract:
Following my submit on the disappointing IPO of Birkenstock, I made a decision to have a look at 2 extra “busted IPOs” that occurred extra not too long ago, each in Autumn 2025:
Swedish listed Verisure (IPO early October 2025) and Swiss Market Group (IPO mid September 2025). I truly discovered each of them attention-grabbing sufficient to justify smaller positions.
“Busted PE IPO” from Sweden: Verisure Plc
Verisure, the European chief of House Safety and Alarm programs IPOed in Stockholm in late 2025 and initially seemed like an excellent success with a 20% “first day pop”.
This nonetheless additionally marked the height of the share value to date, since then the inventory has been taking place:
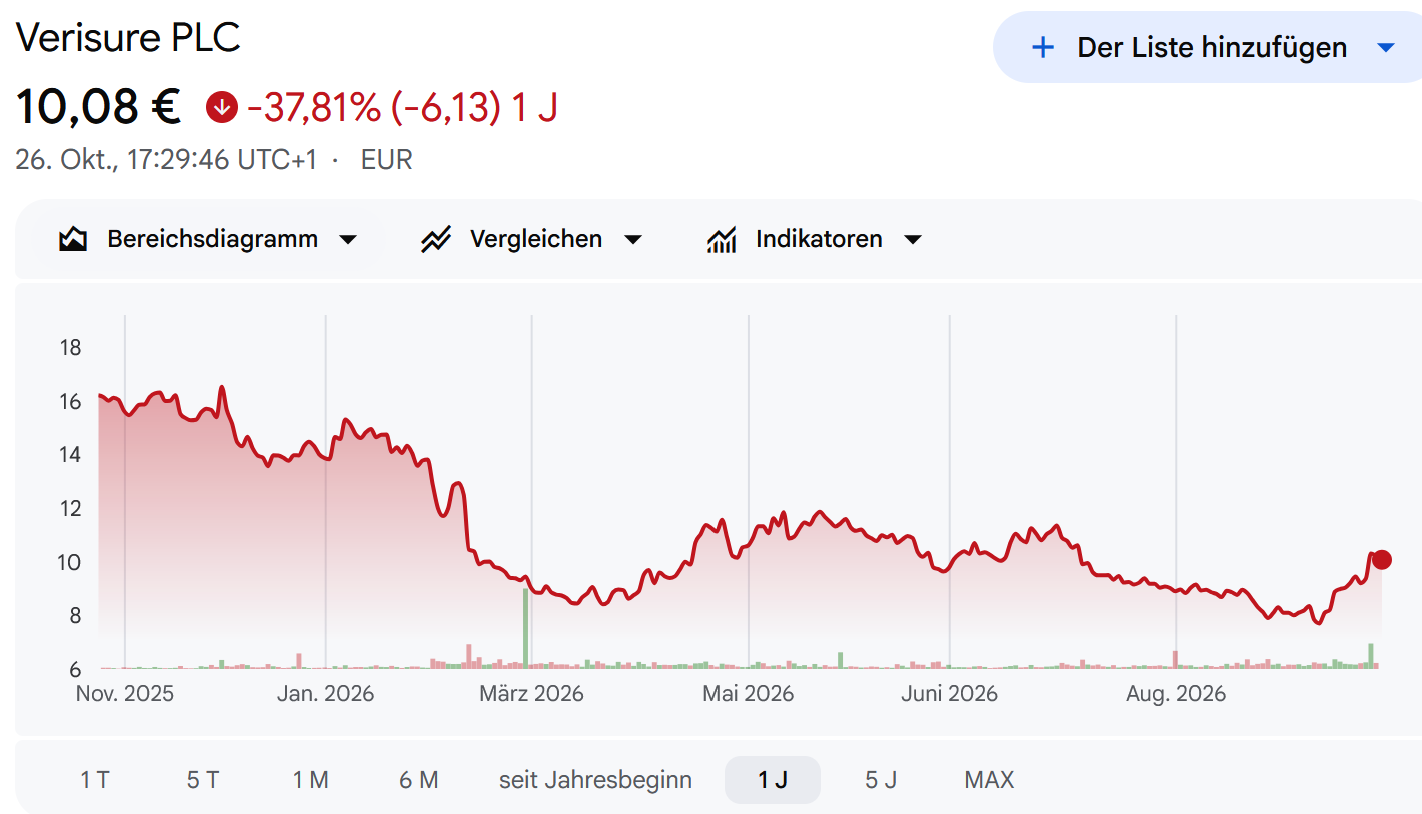
The low was reached at first of October with round 8 EUR per share when the preliminary lock downs expired.
Verisure was IPOed at round 16x EV/EBITDA and is now buying and selling at ~8 NTM EV EBITDA .
This appears to be enticing sufficient that a number of days in the past, the FT leaked that one other PE, this time CVC is serious about taking the corporate personal once more after solely 12 months of being a listed firm.
Verisure itself appears like a possible “Compounder inventory” and has been written up already on a number of Substacks, as an illustration on “Finest Anchor Shares”.
With the CVC hearsay nonetheless, Verisure for me is somewhat an early stage “Particular State of affairs” alternative than a long term funding.
Shareholder Construction:
One attention-grabbing side of the present shareholder construction is that the Pre-IPO shareholders are nonetheless the dominating shareholder Group. Finest Anchor shares has summarized this fairly properly:
Verisure is nonetheless managed by its pre-IPO homeowners. The corporate listed on 8 October 2025 at €13.25 per share, however solely round 26% of the corporate was bought within the IPO. As of 31 December 2025, the most important shareholders have been:
- Hellman & Friedman: 43.7%
- Eiffel Funding (linked to Singapore’s GIC): 16.0%
- Alba (Corporación Financiera Alba): 6.3%
- Securholds: 5.4%. That is the automobile of Luis Gil, a long-time Verisure govt and present board member. It purchased about €185 million of shares within the IPO at €13.25, and the lock-up particularly allowed it to pledge its shares as collateral for the debt used to finance that buy. This can be a stake price watching with the inventory round 40% beneath the IPO value: share-backed loans often include loan-to-value covenants, so an extra drop may pressure a sale no matter what the basics say.
- Administration and former workers: about 3% (the CEO alone holds about 1%)
The above merely reveals that roughly 70% of the shares are held by traders who will, eventually, need to promote (or at the least have the choice to). At at present’s share value, H&F’s stake alone is price round €3.7 billion, near half of Verisure’s market cap. The lock-up calendar appears like this:
- 180 days for the big shareholders (H&F, Eiffel, Alba, Securholds): expired in early April 2026, to allow them to already promote. It’s a “identified subject” by now.
- one year for board members and senior administration: expires proper about now (October 2026), with different administration shares launched in phases over the next 3-12 months.
- Orderly advertising and marketing settlement till October 2027 (extendable in six-month increments as much as October 2029): gross sales by current traders want H&F’s consent and are usually coordinated by means of block trades.
So principally CVC can negotiate with H&F for 70% of the shares which makes it a somewhat easy course of. A really possible final result of an negotiation can be that H&F and the opposite shareholders might want to “roll” a part of their publicity into a brand new take care of CVC which is able to cut back the required cheque size-
Simplified Particular scenario calculation
Now one can speculate at what value H&F and the others can be prepared to promote. A quite simple assumption can be that they need to see the IPO value of 13,25 EUR.
This may equal a premium of round 40% to the worth earlier than the “hearsay leak” and in line what one has seen in related Nordic PE buy-outs up to now.
Primarily based on this assumptions, we are able to calculate a quite simple “anticipated honest worth” for Verisure:
Assuming a 50% likelihood for a deal at 13,25 EUR and a 50% non-deal likelihood with the inventory going again all the way down to 9 EUR, the anticipated worth of the inventory can be 0,5*13,25+ 0,5*9 = 11,13 EUR or ~11% increased than the present share value on the time of writing.
One can now attempt to make extra elaborate eventualities however in precept this appears fairly enticing, particularly as underneath Swedish guidelines, a deal may occur somewhat rapidly if the events agree.
Abstract Verisure
For that cause, I established a 1,5% place for my “particular State of affairs” bucket at a share value of barely beneath 10 EUR per share. I sized this somewhat small as it’s not clear if a deal is definitely occurring. If CVC formally calls the deal off, I’ll promote. If a proper provide is made, I’ll revisit the place.
Swiss Marketplaces AG
Following my “UK Portal Ache basket” submit from late September, one reader truly prompt within the remark to have a look at Swiss Marketplaces AG (SMG).
After a re-examination, I truly obtained extra excited concerning the inventory. SMG is the clear number one in Switzerland, each, for Actual property and Vehicles (so like an Autotrader and Rightmove mixed), plus they personal some smaller comparability websites in Switzerland.
Curiously, the origin of the 2 principal portals, Immoscout24 Schweiz and Autoscout24 Schweiz was the German Scout Group that bought these two portals in 2014 to Swiss writer Ringier.
In 2021 then, these two portals merged with their principal Swiss competitor TX Markets (owned by listed TX Group) to the Swiss MArketplaces Group.
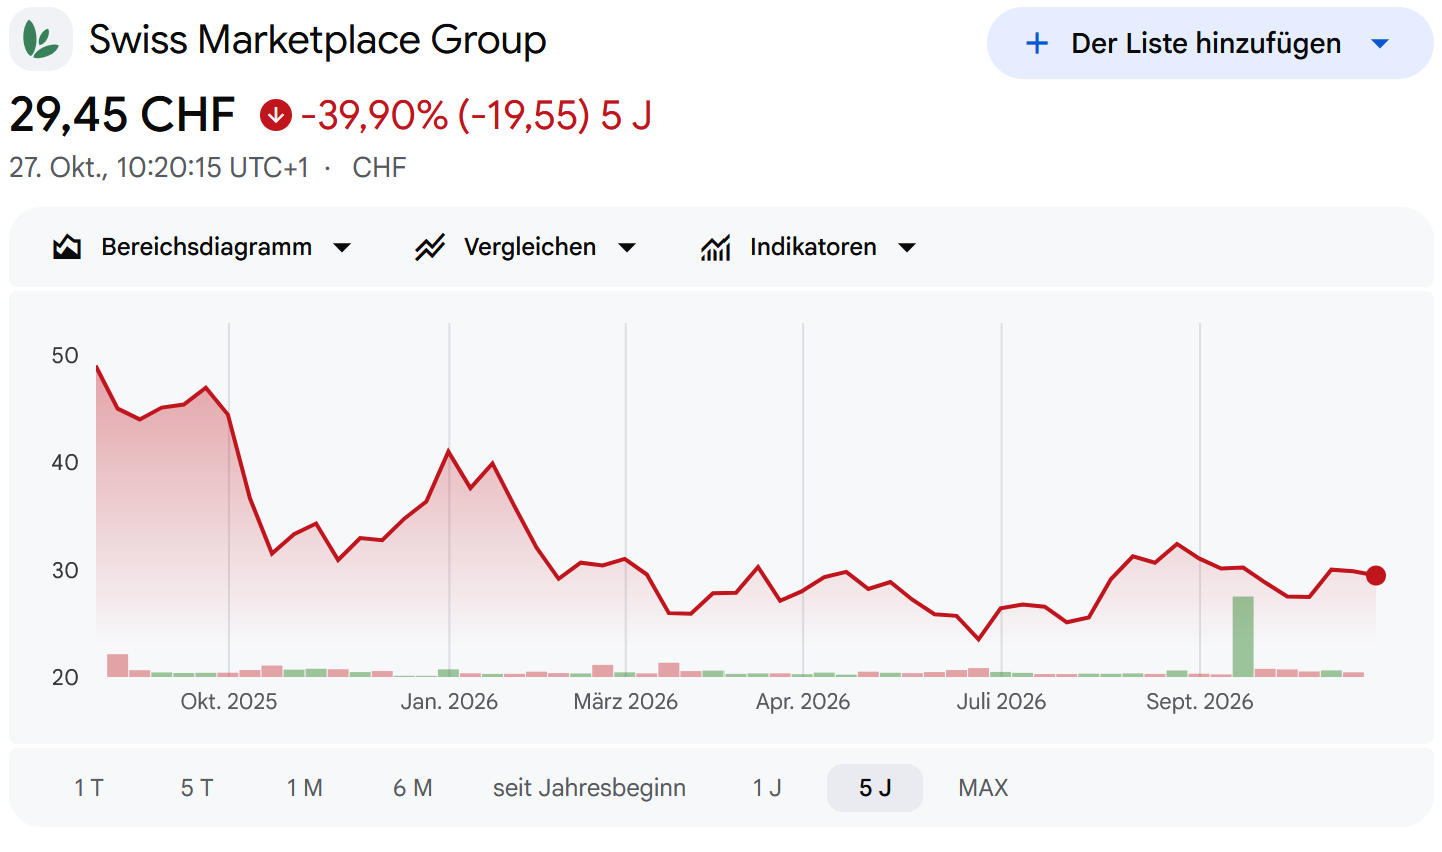
As talked about at first, SMG IPOed in autumn 2025 and searching on the inventory chart we are able to see that much like Verisure, the IPO was the height of the worth vary to date:
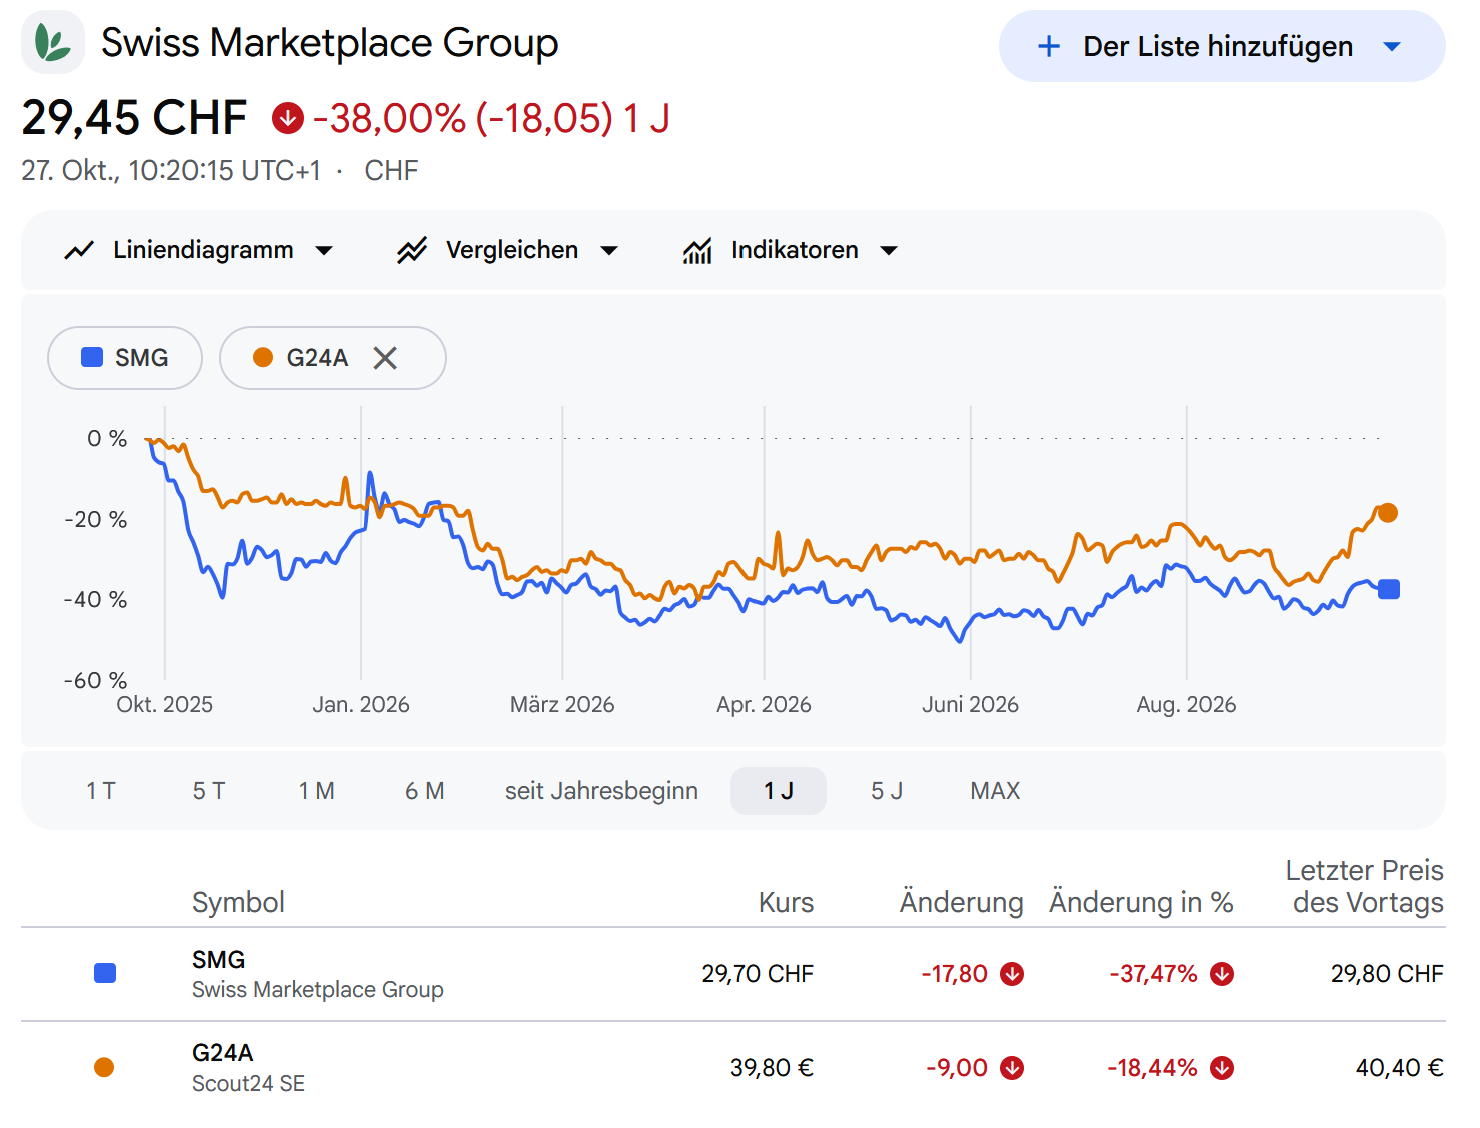
In comparison with the “previous father or mother” Scout24 Group, SMG has carried out considerably worse over the previous 12 months:
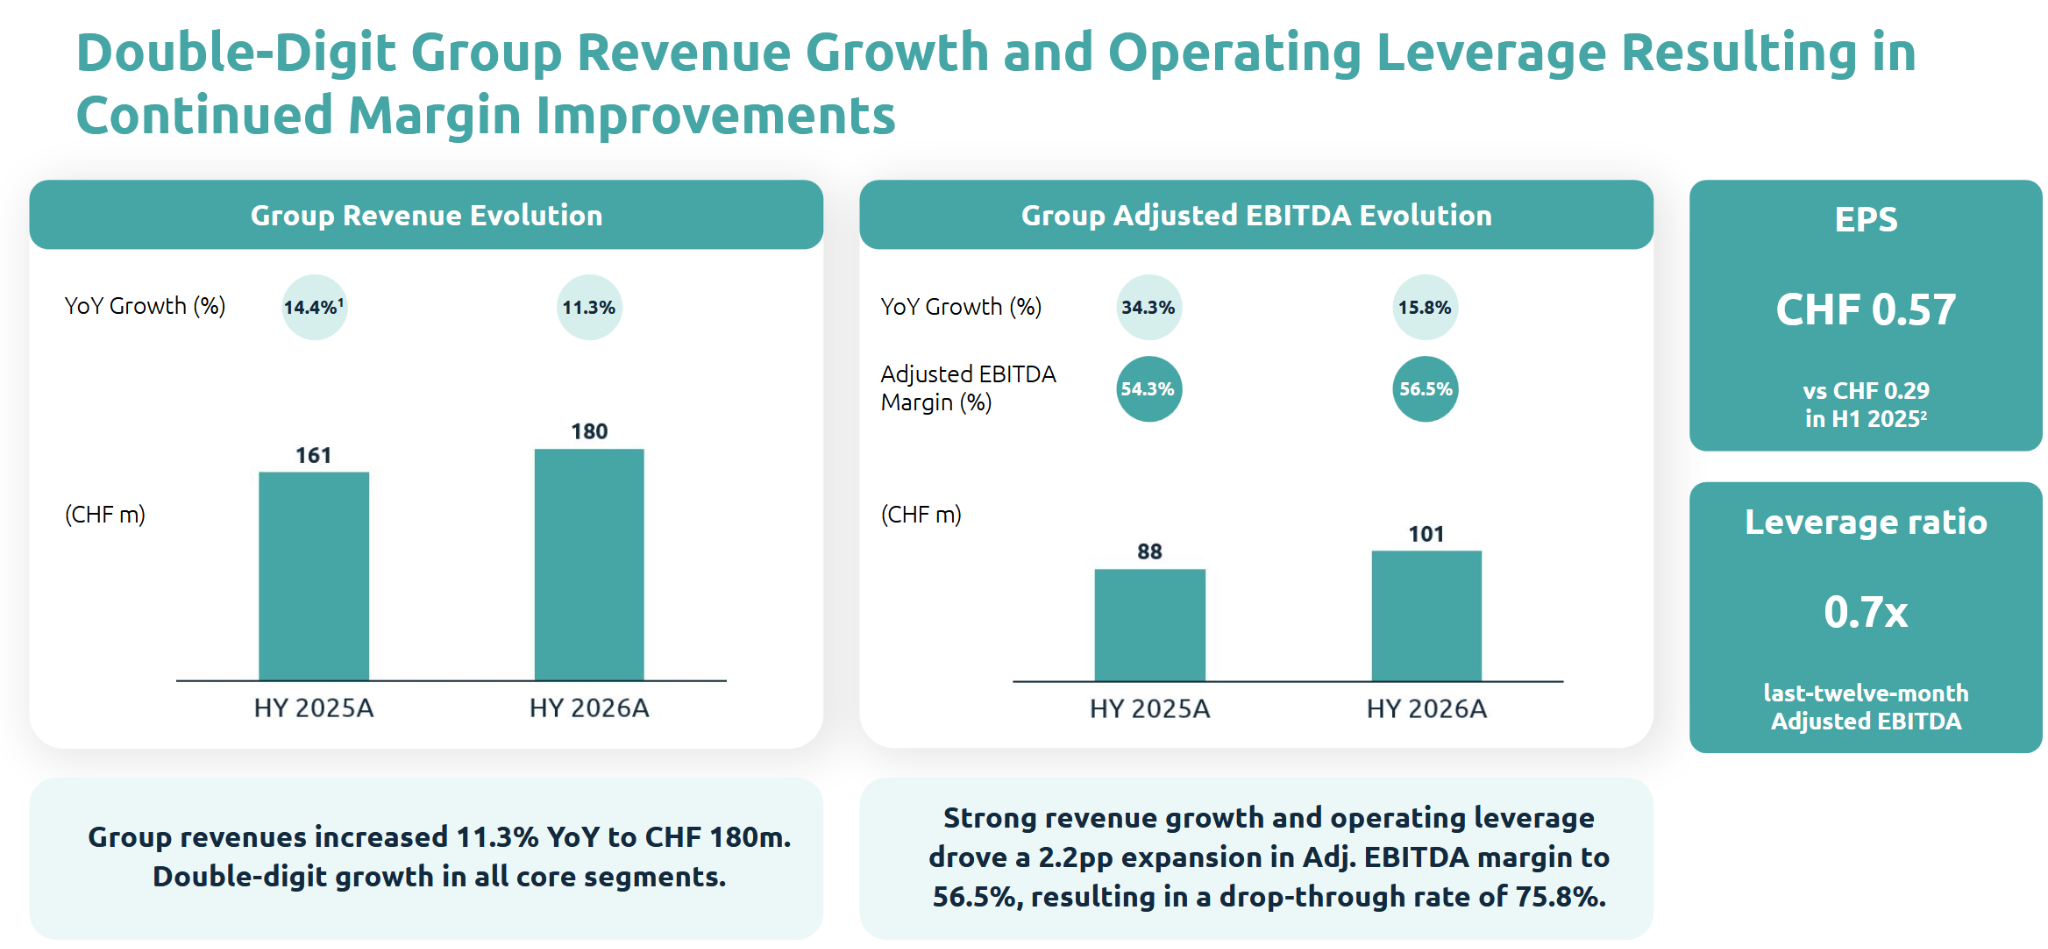
And this regardless of very strong working numbers. for the primary 6M in 2026, gross sales have been up +11% and EBITDA +17%:
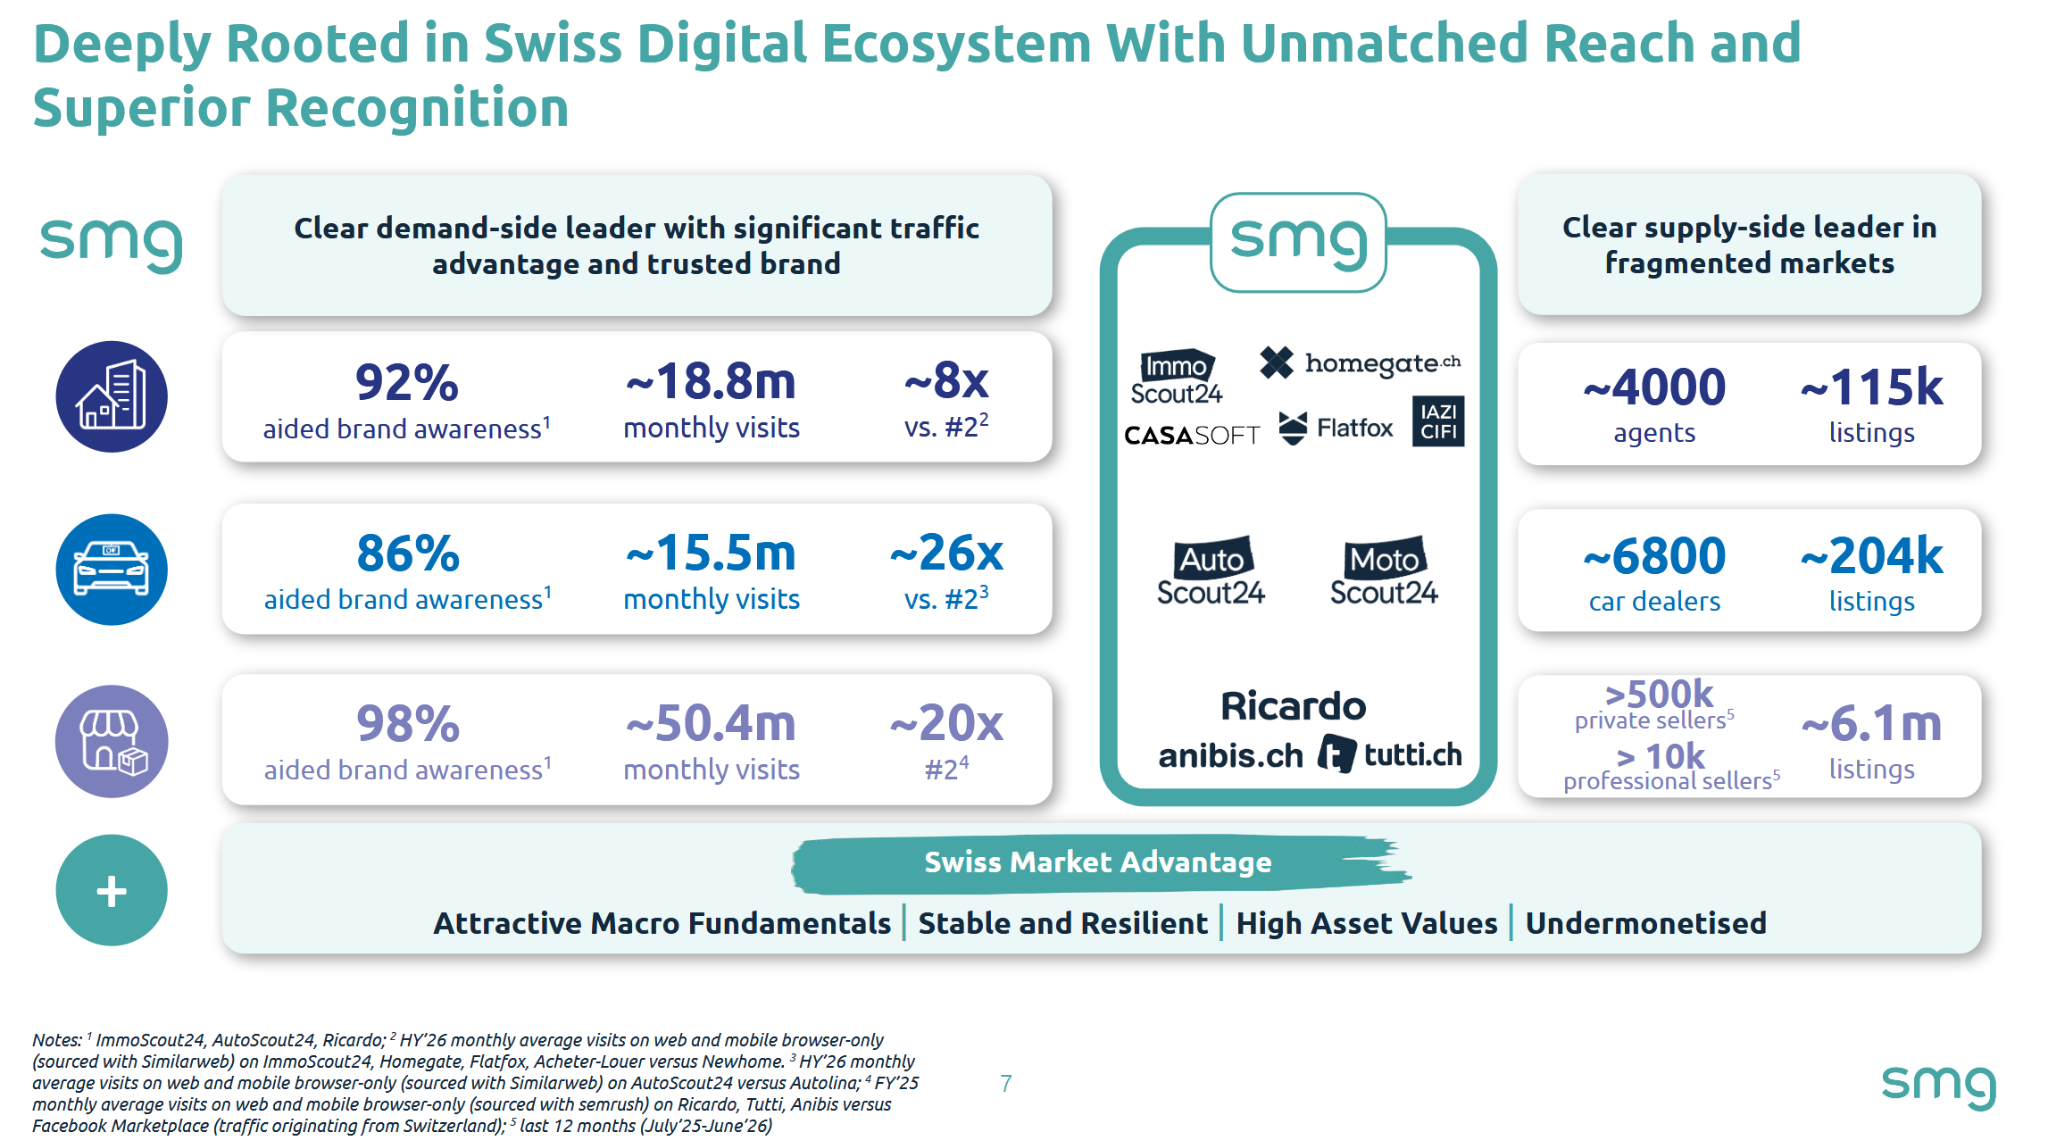
This chart from the 6M outcomes presentation reveals how dominant they’re in nearly each space in Switzerland:
AI menace
As talked about in my “Portal Ache basket” submit, I believe that particularly actual property and automotive portals won’t be disrupted by AI brokers or related instruments any time quickly.
I’m extra sceptical about journey, however SMG has no publicity to journey.
Shareholder construction:
As in Verisure’s case, the Pre-IPO homeowners are nonetheless the bulk homeowners of SMG:
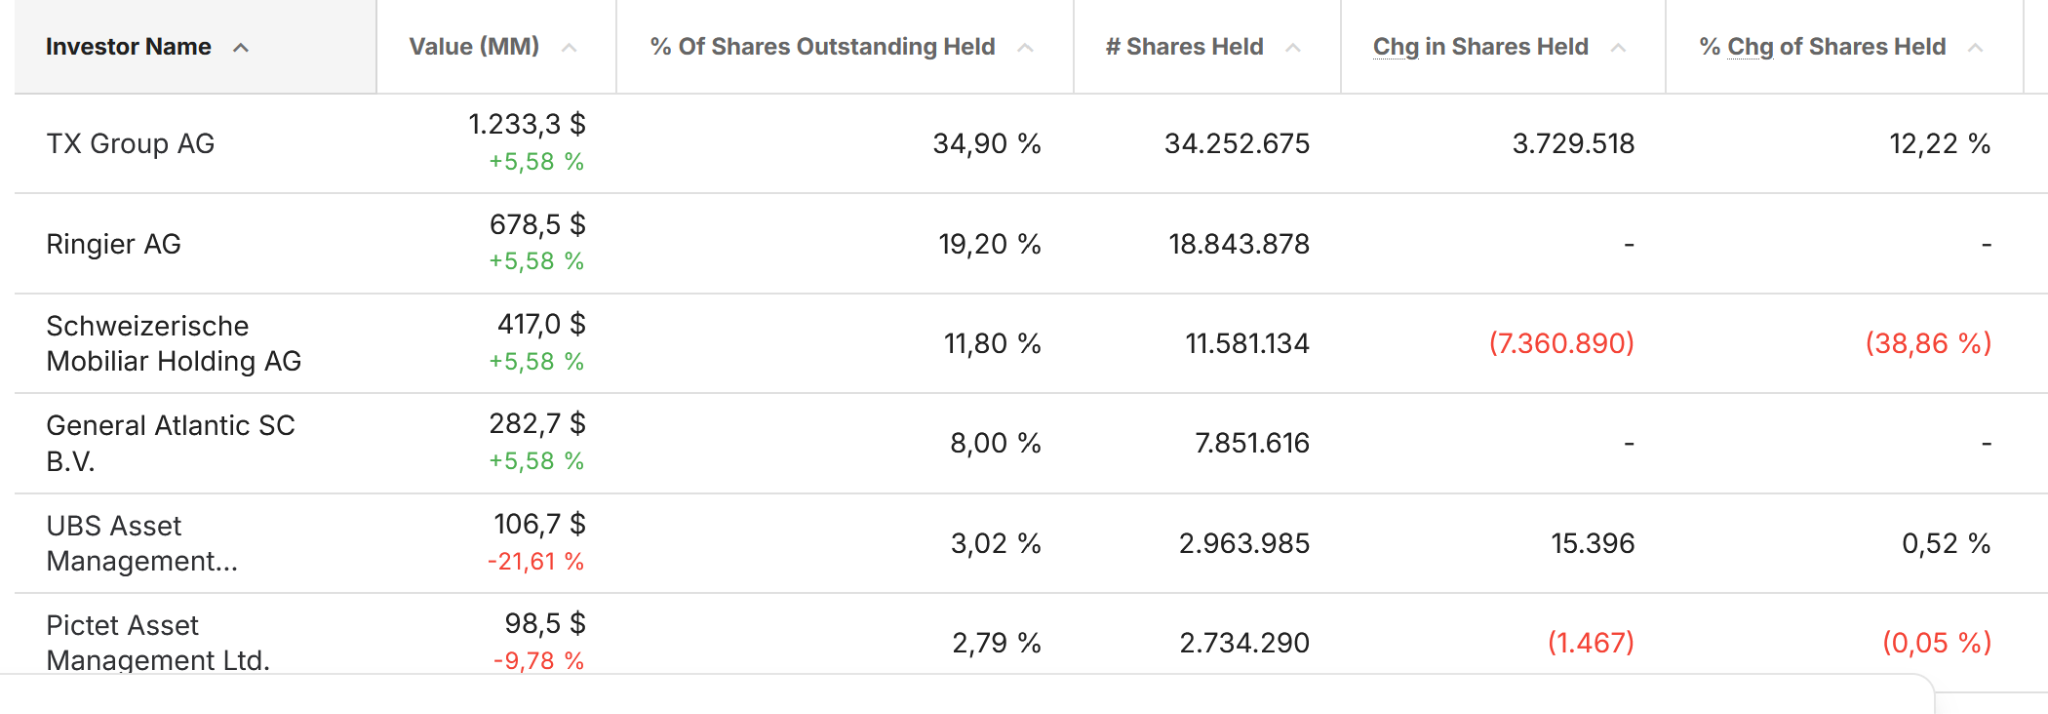
The largest traders are the 2 Swiss publishing Teams TX Group and Ringier. In a current transaction, Swiss Insurer Mobiliar bought ~7,5% of SMG’s shares at 28,50 CHF per share. Curiously, TX Group purchased ~3% of MSG and SMG itself purchased again 1%. Based on this text, Mobiliar has agreed to an extra lock-up till March 2027 following the position.
TX Group is now at 34,9%. Based on the Articles of Affiliation of SMG, the crossing of the 35% threshold would set off a compulsory take over provide by TX Group.
So with Mobiliar promoting down, there’s clearly concern of a inventory overhang out there which could clarify the relative underperformance to Scout24. I additionally assume that Common Atlantic, a US primarily based PE investor won’t keep without end. Curiously, additionally Ringier diminished its stake earlier than and through the IPO from initially 29,5% to the present 19%. Solely TX Group appears to haven’t bought shares, however as talked about above, purchased extra.
Consequently, the valuation of SMG is for a Swiss inventory, fairly reasonable. At ~19x NTM P/E, SMG is valued in keeping with Scout24. Leverage is sort of low (beneath 1x Internet Debt/EBITDA) and with ~3,4% the inventory has a horny dividend yield for a Swiss inventory.
What I discover attention-grabbing is that SMG clearly has some runway to extend profitability. Scout24 as an illustration has an EBIT margin of ~50% whereas SMG “solely” reveals 35%. Particularly the “different marketplaces” appear to have some room to enhance profitability.
There may be clearly the inventory overhang particularly from Mobiliar, however operationally SMG appears to carry out fairly properly and the Swiss economic system is doing higher than lots of their neighbours.
So the inventory overhang “blues” may truly characterize a very good alternative to get a top quality asset at an inexpensive value.
Abstract:
General I discover SMG fairly enticing as a possible 4th member of my “Portal Ache basket”. In comparison with Scout24 in Germany, I like the higher diversification and the publicity to a rustic that performs significantly better economically.
Due to this fact I made a decision to allocate 2% of the portfolio into SMG at present costs of ~29,50 CHF per share.
I may truly consider making it an excellent larger place in the event that they proceed to carry out properly operationally and the inventory retains being depressed due to extra promoting from a few of the massive shareholders.