


Disclaimer: This isn’t funding recommendation. PLEASE DO YOUR OWN RESERACH.
Fuchs SE (Purchase)
As talked about within the feedback of the preliminary write-up, I’ve re-entered Fuchs Widespread shares with a 2% place. I did promote Fuchs after a disappointment virtually 1 12 months in the past. So I used to be fairly stunned that they really introduced “blow out” numbers for Q2 just a few days in the past:
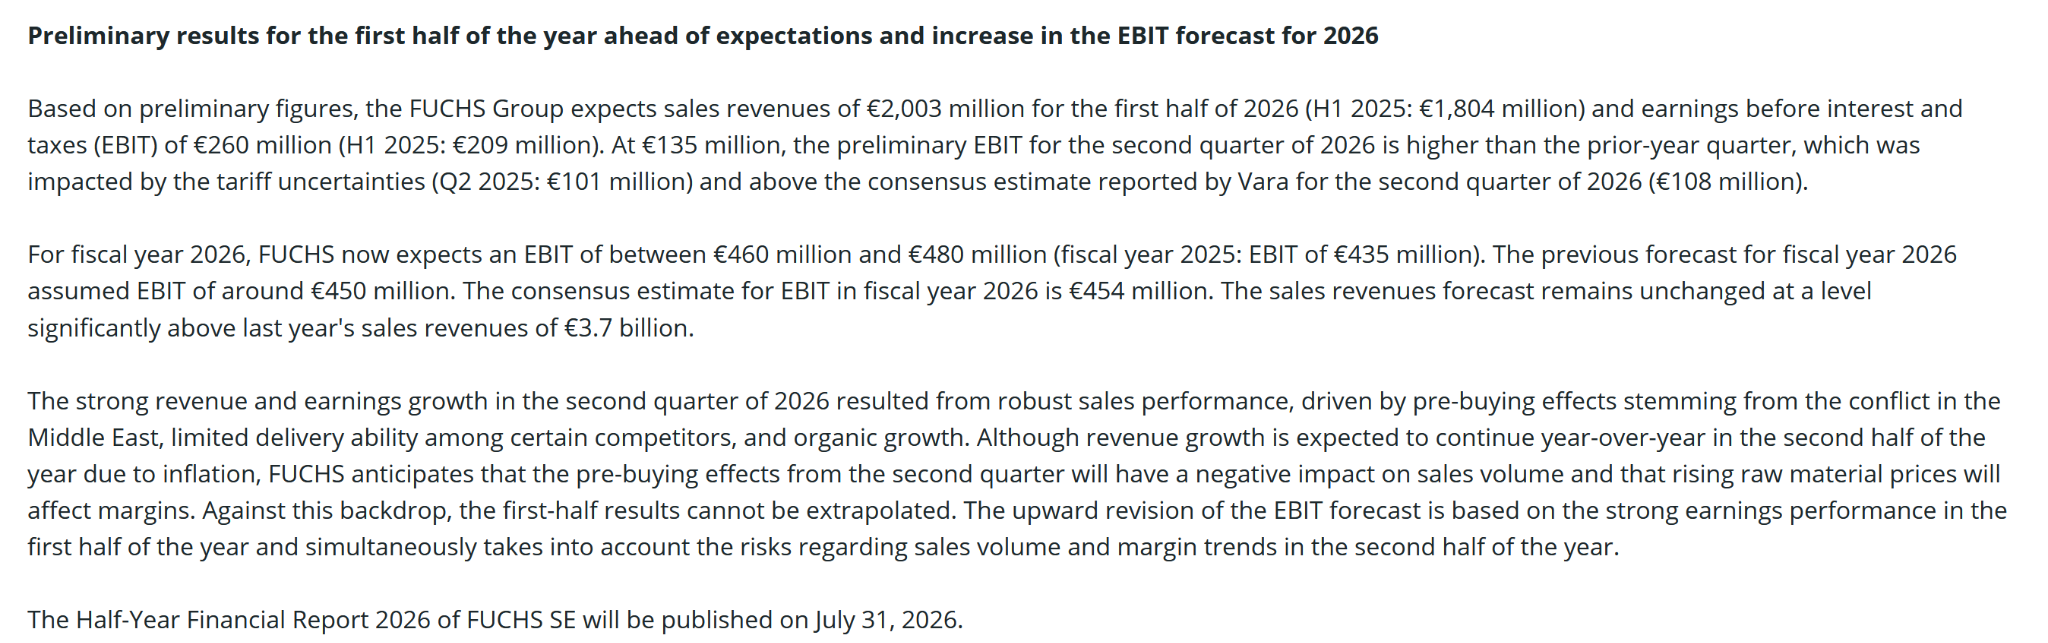
I talked to another buyers about this they usually largely talked about that this seems (as soon as once more) as a one-time impact with perhaps compensating adverse outcomes some quarters down the highway, similar to what occurred after the assault on Ukraine.
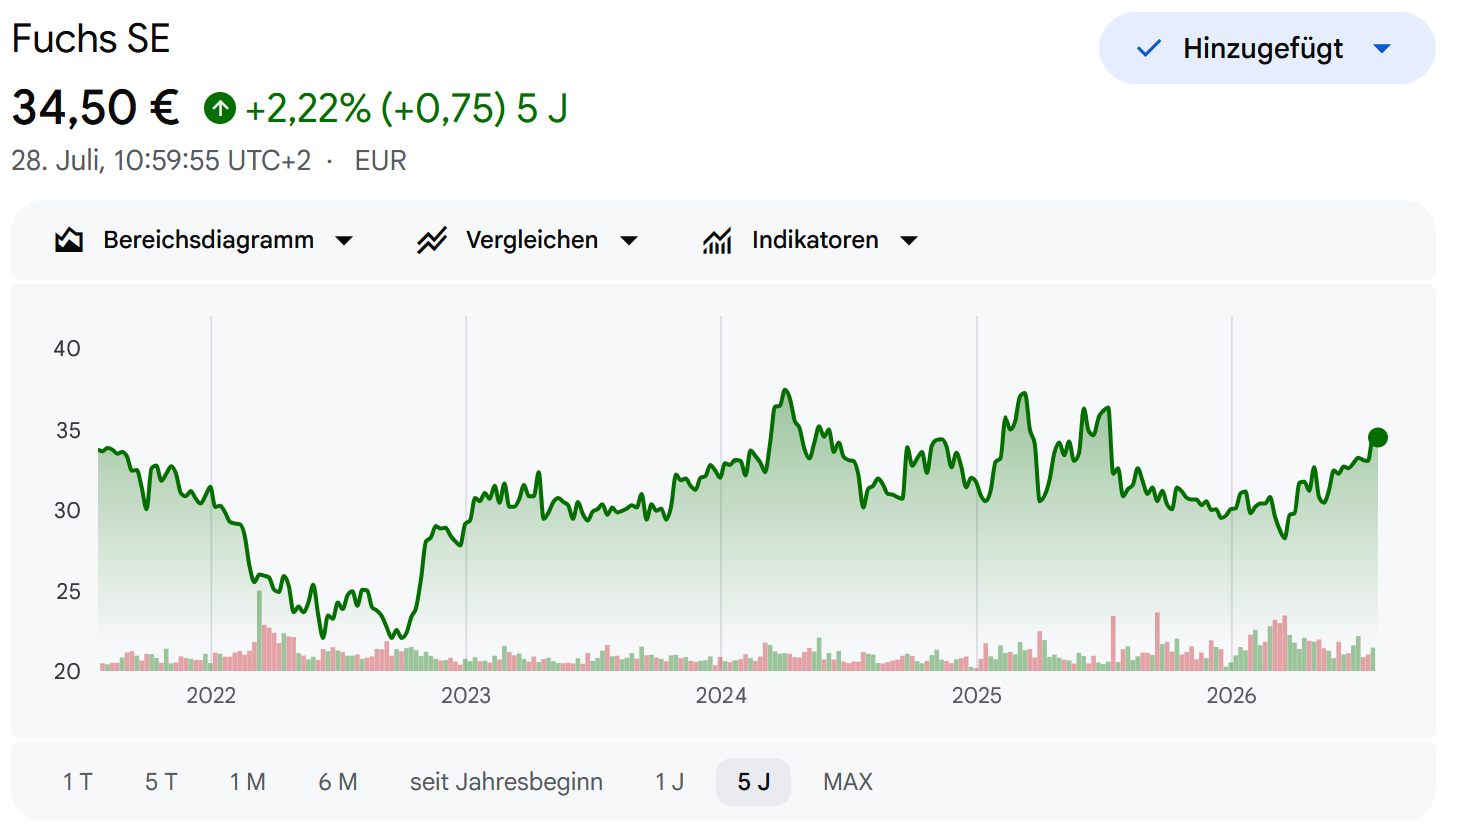
That probably explains the very muted response to a 35% enhance in EBIT in Q2 and a major enhance within the full 12 months steering that in response to the discharge already is conservative.
I really purchased again the shares barely increased to the extent I strong them final 12 months (33,50 EUR vs 31,50 promoting worth).
What I discovered particularly fascinating within the assertion from Fuchs was the next passage:
“The robust income and earnings progress within the second quarter of 2026 resulted from strong gross sales efficiency, pushed by pre-buying results stemming from the battle within the Center East, restricted supply capability amongst sure opponents, and natural progress. “
Digging a bit bit deeper one can comparatively simply discover articles that the Gulf area was and is a serious exporter of lubricants and particularly the underlying base oils which might be wanted for prime efficiency lubricants.
As well as, on main base oil refinery in Qatar was straight hit by Iran in response to this text:
“Roughly 44% of U.S. Group III demand is often provided from the Persian Gulf, however that offer is now largely offline. Harm to Shell’s Pearl GTL facility in Qatar—brought on by Iranian rocket strikes—has halted manufacturing from a key supply of roughly 30,000 barrels per day, with repairs anticipated to take at the very least a 12 months. Further disruptions stem from pressure majeure declarations by producers in Bahrain and the UAE, in addition to the continued closure of the Strait of Hormuz, which has stranded product within the area. “
Though I don’t know precisely how Fuchs sources its base oils, it appears that evidently in the interim that they can ship whereas others have issues.
After all the scenario with Iran can change any day with a single Tweet, however I suppose that some provide chain managers are perhaps rethinking their dependence on Guld primarily based lubricants which could possibly be a structural alternative for an unbiased participant like Fuchs.
We might want to see how this develops, however I feel Fuchs seems much more fascinating now at the very least from my perspective.
Paypal Particular scenario (Purchase)
In March I wrote about Paypal for the primary time and again then, regardless of being low cost, Paypal was one for the “too laborious” pile for me.
Then, after the strategy from Stripe and Introduction I discussed the next:
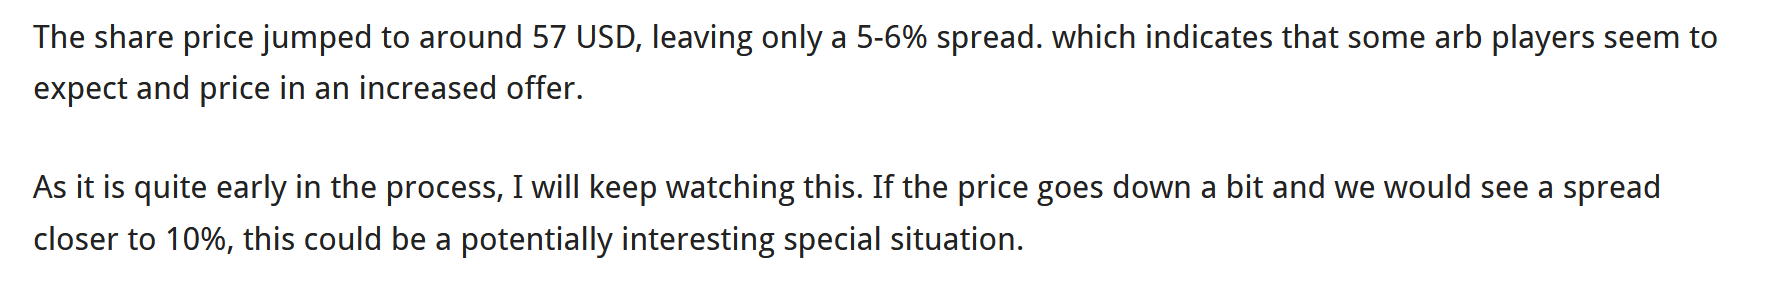
Final Friday, the inventory traded at 55,5 USD, providing a 9% “low cost” to the potential acquisition worth which motivated me to purchase a 1,5% place at that degree.
The chance return ratio is just not too unhealthy at that degree. The “undisturbed” worth is ~47 USD and there’s a fairly good likelihood of a better bid both from Introduction/Stripe or perhaps one other competitor would possibly enter the race.
As at all times, one wants to arrange for volatility round any information in both path however I feel it affords a pleasant, uncorrelated “guess” on a doubtlessly increased clearing worth.
One key participant right here is clearly the brand new CEO whose large bonus is tied to a inventory worth enhance that to my data is far increased than the 60,50 USD provided. So he clearly has an incentive to carry out for a excessive worth OR a pleasant “golden parachute” from the consumers.
Nonetheless yet one more factor is necessary to say: It is a particular scenario funding for me. So if for some cause, Stripe & Introduction withdraw their bid, I’ll promote, it doesn’t matter what. For a “Worth funding” I nonetheless discover Paypal too laborious at this stage.
On the time of writing, the Paypal share worth has climbed again to 58,40 USD per share, a degree the place I’d not purchase (extra).
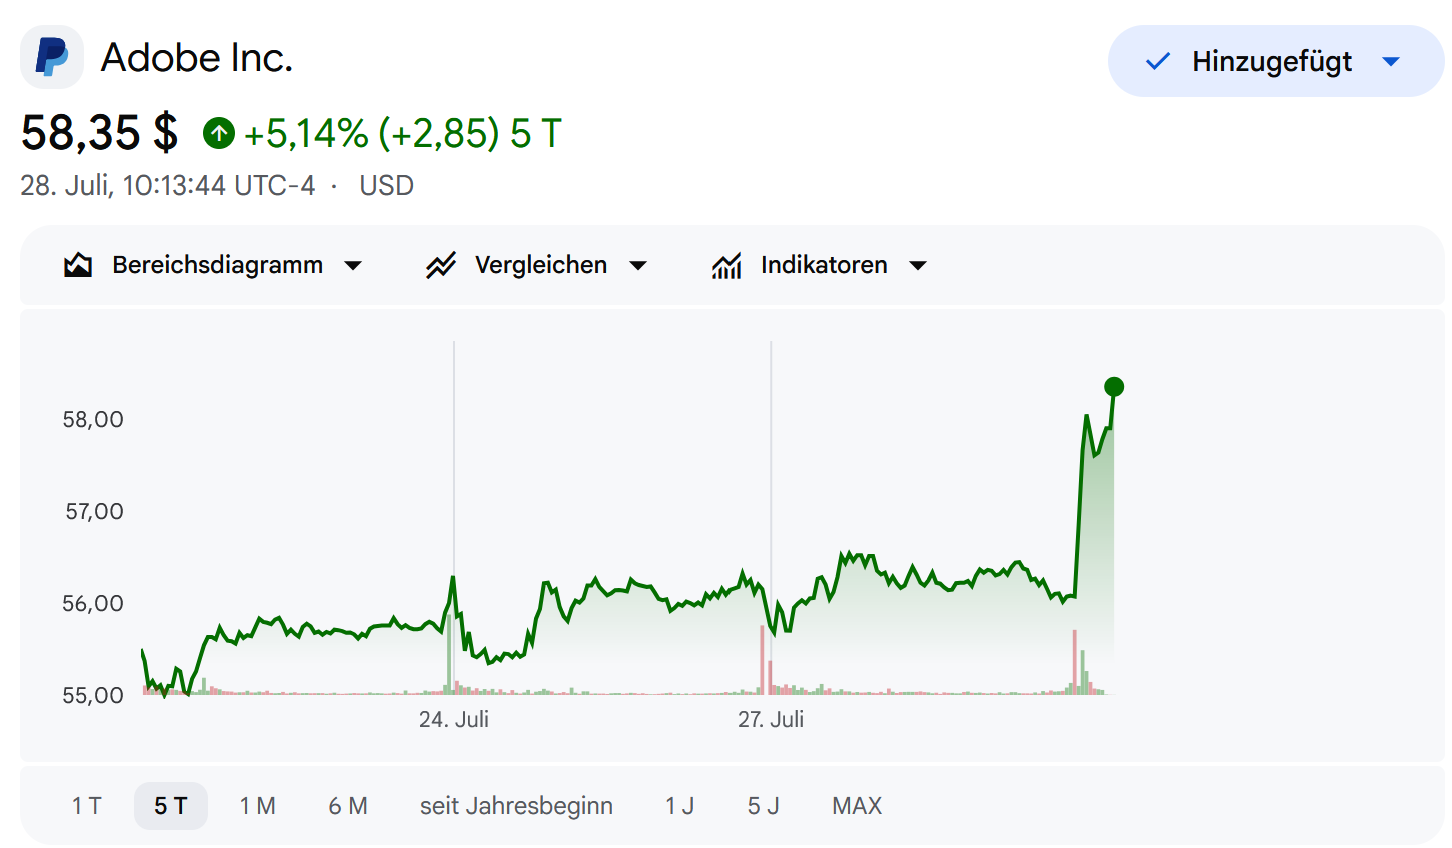
(for some unusual cause, Google Finance says Paypal is now known as Adobe 😉
The primary cause for the current leap appears that Q2 numbers appear to have crushed expectations.
EVS (Broadcast) SA – Publish mortem
I had written up EVS SA (previously generally known as EVS Broadcast SA) some two years in the past. The thesis was the next:

So the corporate had bold progress targets, was comparatively low cost and financially tremendous strong.
Initially, the case went effectively, with 2024 turning out to be a extremely good 12 months.
Nonetheless, 2025 began with a slight disappointment in Q1. Then the inventory jumped as they’d gained a (biggish) contract for the Soccer Worldcup in Q2.
Nonetheless, that was quickly adopted by disappointing 6M numbers. The preliminary 2025 numbers weren’t nice, however again then the outlook for 2026 was nonetheless fairly optimistic in March.
However then in Might, along with the Q1 buying and selling replace, they already guided to the decrease finish of the vary and the CFO girl out of the blue left with out direct alternative.
This was after all very disappointing and I began to promote a part of my stake after that. We will additionally see that the share worth is now decrease than once I wrote up the inventory in June 2024:
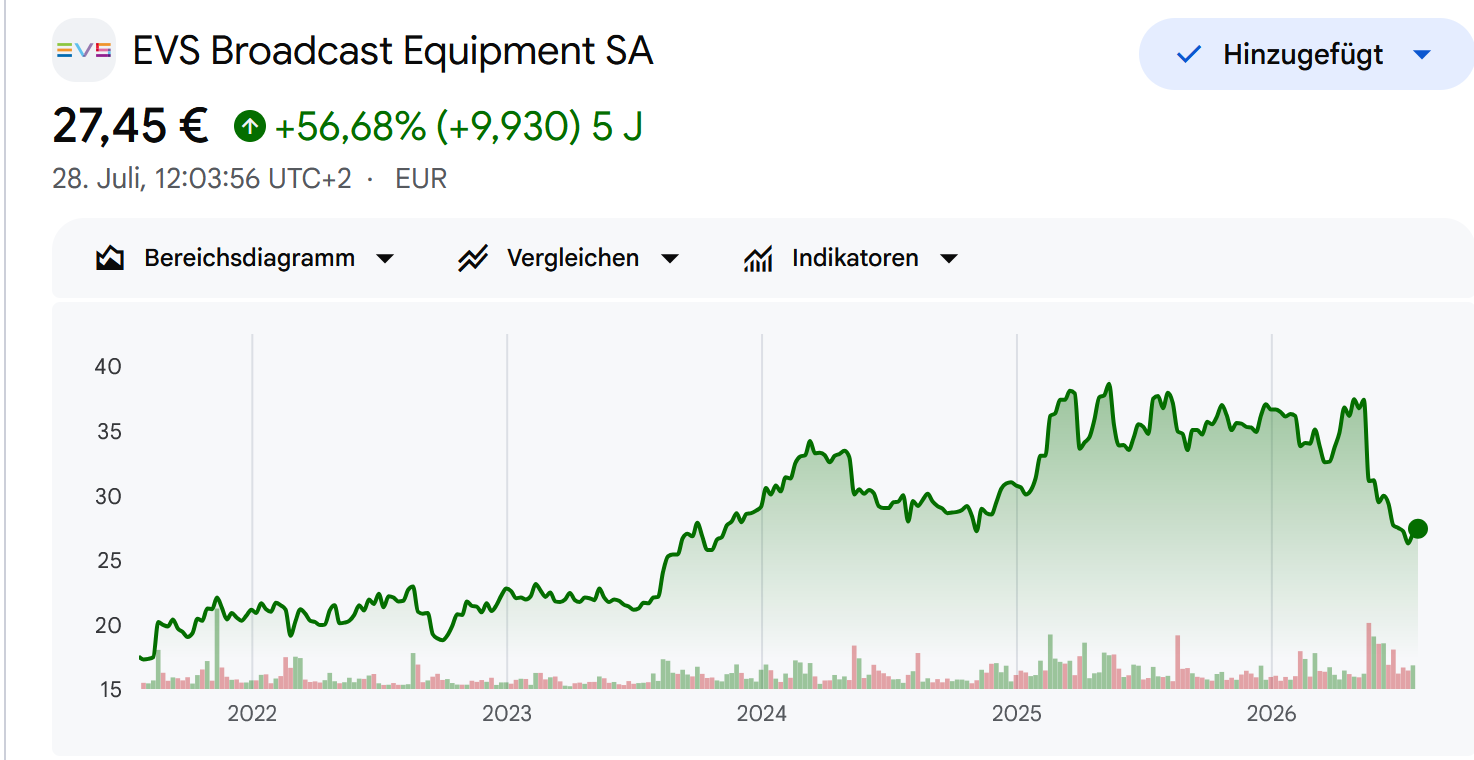
An EBIT /working revenue on the decrease finish of the 40-50 mn vary would imply an EBIT much like 2023 and that in a 12 months with two very massive occasions, the Winter Olympics and the Soccer Worldcup.
Whereas that isn’t a disaster, they’re now clearly distant from the ten% p.a. progress path that I had underwritten initially. To be sincere, I don’t totally perceive why the enterprise is so weak.
What I additionally discovered fascinating, that Canadian listed competitor Evertz has been doing very effectively over the previous 12 months at the very least trying on the share worth:
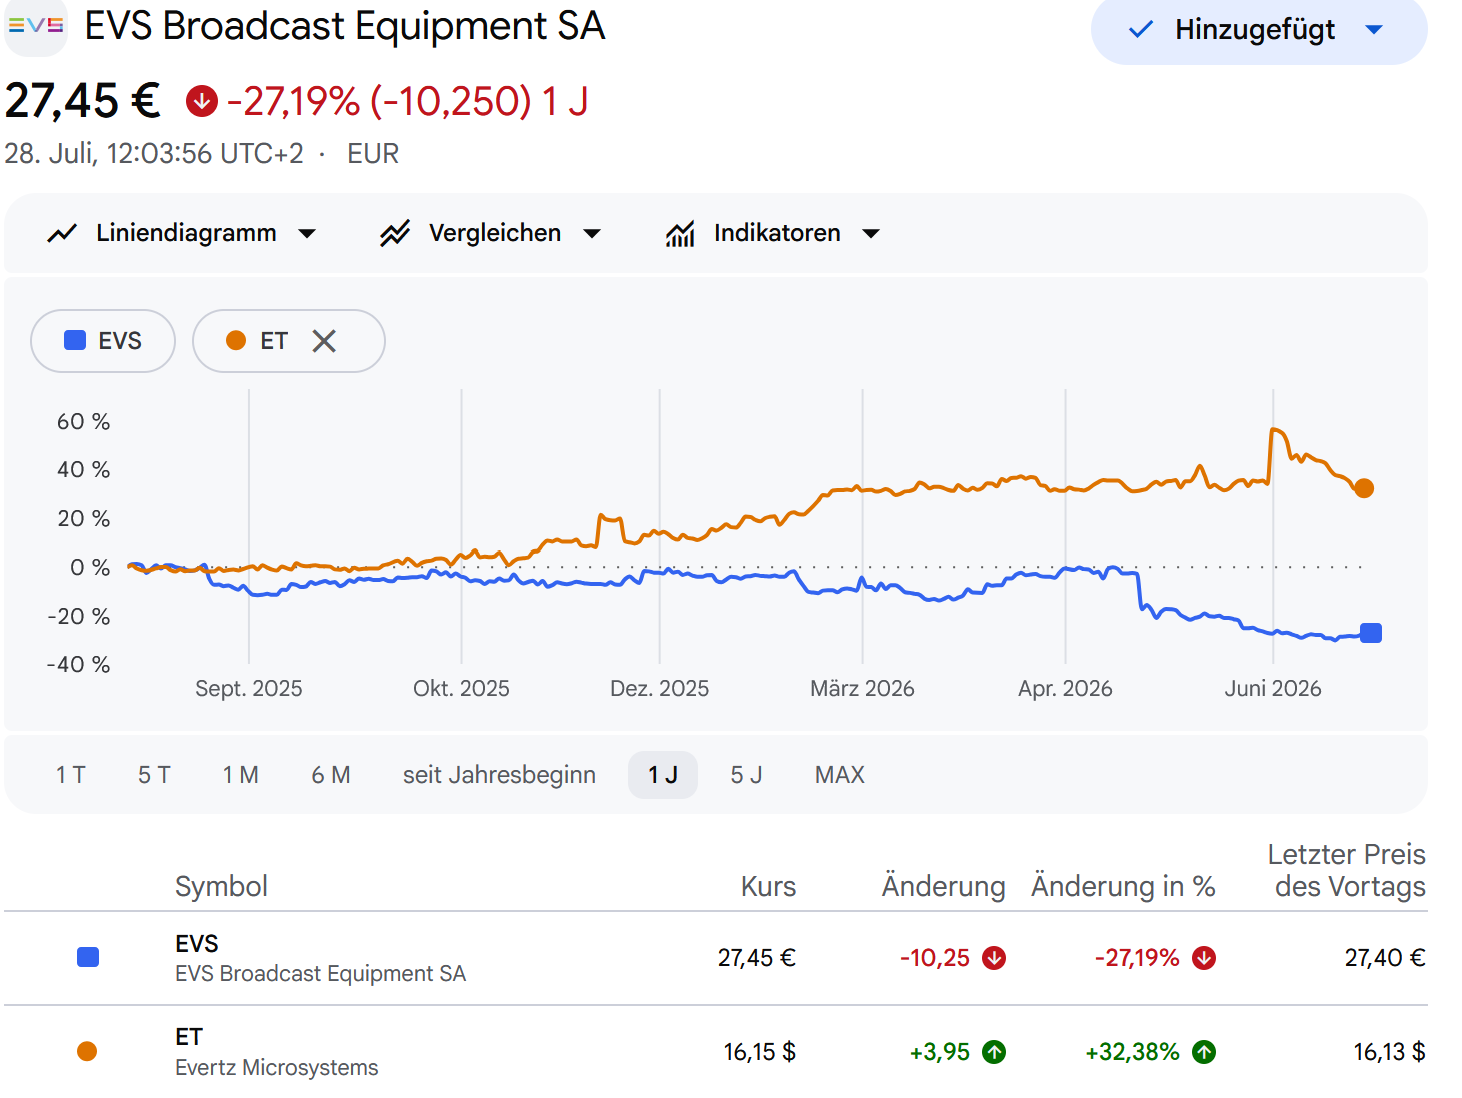
Whereas Evertz struggled a bit bit within the US market, that particular passage was very fascinating of their newest report (that features Q1):
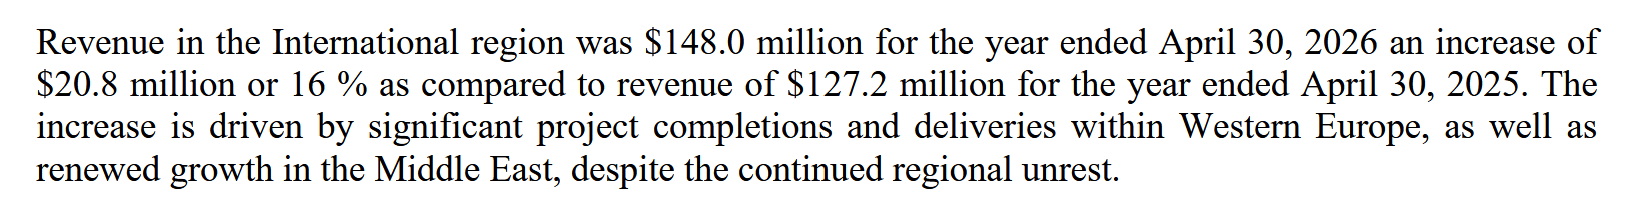
So whereas EVS claims that the struggle within the Gulf is the offender for the unsatisfactory enterprise, Evertz speaks of “revived progress” within the Center East. That’s fairly shocking in my view and casts some doubts on the EVS Broadcast story.
So general, I’m not that assured in EVS in the interim and determined to promote my place completely as I see higher alternatives elsewhere.