


Indirectly. IRDA doesn’t allow claims-based loading.
However in a quiet, covert, and devious method.
How?
Let’s discover out on this submit.
What does IRDA allow and what it doesn’t?
Claims-based loading means rising the premium since you made a declare within the coverage.
IRDA Medical insurance laws don’t allow claims-based loading.
Which means the insurance coverage firm can not enhance your premium merely since you made a declare within the earlier yr.
That is explicitly written in IRDA Well being Insurance coverage Laws, 2016. In black and white.
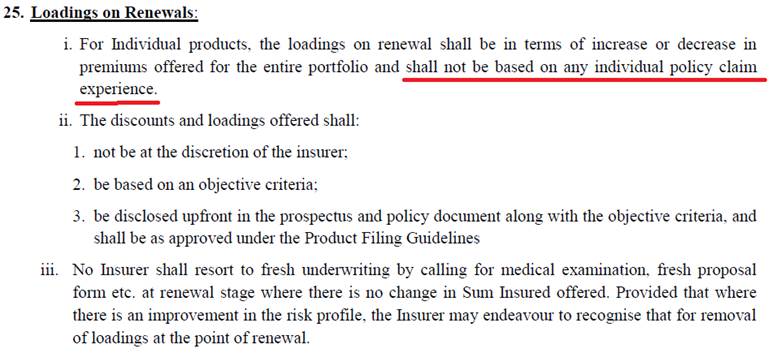
Observe that insurers can nonetheless enhance premium as you get older or because of basic revisions in underwriting coverage, however such hikes should apply equally to all policyholders of the identical plan. They can not selectively elevate premiums solely for many who made claims within the earlier coverage yr.
Nonetheless, whereas disallowing claims-based loading, IRDA neglected a loophole. Copying an excerpt from Well being Insurance coverage Laws, 2016.
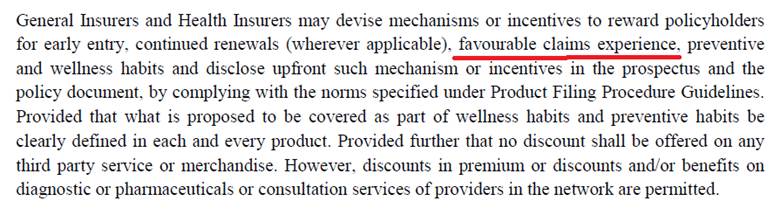
Insurers can not PENALIZE you for claiming.
However they’ll REWARD you for NOT claiming.
And that is the loophole insurers are utilizing to bypass restrictions round claims-based loading.
How Medical insurance firms are bringing again claims-based loading?
Not saying all insurers are doing this. Sadly, my insurer is doing this.
After I renewed my medical health insurance premium, I seen an odd line merchandise within the premium receipt.
Beneficial Claims Expertise Low cost = ~16,000
This {discount} is sort of 50% of ultimate premium. Successfully, in absence of such {discount}, the premium would have been nearly 50% greater. Large, isn’t it?
There was no such head within the earlier yr’s receipt. Clearly, that is newly launched and never and not using a cause. Total, the change in remaining premium (in comparison with final yr) is marginal. A part of the reason being additionally the GST reduce. Nonetheless, clearly {discount} quantity (or %) has been adjusted to maintain the premium secure.
How did the insurer calculate the beneficial claims expertise {discount}?
There was no description for “Beneficial Claims Expertise Low cost” within the coverage doc. Nonetheless, once I searched on the insurer web site, I discovered the next excerpt for one more plan. Truthful to imagine this is applicable to my plan too.

- This isn’t a binary method, the place, in case of a declare, the “beneficial claims expertise {discount}” goes to zero on the time of subsequent renewal.
- It is a laddered method, the place you begin at a sure degree of {discount}. 30% on this case. After which transfer up and down the ladder regularly based mostly on the claims expertise.
- For those who comply with the above grid, if you happen to certainly make a declare of above 1.5 lacs, your premium shall be greater by 10% (all the pieces else being the identical), simply since you made a declare. If this isn’t CLAIMS-BASED Loading, what’s. It is a deliberate try and quietly slip in claims-based loading into the coverage with out anybody noticing. In opposition to the spirit of medical health insurance laws.
- Level to Observe: This observe is gaining acceptance amongst insurers. Do learn this X thread for extra on this. Different insurers might not be following the identical construction, however there are different insurers as nicely that discover advantage on this method.
- You pay in your complimentary well being checkups. Lately, many insurers provide complimentary well being checkups yearly. Now, well being checkups are handled as a declare, regardless of how small the associated fee. At the very least my insurer counts this as a declare. Therefore, if you wish to avail complimentary well being checkup, your premium shall be greater. With this transformation, well being check-up is now not a complimentary service. You pay for the checkup by method of a better premium subsequent yr.
How may Well being Insurance coverage firms misuse this?
- Hike premiums for everybody throughout the board. As a part of your underwriting coverage.
- Give heavy “claims expertise {discount}” to those that didn’t make a declare. I’m not certain if insurers want IRDA approval on tinkering round with the ladder hole (rung interval). In my case, the ladder hole is 3%, It may have been 5% or 10% too.
- Those that made a declare can be compelled to pay the next premium. That is Claims based mostly loading.
For those who think about this method and the way it may be tinkered to short-change policyholders, the potential is large. For the insurer. Not for you.
Moving into the sneakers of an insurer
Nothing is ever so black and white. That’s why it is very important think about the angle of insurers too.
Bear in mind insurance coverage firms are for-profit enterprises and should make enough earnings.
Allow us to say the insurance coverage firm isn’t making enough cash from a medical health insurance plan. And why would that occur?
As a result of the insurer is receiving a number of claims below the coverage. Excess of it might like.
What can the insurer do?
- Shut the plan and provide everybody coated an possibility to enroll in a unique (and dearer) plan. That is allowed and has occurred earlier than. Hurts all of the policyholders. OR
- Improve premium for everybody coated below the coverage. This once more hurts all of the policyholders. OR
- Simply cost extra from the coverage holders who made the declare. Suppose the next premium is extra palatable to prospects who lately made a declare. Why? As a result of they saved some huge cash due to the insurance coverage plan.
Additional, notice that the rise in premium isn’t actually linked to the severity of your situation. The construction for discount/restoration of {discount} is disclosed within the coverage wordings. It’s not arbitrary, regardless that the insurer can all the time change the construction. Moreover, the loading (discount in {discount}) isn’t everlasting. You might have made a declare which reduces the {discount} subsequent yr. Nonetheless, if you don’t make any declare within the coming years, the {discount} % goes again up once more.
Allow us to say your base premium (earlier than claims-experience {discount}) is Rs 50,000 and it stays that method for the following 5 years. Wishful pondering, however let’s play alongside. The insurer affords a reduction of 30% on the premium. So, you pay Rs 35,000 web. You made a declare of Rs 10 lacs. In case your insurer additionally has an identical {discount} matrix as mine, your {discount} % will fall to 21%.
Assuming the pre-discount premium stays the identical Rs 50,000. You’re going to get claims renewal {discount} of 21%. Rs 10,500. Remaining premium shall be Rs 39,500.
| 12 months | Premium | Declare Quantity within the earlier yr |
Low cost % |
Internet Premium |
| 12 months 1 | 50,000 | NA | 30% | 35,000 |
| 12 months 2 | 50,000 | 1,000,000 | 21% | 39,500 |
| 12 months 3 | 50,000 | No Declare | 24% | 38,000 |
| 12 months 4 | 50,000 | No Declare | 27% | 36,500 |
| 12 months 5 | 50,000 | No Declare | 30% | 35,000 |
Observe: “Enough” is subjective. It’s not tough to see how insurers can defend any transfer below the guise of constructing enough cash.
What do I consider this?
If it walks like a duck and quacks like a duck, it’s a duck.
No quantity of disguise can cover the true intention.
Claims-based loading is nicely and actually again.
And, as policyholders, we should be cautious. The insurers could be testing the waters. As soon as this observe finds acceptance (even when reticent) within the trade, insurers could hike base premiums (this anyhow occurs) and make opposed adjustments to the claims {discount} matrix regularly. Double whammy to the policyholders.
My request to IRDA
IRDA should make clear what it meant by incentives to policyholders based mostly on “Beneficial claims expertise”. It’s clear that this incentive is getting used to bypass restrictions on claims-based loading. By way of such strikes, the insurers are sticking to the letter of the medical health insurance laws, to not the spirit of the laws.
The intent behind the point out of “Beneficial Claims expertise” should have been to reward good well being and decrease premium for many who don’t declare. Insurers are utilizing this to penalize these declare.
Would request IRDA to do one of many following 2 issues.
- Be aware of this method and put a cease to this observe. That is nothing however claims-based loading by means of again door. OR
- If IRDA permits this to proceed, it should set some guidelines round this. You can not permit insurers full discretion in structuring the “beneficial claims expertise {discount}” matrix/ladder. As an example, within the instance shared on this submit, the {discount} % goes up and down regularly. Nonetheless, there isn’t a regulation across the tempo of enhance and reduce. What if the insurer makes it binary on the draw back and makes use of a laddered method on the upside? Therefore, in case of a declare, the {discount} share falls to zero immediately however takes years to return to the bottom {discount} degree.
I did current this growth from an insurer’s perspective too. Nonetheless, given how insurers have behaved over the previous a few years, I simply don’t belief insurers. And I’m certain most policyholders would share this sense.
Due to this fact, IRDA ought to look into these delicate makes an attempt to deliver again claims-based loading. IRDA can’t permit insurers a free run on this matter.