


From the Nice Recession till 2019, U.S. labor productiveness development disillusioned. Nonfarm-business output per hour grew about 1 % a 12 months from 2010 to 2019, down from 3 % within the late Nineteen Nineties. This slowdown was particularly pronounced in manufacturing, and it coincided with a slowdown within the development of income per employee amongst public corporations. Nonetheless, since 2019, development has picked as much as twice the 2010s price, round 2 %. On this publish, I take advantage of information from corporations’ 10-Ok filings to unpack this current acceleration. I first present that the acceleration seems in public corporations’ income per employee, then doc how the positive aspects went into revenue margins, and eventually, what agency traits predicted important revenue margin will increase. The rise in revenue margins is per ongoing declines within the labor share of output.
Agency Productiveness, 2019–2025
This piece research U.S. Compustat corporations throughout each manufacturing and providers over 2010–2025, damaged into two intervals: 2010–2019 and 2019–2025. I drop agriculture, utilities, finance, actual property, and public administration, because of the identified challenges of productiveness measurement in these industries.
Nonfarm-business output per hour grew 1.0 % a 12 months from 2010 to 2019 and a pair of.2 % a 12 months from 2019 to 2025. In Compustat, I discover a related qualitative development acceleration. Actual income per employee—gross sales deflated by trade output costs, divided by employment—traces the identical flip, from 0.7 % to 2.2 % a 12 months over the identical time intervals.
The chart under illustrates this development, exhibiting that each income per employee amongst public corporations and output per hour are accelerating within the current interval. Throughout all datasets, the labor productiveness uptick is actual.
Labor Productiveness and Agency Income Per Employee Accelerated Collectively in 2019-2025
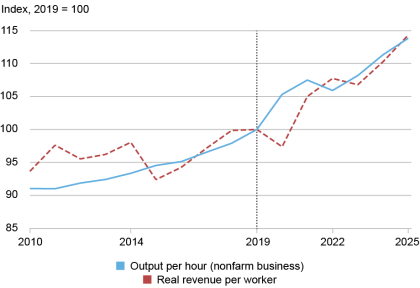
Notes: Labor productiveness, listed to 2019 = 100: Chart exhibits BLS nonfarm-business output per hour and Compustat actual income per employee.
Increased income per employee on the agency stage doesn’t point out who positive aspects from this elevated income. The extra income might go to staff, as corporations compete for labor via greater wages, or accrue to corporations in revenue margins. Agency-level information let me measure how corporations’ revenue margins modified over time. I discover how revenue margins modified between 2019 and 2025 and what agency traits predicted markup positive aspects.
Agency Revenue Margins
A revenue margin is revenue divided by gross sales: the share of every gross sales greenback the agency retains after paying its prices. The gross margin subtracts the direct price of manufacturing (price of products offered), whereas the working margin additionally subtracts overhead (promoting, basic, and administrative expense, which in Compustat usually consists of R&D). If productiveness positive aspects had been flowing to corporations’ earnings, margins ought to present it. By the 2010s margins had been flat: gross margins grew about 0.4 % a 12 months from 2010 to 2019, and working margins had been roughly flat. Each then turned up: on common, gross margins went from about 34 % of gross sales in 2019 to 37 % in 2025 (1.3 % development per 12 months), and working margins from 16 % to 18 % (2.4 % development per 12 months).
Gross and Working Revenue Margins Elevated in
2019-2025
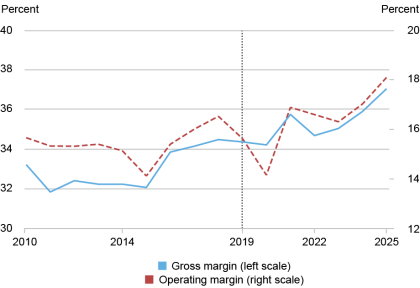
Notes: Compustat gross margin (COGS) and working margin (OPEX), 2010–2025, sales-weighted; gross on the left scale, working on the proper scale.
Which Corporations Noticed the Largest Positive factors?
Lastly, I ask whether or not corporations that put money into intangibles (e.g., analysis and improvement, or R&D) skilled the biggest positive aspects. In earlier work, we confirmed that whereas productiveness development in manufacturing slowed within the 2010s, R&D depth in manufacturing continued to rise. Does R&D depth predict greater revenue margins within the current period?
Corporations that entered the interval with greater R&D expenditure relative to gross sales noticed bigger subsequent positive aspects: corporations with 10 % extra R&D expenditure relative to gross sales in 2019 noticed about 0.7 % greater operating-markup development over 2019–2025, and 0.5 % over 2022–2025. Corporations with greater capital depth didn’t see such a major sample. This sample is per returns to intangible depth reasonably than capital depth. This implies a probably vital position for investments in know-how and intangibles in driving markups.
Measured productiveness has risen since 2019 in each combination and agency information, ending greater than a decade of sluggish development. A part of the positive aspects surfaced with wider revenue margins: on an affordable baseline, the working margin rose over 2 % a 12 months from 2019 to 2025. R&D depth seems to be an vital predictor of margin development for corporations, per the rising returns to high-tech corporations and corporations which have invested in intangibles since COVID. Whether or not these rising margins are returns to important funding in intangibles or purely a windfall for corporations is a subject to discover in future work.
Jeremy Pearce is a analysis economist within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
cite this publish:
Jeremy Pearce, “Income per Employee Is Up. Are Corporations Getting a Bigger Share?,” Federal Reserve Financial institution of New York Liberty Road Economics, October 15, 2026, https://doi.org/10.59576/lse.20261015
BibTeX: View |
Disclaimer
The views expressed on this publish are these of the creator(s) and don’t essentially mirror the place of the Federal Reserve Financial institution of New York or the Federal Reserve System. Any errors or omissions are the accountability of the creator(s).