

As my public fairness portfolio will get obliterated because of being chubby tech shares, I began dusting off my resume to go again to flipping burgers at McDonald’s. Then midway by means of the appliance, I wiped away my tears and took a deep breath.
As each long-time investor is aware of, the secret is survival. If you may make it by means of the downturn, good issues normally await on the opposite aspect.
We’re not in an official bear market, but. However loads of particular person tech names have already fallen by over 20%, and while you’re chubby these names, the index’s official standing does not matter a lot.
So I believed it could be useful for individuals who are retired, or who’re shut, to debate the positives of going by means of a downturn. We’ll additionally evaluation how lengthy downturns normally final so we will higher put together.
The Wealth Impact Was Numbing A Lot Of Ache
Because the midterm elections confirmed, lots of people should not pleased with the way in which our nation has been led. However the discontent did not seem in a single day. The inventory market was merely appearing as a large dose of Lidocaine.
So long as shares stored going up, we might extra simply bear larger oil costs, larger meals costs, larger housing prices, larger school tuition prices, and explosive medical prices. In any case, our funding returns had been rising sooner than inflation. $6 for a gallon of fuel stings lots much less when your brokerage account is up $50,000 for the yr.
However that tolerance for rising prices disappears the second our investments begin dropping cash. All of a sudden, $89 a pound for wagyu feels private.
When the wealth impact vanishes, customers in the reduction of. Fewer dinners out. Fewer holidays. The new automobile will get pushed out one other yr. With declining company profitability, firms speed up layoffs to guard margins. The newly unemployed tighten spending even additional.
Rinse and repeat till economists formally declare a recession six months after everyone already felt it.
In case you see the writing on the wall, you need need to get forward of the layoffs by negotiating your individual severance bundle. In case you do, you’ll in all probability have a neater time getting a a lot better exit provide than being lumped with the lots.
Sequence Of Returns Danger Is The Actual Concern For Retirees
In case you’re newly retired, your greatest worry is sequence of returns threat. That is the chance of struggling massive losses early in retirement whilst you’re additionally withdrawing cash to dwell on. Try this for too lengthy and your portfolio might by no means get better.
Lose sufficient and also you get pressured again to work. No person who has tasted freedom needs to return to Monday morning standing conferences and efficiency evaluations from somebody half their age.
Retirees who dwell off their investments ought to really feel worse a few bear market greater than the typical employee. We don’t have a paycheck to cushion the blow. We might not have a lot spare money circulation to purchase the dip both.
However this is the important thing level. In case your investments can survive the correction or bear market, you need to truly really feel good throughout a downturn. Not ecstatic, however comparatively good. As a result of the choice is working arduous for no monetary reward.
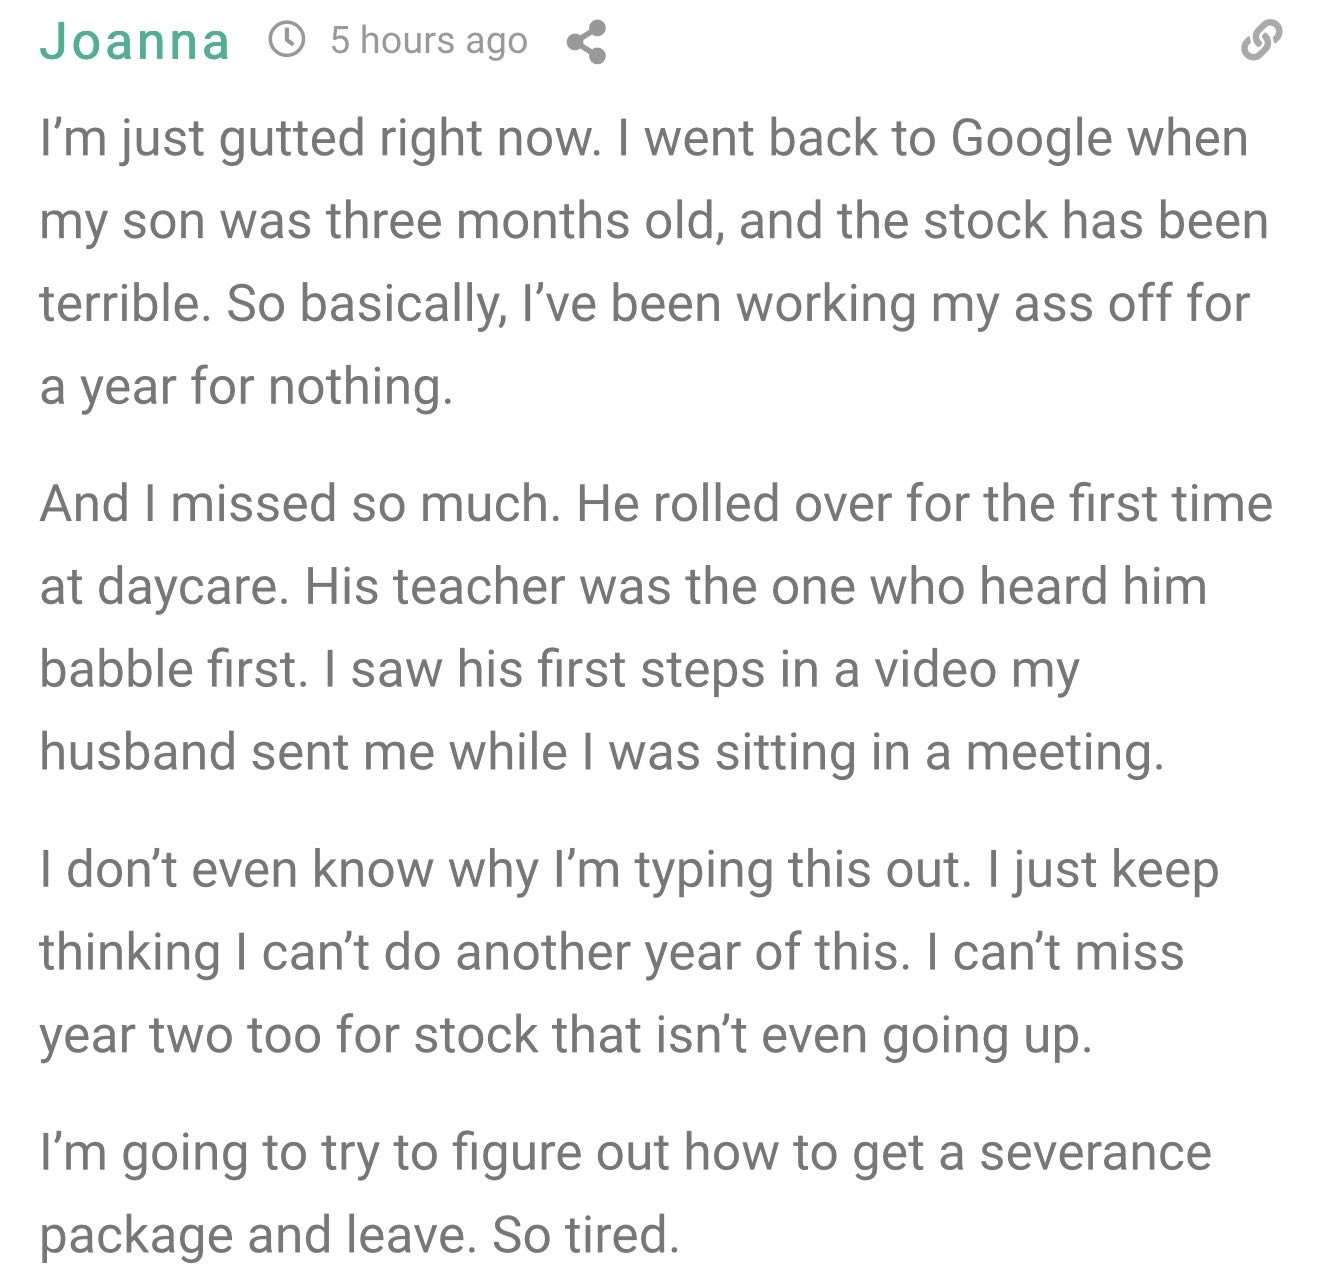
How are you aware when you can survive? Run by means of this fast guidelines:
- You may have over one yr of dwelling bills in money or Treasury payments, so that you by no means should promote shares on the lows.
- Your passive earnings from leases, bonds, and dividends covers a significant chunk of your bills.
- You possibly can lower discretionary spending by 20% to 30% with out feeling depressing.
- If shares fell one other 35% from right here, you may nonetheless get up at 2am in chilly sweats, however you possibly can sitll pay your payments.
How Lengthy You will Have To Intestine It Out
So how lengthy will the ache final? Historical past presents some consolation, supplied you might have the endurance of a guardian ready for a toddler to placed on his footwear whereas already quarter-hour late.
In accordance with Capital Group, the S&P 500 has dropped 10% or extra about as soon as each 18 months since 1954. A 20%+ bear market exhibits up about as soon as each six years.
In different phrases, when you plan on a 40-year retirement, count on roughly 25 corrections and 6 or seven bear markets. Declines are the value of admission, not an indication the world is ending. Get used to them.
| Decline | How typically it occurs | Common size, excessive to low |
|---|---|---|
| 5% or extra | About twice a yr | 46 days (1.5 months) |
| 10% or extra (correction) | About as soon as each 18 months | 133 days (4.4 months) |
| 15% or extra | About as soon as each 3 years | 247 days (8 months) |
| 20% or extra (bear market) | About as soon as each 6 years | 402 days (13 months) |
Supply: Capital Group, S&P 500 knowledge from 1954 by means of 2025.
Hartford Funds, utilizing Ned Davis Analysis knowledge going again to 1928, counts 27 bear markets. Shares fell 35% on common and took 289 days, or about 9.6 months, to hit backside.
Bear markets had been much more frequent in the course of the Melancholy period. Since 1945, there have been 15, or one about each 5.1 years.
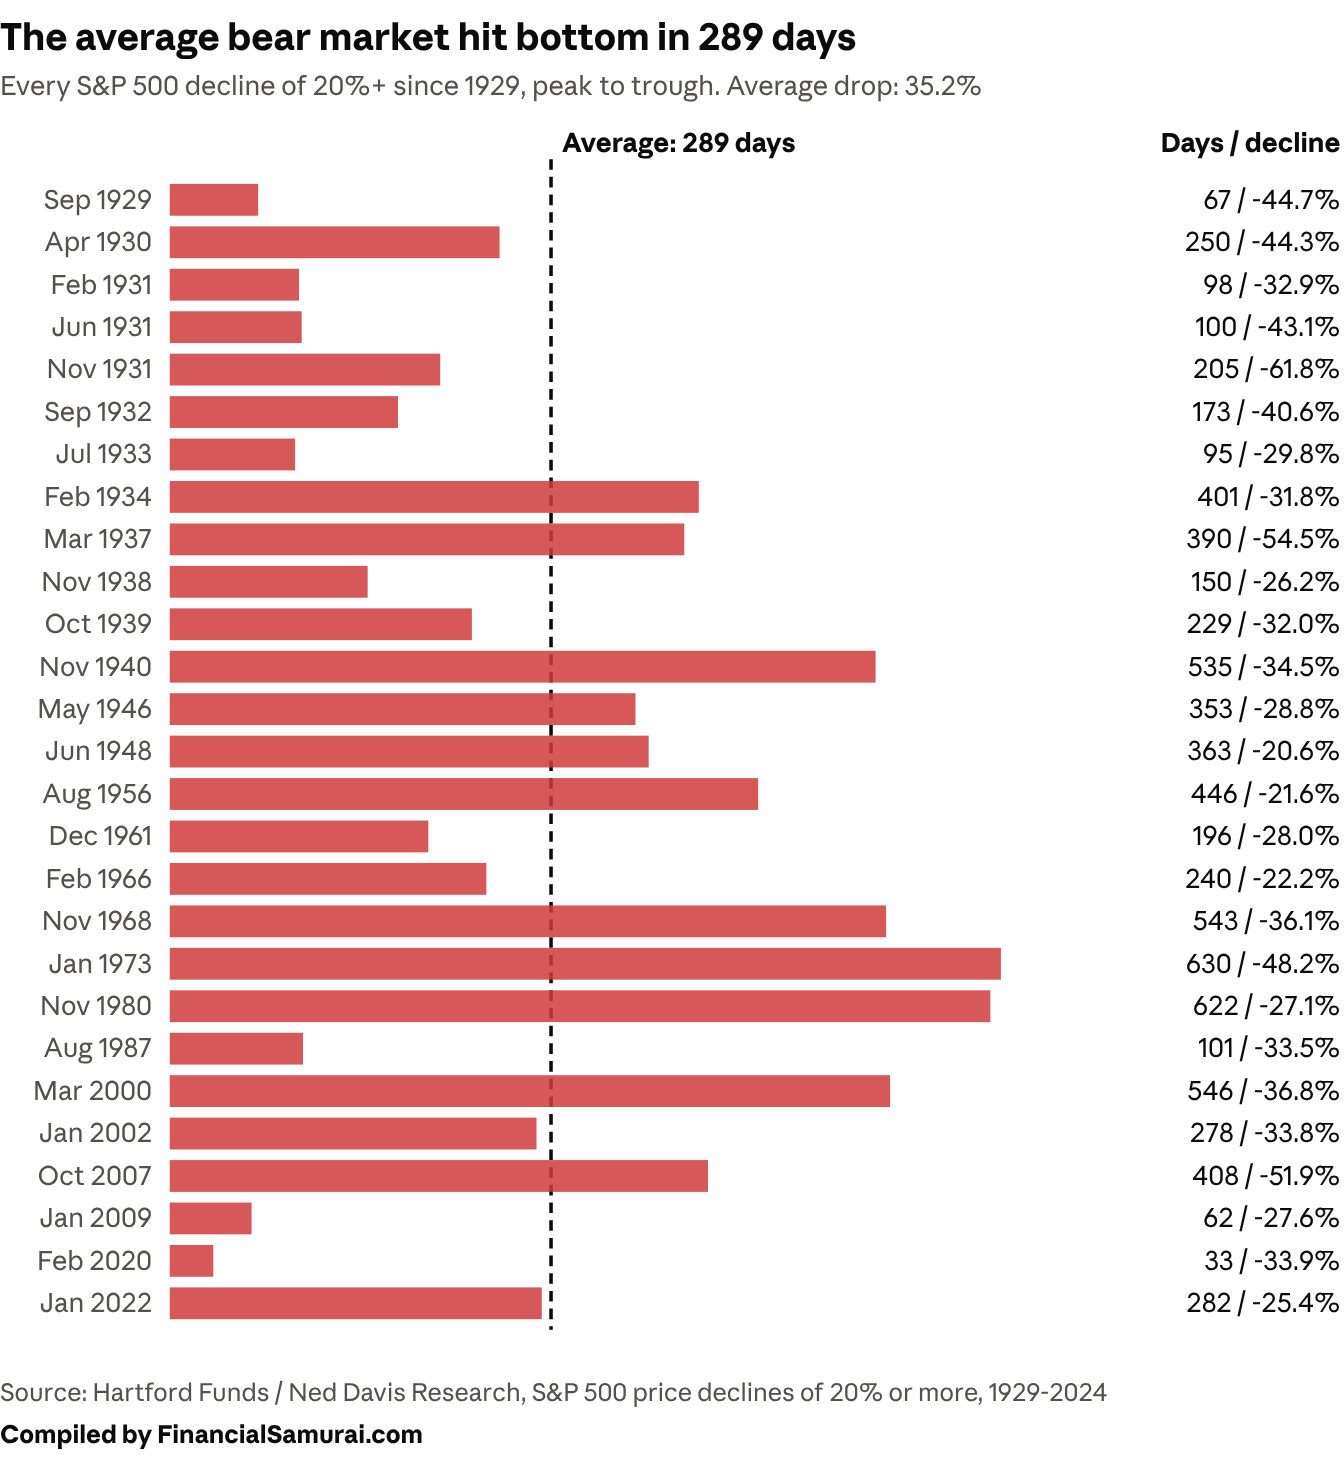
Two caveats earlier than you get too snug. First, these figures measure peak to trough. Getting again to your outdated excessive takes longer. Second, the 1973 and 1980 bear markets every dragged on for greater than 600 days. Averages are good till you are dwelling by means of the outlier.
The Inventory Market At all times Recovers
However this is the half that ought to make everybody really feel higher. Each S&P 500 correction since 1929 has been adopted by a restoration, and the typical return within the first yr after the underside was 52%. And the recoveries are occurring faster now, if we embrace the 2025 Liberation Day and 2026 Iran Struggle occasions.
Hartford additionally discovered that about 42% of the S&P 500’s strongest days over the previous 20 years occurred throughout bear markets. Promote in a panic and you will probably miss the rebound.
My takeaway: In a sensible worst-case situation, plan on gutting out roughly 12 to 18 months of ache from peak to trough, with an extended tail to totally get better. That is why the one to 2 years of money is okay, particularly with rates of interest nonetheless excessive.
The Much less You Work, The Higher You Really feel
The existential dilemma of a bear market is that this:
- Do you’re employed more durable and threat working in place, and even dropping cash?
- Or do you’re employed much less, play extra golf, pickleball, and poker, and spend extra time together with your children, as a result of there is not any longer a lot level to the grind?
The right reply is to work much less arduous and YOLO extra. Let me clarify utilizing an idea I name Return On Effort (ROE).
Throughout a bull market, working much less arduous truly will increase your Return On Effort as a result of your investments present a lot of the returns. Except you might have a gross sales job or another position tightly correlated to efficiency, an additional 15 hours per week not often strikes the needle. You are higher off driving the group’s progress.
Throughout a bear market, working arduous to run in place or lose cash makes even much less sense. There’s nothing you are able to do to stem declining shopper confidence, new socialist insurance policies, larger taxes, and so forth. Your boss is not handing out raises whereas income is falling. See Google’s collapse after having such an enormous lead within the AI race.
If something, your additional effort earns you the privilege of doing the work of three colleagues who simply bought laid off. Congratulations in your 0% elevate.
So you’re employed much less arduous to guard your declining Return On Effort. Not since you’re lazy. Since you’re rational.
By Definition, Retirees Work The Least
With this logic in thoughts, who works the least? The unemployed, the standard retiree, and the early retiree.
Subsequently, as long as your investments can face up to the beating, you are going to be simply high-quality. Psychologically, as a retiree, you need to push your self to do much less and have extra enjoyable.
Happiness is relative. Throughout a bull market, loads of early retirees really feel a twinge of FOMO watching former colleagues get promoted and money fats RSU checks. Throughout a bear market, that FOMO flips. No person envies the man grinding by means of a reorg whereas his inventory comp will get lower in half.
Silver Linings Of A Bear Market For Everybody
Whether or not you’re retired or nonetheless grinding away, a downturn presents some actual perks.
1) Issues get cheaper. When demand falls, so do costs for journey, accommodations, and finally actual property. Retirees with versatile schedules can journey off-peak and rating offers that working dad and mom can solely dream about. Employees seeking to purchase their first dwelling might lastly face much less competitors.
2) You get to buy the sale. Retirees with passive earnings and a money buffer get to purchase when others are pressured to promote. Employees get a good steadier benefit. Each paycheck and 401(ok) contribution now picks up extra shares at decrease costs. Regular earnings plus a very long time horizon makes you the pure purchaser in a bear market.
3) Your children get to purchase the dip. I’ve written about learn how to use inventory market downturns to make your children millionaires. As a father, that is my favourite advantage of a bear market. As a result of the fairness prepare lastly stops lengthy sufficient for youths to catch up and hop on board. A toddler has 50+ years of compounding forward. A 30% drop right now is a rounding error by the point they’re of their 50s.
4) Tax strikes get higher. Tax-loss harvesting offsets future beneficial properties. Roth conversions at depressed valuations imply you pay much less tax on the identical variety of shares, and all of the restoration occurs tax-free.
5) The AI hedge is doing its job. Public AI shares have gotten crunched. However there’s a flip aspect. If AI firms are struggling to justify their valuations, AI in all probability isn’t wiping out white-collar work as quick as everybody feared. That’s comforting for our youngsters, and for each employee questioning if their job will exist in 10 years.
6) You get humbled and construct resilience. Being closely chubby tech felt sensible for years. Bear markets remind us we’re not as sensible as we thought. My recommendation after each large win is to go scrub all of your bogs. Each downturn you survive makes you a calmer, higher investor for the following one. In case you’re nonetheless working, simply make certain your emergency fund is stable, as a result of layoffs have a tendency to point out up on the worst time.
Calm Comes From Management
You possibly can’t management tech volatility, rates of interest, or who wins elections. However you possibly can management the way you spend your time throughout a downturn.
The market will finally get better. It at all times has. When it does, the individuals who grinded by means of the downturn might be exhausted. These of us who leaned into household, buddies, and health might be effectively rested. Each teams will survive, which is what issues most.
In case you’ve been desirous about retiring, a bear market could also be the most effective time to tug the set off. It signifies that regardless of the carnage, your funds are robust sufficient so that you can break away. Ready for the following bull market can really feel safer, nevertheless it’s backwards.
In case your funds can help retirement whereas shares are down 20% or extra, your plan has already handed the stress take a look at. You’re not retiring on inflated numbers that might vanish within the subsequent correction. And since bear markets don’t final endlessly, a restoration might carry your retirement ahead with a tailwind as an alternative of a headwind.
Evaluate that to the one who retires on the peak of a bull market, solely to look at their portfolio drop 30% within the first two years. That’s sequence of returns threat at its worst.
So go play within the park. Take your children to the seaside. A downturn is the most effective time to benefit from the freedom you labored so arduous to construct, and perhaps the most effective time to assert it.
Reader Questions
Are you discovering it extra comforting to be retired throughout a downturn, or extra disturbing? How a lot of your portfolio would wish to fall earlier than you’d significantly contemplate going again to work? Do you agree that working much less arduous in a bear market is the rational transfer, or is that only a cop-out for the lazy? And for these nonetheless working, has the market selloff made you rethink how arduous you are grinding? Are you utilizing the downturn to fund your children’ funding accounts?
Construct Wealth By way of Each Market Cycle
If you’d like a roadmap for getting by means of downturns and popping out richer, decide up a duplicate of Millionaire Milestones: Easy Steps To Seven Figures, a USA Right now bestseller. It covers learn how to hold investing when everyone else is scared, so you possibly can attain monetary independence sooner.
To get my posts in your inbox as quickly as they’re revealed, ad-free for the primary few hours, enroll right here. Be part of 60,000+ others and join my free weekly e-newsletter right here. I’ve been writing from firsthand expertise since 2009, and I’ll hold sharing what I’m seeing and doing with my very own cash throughout this downturn.