


Publish Views:
91
At Truemind Capital, our broad understanding has been:
- Diversification throughout asset courses, sectors and geographies helps handle threat.
- Wealth preservation stays as vital as wealth creation, significantly in unsure markets.
- Asset allocation wants to stay dynamic, with portfolios actively rebalanced as alternatives and dangers evolve.
- Sustaining liquidity inside portfolios stays essential, enabling well timed shifts and efficient deployment throughout market dislocations.
If the April-June quarter ended with hopes of peace, July-September confirmed how shortly the state of affairs may change. Brent crude, which had fallen to round US$72-73 a barrel by the top of June, climbed above US$100 in July and reached round US$109 in mid-September as tensions in West Asia flared once more. The renewed rise in oil costs introduced inflation, rates of interest and strain on the rupee again into focus.
Fairness Market Insights:
Indian equities had a tough quarter. The Sensex and Nifty 50 every declined by round 5.2% between July and September, with a lot of the autumn coming in September. Greater crude oil costs, rising US bond yields, a weaker rupee and renewed overseas investor promoting weighed closely on sentiment. Home institutional buyers offered some help, however this was not sufficient to forestall the decline.

The present weak spot additionally must be seen within the context of the previous two years. The Sensex closed at roughly 84,300 on September 30, 2024, after a robust bull run that had taken the index to contemporary document highs. By September 30, 2026, it had fallen to round 72,480, leaving it roughly 14% beneath its stage two years earlier. For buyers, this has been a protracted interval of restricted progress. We consider the best way ahead relies upon largely on company earnings.
The quarter passed by additionally reinforces a priority we had highlighted earlier: revenues might develop, however increased prices can forestall that development from translating into stronger income. Nifty 50 income grew 18.4% year-on-year, whereas working margins for non-financial corporations contracted by round three proportion factors to twenty.5%. Revenue development stood at 11.8%. Earnings development estimates for FY27 had been additionally revised right down to 9.2%, from 16.4% in March.
For this reason a market correction alone is just not sufficient to make equities enticing. Valuations should be thought-about alongside the earnings corporations can realistically ship. We might search for a sustained enchancment in earnings earlier than anticipating a stronger and extra sturdy restoration in Indian equities.
Within the US, the S&P 500 gained round 2% in the course of the quarter, however the rally remained concentrated in giant expertise corporations and AI-related themes. On the similar time, market management started to broaden, with buyers displaying higher curiosity in alternatives past a few of the most crowded AI-related trades. This doesn’t imply that the long-term potential of AI has disappeared. Nonetheless, the dimensions of funding, excessive expectations and questions round how sustainably these investments will generate returns make it vital to evaluate valuations and dangers fastidiously.
For buyers, the lesson is to not react to each change in market sentiment. We proceed to consider that oil costs, rates of interest and forex actions can have an effect on markets in ways in which particular person inventory choice can not absolutely offset. Diversification, affordable valuations and sufficient liquidity stay vital, significantly when the outlook is that this unsure.
What We Are Doing
We proceed to take care of fairness allocations within the 30-60% vary, relying on particular person threat profiles, with a choice for large-cap and value-oriented investments diversified throughout sectors and geographies.
One improvement now we have been paying shut consideration to is the altering investor urge for food for AI-related investments. The chance offered by AI stays vital, however the valuations of some corporations, the dimensions of capital being dedicated to infrastructure, and questions round how shortly these investments will generate returns have made the commerce extra weak to altering expectations. The priority is just not essentially that demand for AI will disappear, however that the costs buyers are keen to pay for that development might turn into, economically, more durable to justify.
That is additionally why we consider portfolios mustn’t rely excessively on anyone market, sector or funding theme. Reasonably than attempting to foretell when the following shift in market management will happen, we’re centered on diversifying throughout geographies and figuring out alternatives pushed by totally different sources of development. Our worldwide portfolios present publicity to markets resembling Hong Kong and China, Singapore, Brazil, the UAE and Japan, whereas our healthcare allocation gives publicity to companies addressing real-world wants past the AI infrastructure cycle.
With valuations remaining demanding in components of the market, we proceed to favour persistence over chasing momentum. Sustaining liquidity and reviewing portfolios as circumstances change permits us to behave when extra enticing alternatives emerge, whereas preserving investments aligned with purchasers’ long-term targets.
Debt Market Insights:
One of many vital developments in the course of the July-September quarter was the sharp rise in authorities bond yields throughout main economies. The US, UK and Japan all noticed borrowing prices climb to ranges not seen in years, as buyers reassessed the outlook for inflation, rates of interest and authorities borrowing. India was not insulated from this pattern. Its 10-year authorities bond yield rose from round 6.75% on the finish of June to roughly 7.19% by September 30.
For India, this got here at a time when the outlook for inflation was turning into extra unsure once more. The rise in crude oil costs raised considerations about imported inflation, whereas a weaker rupee added to the strain. On the similar time, increased yields in developed markets made international buyers extra delicate to the returns obtainable throughout international locations. This created a difficult backdrop for Indian bonds, at the same time as measures to draw overseas capital started to enhance inflows.
Internet non-resident deposit inflows reached US $ 119.2 billion between April and August, in contrast with US $ 5.6 billion throughout the identical interval a 12 months earlier. Nonetheless, stronger inflows didn’t forestall longer-term bond yields from rising. World interest-rate actions, inflation considerations and overseas investor promoting continued to weigh in the marketplace.
Home liquidity additionally performed a task. Robust deposit inflows contributed to surplus banking-system liquidity, which the RBI absorbed by means of its liquidity operations. This led to a steeper yield curve, serving to ease some short-term charges, at the same time as longer-term authorities bond yields rose.
Our Method to Debt Allocation
For us, the mix of elevated international bond yields and renewed inflationary pressures in India requires warning on the interest-rate outlook. The RBI’s 25-basis-point repo price hike to five.50% on October 7, after the quarter ended, reinforces the significance of this threat. We consider rates of interest may stay elevated, with additional hikes attainable if inflationary pressures persist. That is one purpose now we have been cautious about taking aggressive positions in longer-duration debt.
At Truemind Capital, now we have consciously averted aggressive period calls over the previous two to 3 years. The developments throughout this quarter strengthened the rationale for this method. With inflationary pressures excessive, geopolitical dangers elevated and bond yields rising throughout main economies, we consider you will need to stay measured about how a lot interest-rate threat portfolios take.
We proceed to favour short- and intermediate-duration devices that supply a stability of yield, liquidity and decrease mark-to-market threat. The ten-year G-Sec yield rose from round 6.70–6.75% in July to roughly 7.15-7.20% by late September. One-year CDs had been providing yields of round 7.45–7.55% as of mid-October. These increased yields have improved the earnings obtainable from debt investments in contrast with just a few months in the past. Nonetheless, with the RBI having raised charges and the potential of additional hikes remaining, we see no compelling purpose to increase period aggressively but.
Debt stays an vital stabilising anchor in a portfolio, offering common earnings, serving to protect capital throughout unsure durations and creating the flexibleness to rebalance into equities when markets supply worth.
Different Asset Courses:
Gold: Home Gold ETFs delivered a gentle return of 4.81% in the course of the July-September quarter, pushing their trailing 12-month return to a powerful 26.85% as of September 30, 2026.
The asset class continues to show its very important function as a structural portfolio anchor. Whilst treasured metals confronted short-term international profit-taking in late September resulting from a surging US greenback index, investor urge for food reached an inflection level. Home web inflows into Indian gold ETFs surged by 71% month-on-month to hit Rs 4,451 crore in September, as capital actively sought refuge from a correcting fairness market.
We proceed to take care of gold as a key non-correlated diversifier, structurally underpinned by aggressive multi-year central financial institution accumulation.
Actual Property: Housing gross sales throughout the highest seven cities rose about 3% YoY in July-September, a turnaround from final quarter’s 6% fall. New launches rose 18% and costs 7%. With launches operating nicely forward of gross sales, unsold stock is up about 12%. We proceed to view actual property as a complementary, not core, allocation given its illiquidity, cyclical nature and excessive transaction prices.
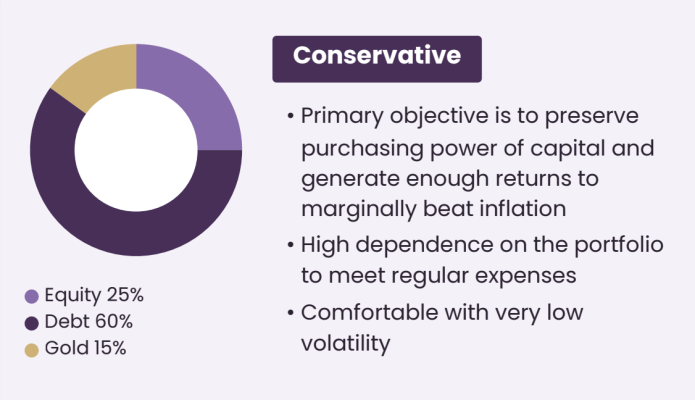
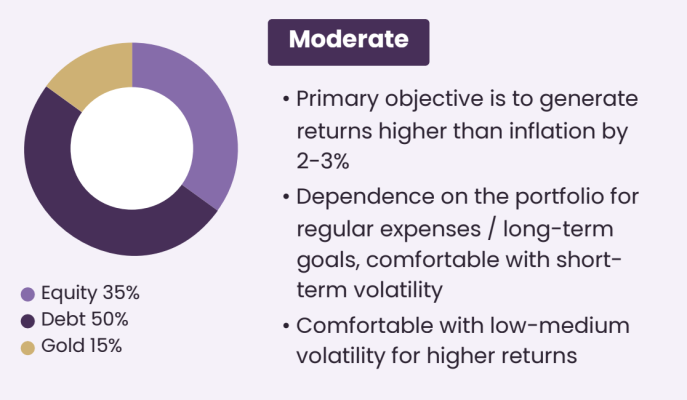
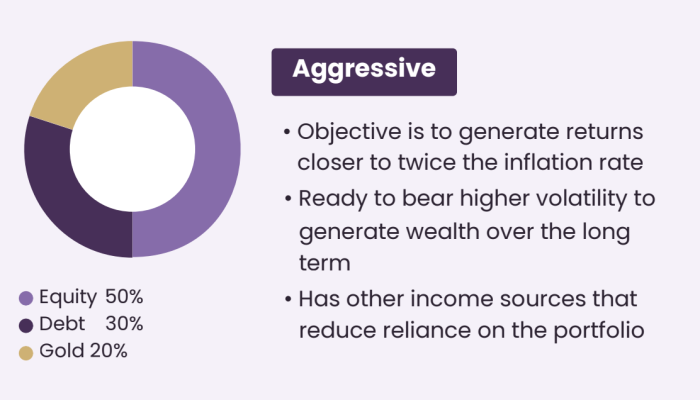
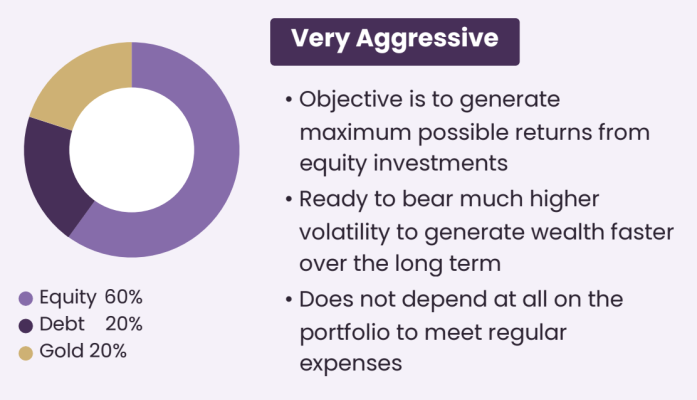
Truemind’s Mannequin Portfolio – Present Asset Allocation
Private Finance Capsule:
Macro-calls that labored and can proceed to work
Attention-grabbing World Themes Past Indian Markets
Why SEBI RIAs are the Greatest Wager for Traders
At Truemind Capital, we assist individuals obtain peace of thoughts by managing their monetary planning and investments in India and globally diversified portfolios.
For an introductory name, attain out to us at: https://www.truemindcapital.com/contact-us